Our update provides key takeaways from President Trump’s Executive Order and its potential impact on various energy initiatives as well as the M&A and capital markets outlook for energy companies.
On January 20, 2025, President Donald Trump signed executive order “Unleashing American Energy“ (the Executive Order). This update discusses key takeaways from the Executive Order and the potential impact of the Executive Order on various energy initiatives as well as the M&A and capital markets outlook for energy companies. For a broader discussion of the twenty-six executive orders President Trump signed on January 20, 2025 and the major regulatory and policy issues energy industry experts will be monitoring in the coming days, please refer to Trump 2.0 on Energy: Ten Items to Watch.
1. Overview of the Executive Order
The Executive Order is intended to reverse years of what the new administration characterizes as “burdensome and ideologically motivated regulations” which have impeded the development of America’s abundant energy and natural resources. By implementing new policies and revoking several executive orders from prior administrations, the Executive Order seeks to promote and encourage energy exploration and development by revising the permitting process, revoking or revising regulations, and promoting domestic mining, amongst other changes.
2. Impact on Oil & Gas Leasing and Permitting
The Executive Order lays out policies of the United States which include (a) encouraging energy exploration and production of Federal lands and waters, including on the Outer Continental Shelf, in order to meet the needs of US citizens and solidify the United States as a global energy leader and (b) establishing the United States’ position as the leading producer and processor of non-fuel minerals, thus creating jobs and prosperity at home.
The heads of all federal agencies are ordered to review, revise, or rescind all existing regulations, orders, guidance documents, policies, or other agency actions, that impose an undue burden on the identification, development or use of domestic energy resources, particularly “oil, natural gas, coal, hydropower, biofuels, critical mineral, and nuclear energy resources.” Agency heads are instructed to develop and begin implementing action plans to suspend, revise or rescind any such unduly burdensome agency actions within 30 days of the Executive Order (Feb. 19, 2025).
The chair of the Council of Environmental Quality (CEQ) is ordered to provide guidance on implementing the National Environmental Policy Act (NEPA) and propose rescinding burdensome NEPA regulations in order to expedite and simplify permitting. Further, the Executive Order directs various federal agencies to eliminate delays within their permitting process. In doing so, the Executive Order intends to streamline the NEPA judicial review process and promote the permitting and construction of critical infrastructure whilst providing greater certainty in the Federal permitting process.
These changes are expected to streamline and promote domestic exploration and production on both onshore and offshore federal oil and gas leases. While challenges from environmental groups are likely, we expect significantly more federal lease sales to be conducted, including in federal lands that had never previously been considered for sale. Environmental review of well and pipeline permit applications will still occur, but the process will likely be overhauled and permit approvals will likely be granted significantly faster in an effort to promote resource development.
3. Pause on Inflation Reduction Act Funding on Various Energy Projects
Pursuant to the Executive Order, all agencies are to immediately pause the disbursement of funds appropriated through the Inflation Reduction Act (Public Law 117-169, IRA) or the Infrastructure Investment and Jobs Act (Public Law 117-58, IIJA). On January 21, 2025, the acting director of the Office of Management and Budget (OMB) issued guidance clarifying that the pause only applies to funds supporting programs, projects or activities that contravene the policies of the Executive Order and that agency heads may disburse funds as they deem necessary after consulting with OMB. Given that the Executive Order indicates a lack of support for solar and wind, while remaining silent on geothermal or carbon capture, utilization, and storage (CCUS), IRA and IIJA funding for geothermal and CCUS projects may not be suspended for long, if at all. However the future of federal funding for solar and wind-related projects is more uncertain.
It is important to note that a pause on federal funding under the IRA is not tantamount to a revocation of tax credits under the IRA. For further discussion on the impact to IRA Tax Credits, please refer to Trump 2.0 on Energy: Ten Items to Watch.
4. Changes to Environmental Analyses and Carbon Monitoring
The Executive Order aims to streamline the permitting process, reduce regulatory burdens, and shift the focus away from certain climate-related metrics. As touched on in Section 2 above, it does so in part by revoking prior Executive Orders related to Environmental regulations under NEPA and directing agencies to make changes related to consideration and calculation of greenhouse gas emissions.
- Revocation of Executive Order 11991: Revokes Executive Order 11991 (Carter, May 24, 1977), which amended Executive Order 11514 (Nixon, March 5, 1970). Executive Order 11991 tasked CEQ with issuing regulations to federal agencies for implementing the procedural provisions of NEPA, and directed that federal agencies comply with those regulations unless such compliance would be inconsistent with statutory requirements.
- NEPA Implementation: Tasks the Chairman of CEQ with providing guidance to expedite and simplify the permitting process under the NEPA. Agencies are required to prioritize efficiency and certainty in the permitting process, minimizing delays and ambiguity.
- Adherence to Legislated Requirements: Agencies must adhere strictly to legislated requirements for environmental considerations, using robust methodologies and avoiding arbitrary or ideologically motivated methods.
- Disbanding the Interagency Working Group on the Social Cost of Greenhouse Gases (IWG): The IWG is disbanded, and all its guidance, instructions, and documents are withdrawn. This includes the withdrawal of the Technical Support Document on the social cost of carbon, methane, and nitrous oxide.
- Elimination of the Social Cost of Carbon Calculation: The calculation of the social cost of carbon is deemed arbitrary and potentially harmful to the U.S. economy. The EPA Administrator is directed to issue guidance to address these issues, including the potential elimination of the social cost of carbon calculation from federal permitting or regulatory decisions.
- Review of EPA’s Endangerment Findings: The EPA Administrator, in collaboration with other agencies, is to review the legality and applicability of the EPA’s findings on greenhouse gases under the Clean Air Act.
- Review of Agency Actions: Agency heads must review existing regulations and actions to identify those that burden domestic energy development, and create and implement plans to suspend, revise, or rescind identified burdensome actions, in collaboration with OMB and the National Economic Council (NEC).
- Revocation of Executive Orders: Revokes a dozen of President Biden’s Executive Orders related to environmental justice, climate change, and the environment.
There are various agency deadlines related to the above NEPA and carbon monitoring changes which will need to be achieved as part of the Executive Order.
- Within 30 days:
- Agency heads must develop and begin implementing action plans to suspend, revise, or rescind burdensome actions.
- The Chairman of CEQ must provide guidance on implementing NEPA.
- Agencies must submit reports identifying instances where enforcement discretion can advance policy goals.
- Within 60 days:
- The EPA Administrator must issue guidance addressing the inadequacies of the social cost of carbon calculation.
The Executive Order mandates a review and revision of regulations that are seen to burden domestic energy development, which could lead to faster permitting processes and reduced compliance costs for energy companies. CEQ is expected to be stripped of its power to issue binding NEPA regulations for federal agencies. Because most agencies have their own regulations to implement NEPA, this change will not eliminate NEPA reviews. The elimination of the social cost of carbon calculations is intended to lessen the importance of climate change analysis in permitting decisions. Industry should prepare for streamlined regulatory requirements and potential shifts in the rigor required to prepare environmental analyses and environmental impact statements, with agencies tasked with focusing on efficiency and adherence to strict legislative text and these new guidelines. We expect NEPA litigation to increase as environmental groups challenge these executive orders. Energy sector companies should stay informed about changes to ensure compliance and leverage opportunities for expedited project approvals over the coming months as these agencies undergo a potentially major overhaul of NEPA and carbon reporting.
5. Impact on LNG Export Projects
The Executive Order directs the Secretary of Energy to “restart reviews of applications for approvals of liquified natural gas (LNG) export projects,” which, coupled with President Trump reversing the Biden administration’s pause on LNG permits on day one of his second term by rolling back President Biden’s executive order that paused granting LNG export authorizations, suggests an emphasis on increasing LNG exports by the current administration. LNG exports are a key driver for investment in natural gas assets, midstream projects, and CCUS, thus such a change should be positive for investment and dealmaking in these areas.
For further discussion on the future of LNG under the Trump administration, please refer to Trump 2.0 on Energy: Ten Items to Watch.
6. Impact on Mergers & Acquisitions and Antitrust in the Energy Industry
While the Executive Order promises to reduce administrative hurdles to traditional energy projects, we expect oil and gas companies to operate largely consistently with the approach they have taken in the post-pandemic era, with an emphasis on capital discipline, efficient returns, and consolidation. The Executive Order will likely enhance the value of companies with asset bases that include large portfolios of leases on federal lands or in the Outer Continental Shelf, but from a dealmaking perspective, the administration’s attitude shift toward traditional energy is likely to also be seen in the antitrust review process. With the change in political leadership and an emphasis on encouraging investment in natural resources in the name of energy security, the Federal Trade Commission (FTC) is unlikely to be as hostile to mergers and acquisitions in the energy industry as the previous administration. For example, the FTC conducted large-scale Second Request investigations into a range of industry transactions as part of its antitrust reviews under the Hart-Scott-Rodino (HSR) Act, following requests from Democratic leadership in the Senate for thorough investigations of industry transactions. With that said, the FTC cleared most industry transactions without challenge, despite the costs imposed through extensive investigations. Furthermore, the career FTC staff that has reviewed transactions in the industry for a number of years will likely remain in place, suggesting that changes in the substantive review of industry transactions are likely to be modest. Nonetheless, the potential for fewer Second Requests and quicker HSR approvals would be beneficial to an energy consolidation wave that industry experts suggest has not yet crested.
7. Impact on Energy Industry Capital Raising and Public Company Regulation
The reduction in environmental reporting and carbon monitoring under the Executive Order, in combination with the policy objectives stated in the Executive Order and other directives from the Trump administration, indicate that the outlook for energy capital markets and public company regulation under the second Trump administration is positive. Both going public and operating as a public company should be less time-consuming and costly than it was under the Biden administration. A majority of the U.S. Securities and Exchange Commission (SEC) commissioners (including the nominated chair, former Commissioner Atkins) will be appointed by President Trump and, judging from the first Trump administration, will set an agenda that is supportive of capital raising and focused on reducing the burden of being publicly traded. For example, the climate disclosure rules adopted by the Biden administration’s divided SEC (and stayed pending challenge in federal court) are likely to be repealed, saving energy companies a significant amount of G&A expense and reducing the risk of litigation. As another example, based on experience with the SEC review process under the first Trump administration, we expect the process and waiver requests to be faster and more commercial, further facilitating capital markets transactions. We also can expect rule proposals that are focused on making it easier for private companies to raise capital from a broader investor base. For capital intensive businesses in the energy industry, a relatively fast, predictable process with as little unnecessary expense as possible, is important. As such, we expect the backlog of private energy companies who have been waiting to IPO to seize the opportunity to access the capital markets while the process is easier, being a public company is less costly, and the broader business climate for the industry is supportive. In addition, we expect public energy companies to take advantage of this improved regulatory climate to access the capital markets more often than in recent years. Regardless, investor pressures to live within free cash flow, maintain low leverage and pay dividends to shareholders will continue to impact decision making with respect to equity and debt capital markets transactions.
Despite all this optimism, it remains true that capital markets for the energy industry are only as strong as the capital markets themselves. Other significant events, such as war, pandemic, inflation, labor shortages, or supply cost increases from tariffs, could have an adverse impact on the equity markets or the energy industry generally. Similarly, any increases in the deficit and inflation could cause interest rates to rise again, increasing the cost of accessing the debt capital markets. Even so, energy capital markets generally thrive on stability and low volatility and the regulatory environment under the second Trump administration appears to be conducive to this.
Gibson, Dunn & Crutcher’s lawyers are available to assist in addressing any questions you may have about these developments. To learn more, please contact the Gibson Dunn lawyer with whom you usually work, the authors, or any leader or member of the firm’s Oil & Gas, Energy Regulation & Litigation, Environmental Litigation & Mass Tort, Power & Renewables, Cleantech, Antitrust & Competition, Capital Markets, or Mergers & Acquisitions practice groups:
Oil and Gas:
Michael P. Darden – Houston (+1 346.718.6789, mpdarden@gibsondunn.com)
Rahul D. Vashi – Houston (+1 346.718.6659, rvashi@gibsondunn.com)
Graham Valenta – Houston (+1 346.718.6646, gvalenta@gibsondunn.com)
Energy Regulation and Litigation:
William R. Hollaway – Washington, D.C. (+1 202.955.8592, whollaway@gibsondunn.com)
Tory Lauterbach – Washington, D.C. (+1 202.955.8519, tlauterbach@gibsondunn.com)
Environmental Litigation and Mass Tort:
Stacie B. Fletcher – Washington, D.C. (+1 202.887.3627, sfletcher@gibsondunn.com)
David Fotouhi – Washington, D.C. (+1 202.955.8502, dfotouhi@gibsondunn.com)
Rachel Levick – Washington, D.C. (+1 202.887.3574, rlevick@gibsondunn.com)
Power and Renewables:
Peter J. Hanlon – New York (+1 212.351.2425, phanlon@gibsondunn.com)
Nicholas H. Politan, Jr. – New York (+1 212.351.2616, npolitan@gibsondunn.com)
Cleantech:
John T. Gaffney – New York (+1 212.351.2626, jgaffney@gibsondunn.com)
Daniel S. Alterbaum – New York (+1 212.351.4084, dalterbaum@gibsondunn.com)
Adam Whitehouse – Houston (+1 346.718.6696, awhitehouse@gibsondunn.com)
Antitrust and Competition:
Rachel S. Brass – San Francisco (+1 415.393.8293, rbrass@gibsondunn.com)
Kristen C. Limarzi – Washington, D.C. (+1 202.887.3518, klimarzi@gibsondunn.com)
Cynthia Richman – Washington, D.C. (+1 202.955.8234, crichman@gibsondunn.com)
Capital Markets:
Andrew L. Fabens – New York (+1 212.351.4034, afabens@gibsondunn.com)
Hillary H. Holmes – Houston (+1 346.718.6602, hholmes@gibsondunn.com)
Stewart L. McDowell – San Francisco (+1 415.393.8322, smcdowell@gibsondunn.com)
Peter W. Wardle – Los Angeles (+1 213.229.7242, pwardle@gibsondunn.com)
Mergers and Acquisitions:
Robert B. Little – Dallas (+1 214.698.3260, rlittle@gibsondunn.com)
Saee Muzumdar – New York (+1 212.351.3966, smuzumdar@gibsondunn.com)
George Sampas – New York (+1 212.351.6300, gsampas@gibsondunn.com)
© 2025 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
This update summarizes key amendments to the COPPA Rule and related FTC Commissioner statements, as well as key proposals that the FTC declined to adopt, and it positions these developments in the broader legal landscape related to children’s privacy and safety online.
On January 16, 2025, the Federal Trade Commission (FTC or Commission) voted 5-0 to approve long-awaited updates to the Children’s Online Privacy Protection Rule (COPPA Rule or Rule),[1] which was last updated over a decade ago, in 2013. The FTC had proposed amendments to the COPPA Rule in a Notice of Proposed Rulemaking (NPRM) in January 2024,[2] following a 2019 request for comment[3] on the effectiveness of the 2013 amendments. While the updated COPPA Rule does not include some of the more sweeping amendments proposed, it imposes significant new obligations regarding the collection, use, and disclosure of personal information from children under 13. Many of these updates effectively codify positions that the Commission has taken in COPPA enforcement actions under the prior COPPA Rule.
As described in detail below, key updates to the COPPA Rule include:
- Requiring separate parental consent for data sharing with third parties for targeted ads and other non-integral purposes. Requiring covered operators to obtain separate verifiable parental consent to disclose children’s personal information to third-party companies for targeted advertising or other purposes that are not “integral” to the operator’s websites or online services;
- Requiring data minimization and a data retention policy. Limiting the retention of children’s personal information to only the time reasonably necessary to fulfill the specific purpose for which it was collected, prohibiting the retention of children’s personal information indefinitely, and requiring adoption of a written data retention policy;
- Clarifying definitions of child-directed and mixed audience services. Clarifying which online services may be covered by the Rule by amending the definition of “website or online service directed to children” to include a non-exhaustive exemplary list of evidence the FTC may consider in analyzing audience composition and intended audience, and adding a new, standalone definition of “mixed audience website or online service”;
- Expanding the definition of covered information. Expanding the definition of “personal information” to include biometric identifiers and government-issued identifiers beyond Social Security numbers;
- Expanding parental notice requirements. Clarifying and expanding the scope of disclosures required in direct notices and online privacy notices, including: the identities and categories of any third parties with which the operator shares children’s personal information; how specifically the operator uses persistent identifiers to support its internal operations and what measures are in place to avoid using persistent identifiers for unauthorized purposes; and when an operator collects an audio file of a child’s voice pursuant to the audio file exception, a description of how the operator uses audio files and a disclosure that such files are deleted immediately after responding to the request for which they were collected;
- Enumerating additional methods to obtain verifiable parental consent. Enumerating additional methods that satisfy the requirement to obtain verifiable parental consent before collecting personal information from children or using or disclosing such information, including using a text message coupled with an additional step, such as a confirmatory text message following receipt of consent (the “text plus” method);
- Enhancing data security requirements. Clarifying the reasonable security measures required to protect personal information from children, which include, at a minimum, establishing a written data security program; and
- Increasing oversight and transparency of Safe Harbor programs. Enhancing oversight of, and transparency regarding, Safe Harbor programs, including by requiring that such programs disclose their membership lists and report additional information to the FTC.
Significant proposals the FTC dropped include changes that would have codified requirements for educational technology companies operating in a school environment, and those that would have prohibited the use of push notifications and similar engagement techniques without separate parental consent.
The amended COPPA Rule will become effective 60 days after its publication in the federal register, and covered operators will have until one year after the publication date to comply, except with respect to certain provisions regarding Safe Harbor programs.[4] We note, however, that businesses should continue to monitor updates regarding the publication of the updated Rule, given the possibility for delay or withdrawal under the Trump administration or the new FTC leadership.[5] Although the FTC’s vote approving the final Rule was unanimous, then-incoming Chair Andrew Ferguson issued a strongly worded concurring statement identifying three “serious problems” with the amendments that he ascribed to “the outgoing administration’s irresponsible rush to issue last-minute rules two months after the American people voted to evict them from office,” and calling for “[t]he Commission under President Trump [to] address these issues and fix the mess that the outgoing majority leaves in its wake.”[6]
Despite some uncertainties, companies that knowingly provide services to children under 13 or that have offerings that could be considered attractive to children should revisit their existing compliance strategies to mitigate the substantial risk of liability for non-compliance with the updated COPPA Rule, which include civil penalties up to $53,088 per violation for 2025.[7] Given historical and continued bipartisan consensus that the privacy and safety of children online is a priority in light of developing technologies,[8] we expect rigorous oversight and enforcement by the FTC, including under the new administration.
Gibson Dunn has extensive experience advising and defending multinational companies on COPPA and youth-related strategies, including regulatory investigations and engagement strategies, product counseling, and litigation matters. We stand ready to advise companies on compliance with the updated COPPA Rule, and on federal, state, and international youth privacy and safety laws more broadly.
A. COPPA Background
Congress enacted COPPA in 1998, and the FTC’s COPPA Rule implementing COPPA first went into effect in 2000 and was last amended in 2013.
Importantly, COPPA applies only to online services that are directed to children under 13 or that are collecting, using, or sharing personal information of a user with actual knowledge that a particular user is under 13. More specifically, COPPA applies to (1) “operators of commercial websites and online services” that are “directed to children under 13 that collect, use, or disclose personal information from children”; (2) “operators of general audience websites or online services with actual knowledge that they are collecting, using, or disclosing personal information from children under 13”; and (3) to websites or online services that have actual knowledge that they are collecting personal information directly from users of another website or online service directed to children.”[9] COPPA’s primary goal is to give parents control over their children’s personal information and how that information is collected and processed.[10]
The COPPA Rule imposes several requirements on covered operators of websites and online services, including requirements to provide clear direct notice to parents and to obtain verifiable parental consent before collecting personal information from children or using or disclosing such information.[11] The Rule also confers other rights on parents, including the right to request that covered operators delete their children’s personal information,[12] and it imposes several additional obligations on covered operators, including for example with respect to security measures[13] and data retention.[14]
B. Key Amendments to the COPPA Rule
The following sections detail key amendments to the COPPA Rule.
a. Companies Covered By the COPPA Rule
The amended COPPA Rule “clarifies” the definition of “website or online service directed to children” by adding to the non-exhaustive exemplary list of evidence the FTC may consider in analyzing audience composition and intended audience “consideration of marketing or promotional materials or plans, representations to consumers or to third parties, reviews by users or third parties, and the age of users on similar websites or services.”[15] The latter example may be particularly challenging for companies to address since it relies on extraneous information outside a service’s control (and for the same reason, would not appear to be probative of a company’s intent to direct its service to children).
The amended Rule also includes a new, standalone definition of “mixed audience website or online service,” which the FTC confirmed is not intended to expand the scope of child-directed websites and online services, and does not change which websites or online services are directed to children.[16] The 2013 COPPA amendments and the FTC’s subsequent COPPA FAQ guidance introduced the concept of “mixed audience” websites and online services as a subcategory within the definition of “website or online service directed to children,” but did not define this term.[17] Under the updated Rule, “mixed audience” websites and online services are defined as those directed to children but that do not target children as their primary audience, and that do not collect personal information from any visitor other than to assess whether a visitor is a child.[18] Unlike other child-directed websites and online services, mixed audience websites and online services are permitted to collect information from visitors in a neutral manner in order to determine whether a visitor is a child.[19] Once a mixed audience website or online service determines that a visitor is 13 or over, it may collect personal information from the visitor without obtaining verifiable parental consent. The mixed audience website or online service may not deny access to visitors who are under 13, but may require verifiable parental consent or offer an experience that does not collect their personal information.
b. Expanded Definition of “Personal Information”
As amended, “personal information” under COPPA now explicitly includes (1) biometric identifiers, defined as an “identifier that can be used for the automated or semi-automated recognition of an individual, such as fingerprints; handprints; retina patterns; iris patterns; genetic data, including a DNA sequence; voiceprints; gait patterns; facial templates; or faceprints”; and (2) government-issued identifiers beyond Social Security numbers, including state ID cards, birth certificates, and passport numbers.[20]
c. Direct Notice & Verifiable Parental Consent
Direct Notice. The amended COPPA Rule clarifies and expands what companies must include in their direct notice disclosures to parents prior to collecting from and using their children’s personal information. Specifically, companies should ensure their direct notice disclosures:
- Include information on “how the operator intends to use [a child’s personal] information;”[21]
- Disclose the identity or categories of third parties the company shares personal information with, the purposes for sharing with those third parties, and that a parent can consent to the collection of and use of the child’s information, without consenting to its disclosure;[22] and
- Are provided in every instance in which a company seeks parental consent.[23]
Online Privacy Notice. Companies must also post clear, prominent links to online notices of their information practices regarding children.[24] As with the direct notices, the COPPA Rule amendments expand what must be included in the online notices to include:
- The identities and categories of any third parties to which the operator discloses personal information and the purpose for such disclosure;[25]
- The specific internal operations for which the operator uses persistent identifiers, and the policies or practices the operator has in place to avoid using persistent identifiers for unauthorized purposes;[26]
- When an operator collects an audio file of a child’s voice pursuant to the audio file exception (discussed below), a description of how the operator uses the audio files, and that such files are deleted immediately after responding to the request for which they were collected;[27] and
- The operator’s data retention policies for personal information collected from children.[28]
Verifiable Parental Consent. The amendments enumerate additional methods that satisfy the requirement to obtain verifiable parental consent before collecting personal information from children or using or disclosing a child’s personal information,[29] including:
- Processing any transaction requiring a parent to use a credit card, debit card, or other online payment system, provided that the transaction “provides notification of each discrete transaction to the primary account holder”–not just those transactions which include a monetary fee, as previously required;[30]
- Using a knowledge-based authentication process (i.e., questions of sufficient number and difficulty that a child could not reasonably ascertain the answers);[31]
- Matching an image of a face to a verified photo identification, such as a driver’s license (with the image and photo ID being promptly deleted thereafter);[32] and
- Using a “text plus” method that may be used when an operator does not disclose personal information from children to a third party, where (similar to the “email plus” method already available) subject to certain disclosure and confirmation requirements, a company uses a text message to obtain consent.[33]
The amendments also modify and expand exceptions to the COPPA Rule’s verifiable parental consent requirement. Of particular note is an exception for when a company collects an audio file containing a child’s voice as a replacement for written words, and no other personal information, and uses the audio file only to respond to a child’s specific request such as to execute a search or implement a verbal instruction, and the file is deleted immediately thereafter.[34] This exception is meant to provide flexibility for companies who rely on voice-assist technology.[35] Such a practice must be disclosed in an online notice.[36]
d. Separate Consent for Information Disclosures to Third Parties for Targeted Advertising and Other Non-Integral Purposes
The amended COPPA Rule requires separate parental consent for the disclosure of a child’s personal information to a third party for targeted advertising or other uses, “unless such disclosure is integral to the website or online service” such as disclosures necessary to provide the product or service.[37] Covered operators also cannot condition access to their website or service on obtaining such consent.[38] This amendment, in particular, will have significant implications for online services that may be perceived to be attractive to children that leverage third-party advertising technologies in their services.
e. Data Retention and Deletion
The COPPA Rule includes directives regarding the retention and deletion of personal information from children, including that a covered operator may retain such information “for only as long as is reasonably necessary to fulfill the purpose(s) for which the information was collected.”[39] Notably, the amendments prohibit companies from retaining children’s personal information indefinitely.[40] As discussed below, there is disagreement within the Commission surrounding this requirement, including as to what “indefinitely” means in this context.
The amendments further instruct that companies must establish a written data retention policy that specifies the purposes for which a child’s information is collected, the business need for retaining the information, and the timeframe for deleting it.[41] These policies must now be provided in online notices, as described above.[42]
f. Confidentiality, Security, and Integrity of Personal Information
COPPA requires covered operators to “establish and maintain reasonable procedures to protect the confidentiality, security, and integrity of personal information collected from children,”[43] and the amendments clarify the steps covered operators can take to comply with this “reasonable procedures” standard.
At a minimum, a covered operator’s safeguards must be “appropriate to the sensitivity of the personal information collected from children and the operator’s size, complexity, and nature and scope of activities.”[44] To comply, an operator must, among other requirements, designate employees to manage the program, assess the program at least annually, and implement necessary safeguards based on those assessments.[45] Notably, these requirements generally mirror the requirements contained in Commission orders requiring the implementation of a comprehensive information security program.
Additionally, covered operators that disclose children’s personal information to third parties must “take reasonable steps to determine that such entities are capable of maintaining the confidentiality, security, and integrity of the information” and obtain written assurances from the third parties that they will do so.[46]
g. Safe Harbor Programs
Under the COPPA Rule, the Commission may approve Safe Harbor programs–i.e., self-regulatory guidelines submitted by industry groups which implement the same or greater protections for children as in COPPA. The FTC amended the COPPA Rule to “enhance oversight of, and transparency regarding” these Safe Harbor programs by requiring they conduct annual independent assessments of their members’ compliance, including the members’ data privacy and security practices, disclose their membership lists, and maintain and submit to the FTC records of complaints about, and disciplinary actions against, the program’s members.[47] Existing COPPA Safe Harbor programs must submit proposed modifications within 6 months of the publication of the amended COPPA Rule in the federal register.[48]
C. Key Proposed Changes Not Adopted in Amended COPPA Rule
The amended COPPA Rule does not include certain amendments that the FTC proposed in its January 2024 NPRM, which were the subject of nearly 300 public comments, and which would have imposed significant compliance obligations relating to push notifications or engagement techniques and on educational technology companies.
a. Push Notifications/Engagement Techniques
The COPPA Rule includes an exception to obtaining verifiable parental consent “[w]here the purpose of collecting a child’s and a parent’s online contact information is to respond directly more than once to the child’s specific request, and where such information is not used for any other purpose, disclosed, or combined with any other information collected from the child.”[49] The NPRM’s proposal sought to prohibit companies from using this exception to “encourage or prompt use of a website or online service,” in order to address children’s overuse of online services due to engagement-enhancing techniques such as push notifications, in-game notices, or website pop-ups.[50]
Though the FTC stated it remains “deeply concerned” about push notifications and other techniques designed to prolong a child’s time spent online, the Commission was persuaded by concerns regarding the inconsistency between the proposed language and the COPPA statute, as well as First Amendment concerns regarding the breadth of the restriction, and thus did not amend COPPA to include this proposal.[51]
b. Educational Technology Requirements
The FTC also excluded several requirements proposed in the NPRM that would have been applicable to educational technology (ed tech) companies. The NPRM proposed including new definitions of “school” and “school-authorized education purpose,” as well as new provisions governing the collection of information from children in schools, and codifying the FTC’s existing guidance that allows ed tech companies to obtain consent from schools, rather than parents, to collect personal information from students for educational purposes.[52] The FTC chose not to adopt these proposed amendments “[t]o avoid making amendments to the COPPA Rule that may conflict with potential amendments to [the Department of Education’s Family Education Rights and Privacy Act] regulations.”[53] However, the Commission specifically noted that they “will continue to enforce COPPA in the ed tech context consistent with its existing guidance.”[54]
c. Other Exclusions
The final COPPA Rule also excluded other proposed amendments, including one that would have modified the exception to the parental consent requirement when companies collect persistent identifiers (and no other personal information) to provide support for the internal operations of the website or online service, such as for contextual advertising or personalization.[55] The FTC also declined to expand the definition of personal information to include avatars generated from a child’s image. And the FTC declined to amend the Rule to require companies disclose specifically the types of personal information collected, as well as details on how that personal information in particular is used, agreeing with commenters that “that level of detail could be superfluous.”[56]
D. An Uncertain Future
While the Commission vote approving the final COPPA Rule was unanimous, the future of the Rule remains uncertain. Former-Chair Lina Khan and then-incoming Chair Andrew Ferguson issued separate concurring statements about the Rule, and Commissioners Alvaro Bedoya and Rebecca Slaughter issued a joint concurring statement.
Former-Chair Khan’s concurring statement emphasized that these updates were long-awaited, especially given the dramatic rise in children’s smartphone and social media use since the Rule was last amended.[57] She characterized the updates as “complementing” the FTC’s enforcement efforts, potentially “boost[ing]” enforcement efforts by state attorneys general,[58] and welcoming Congress’ efforts to legislate in this area.[59]
In his concurring statement, Commissioner Ferguson characterized the amendments as “the culmination of a bipartisan effort initiated when President Trump was last in office” and voted to issue the final Rule because the amendments “contain several measures improving data privacy and security protections for children”–but he identified “three major problems” with the amendments.[60] He argued against the requirement that all new third-party data sharing should require a separate consent from parents, and against the prohibition on indefinite retention of data.[61] He also advocated for an exception for collecting children’s information for the limited purpose of age verification.[62] He was blunt in his critique that “these issues are the result of the Biden-Harris FTC’s frantic rush to finalize rules on their way out the door” and foreshadowed an intent to revisit the amendments in stating that “[t]he Commission under President Trump should address these issues and fix the mess that the outgoing majority leaves in its wake.”[63]
In their joint concurring statement, Commissioners Bedoya and Slaughter disagreed with Commissioner Ferguson regarding the prohibition against indefinite data retention, arguing such a requirement is necessary for companies that take the position that it is “reasonably necessary” to keep personal information indefinitely.[64]
E. FTC Enforcement Risks
Notwithstanding disagreement among Commissioners on certain details of the COPPA Rule amendments, companies can expect the FTC to continue to vigorously scrutinize data practices involving children. The FTC historically has focused its enforcement efforts on potential harms to children online, even where business practices are not subject to COPPA, under Section 5 of the FTC Act (Section 5). The FTC has also enforced against companies for violations of both COPPA and Section 5, often resulting in steep monetary penalties.
For example, in 2022, the FTC secured an agreement with Epic Games, Inc. (the creator of the video game Fortnite) to pay a record-breaking $520 million to settle allegations that Epic violated both COPPA and Section 5.[65] More recently, on January 17, 2025, another video game developer agreed to pay $20 million and make various product and other changes to settle FTC allegations that its practices related to loot boxes violated COPPA and Section 5[66]–although notably, Commissioners Ferguson and Holyoak dissented on three of four counts brought under Section 5.[67]
Further, some in Congress continue to push for federal legislation, including the Children and Teens’ Online Privacy Protection Act (COPPA 2.0),[68] which would extend the application of COPPA to youth under 16, ban targeted advertising to minors, and place more responsibility on companies to ensure children’s online safety. Senator Markey, the author of the bill and an author of COPPA, noted in a statement applauding the updated COPPA Rule that “Congress must still pass [COPPA 2.0] to extend these protections to teenagers, block targeted advertising to kids and teens, and give young people an eraser button to delete their personal information.”[69]
F. Additional Youth Privacy and Safety Developments and Enforcement Risks
These federal changes reflect a broader trend toward enhancing privacy and safety protections for children. Various U.S. states and jurisdictions worldwide are also increasingly focused on children and youth, implementing laws and taking actions under existing laws against companies with a substantial youth user base.
a. State Youth Laws and Enforcement
State lawmakers have made clear that protecting children’s online privacy and safety is a top priority, including by amending omnibus state privacy laws to include youth-specific provisions, enacting broader “age-appropriate design” laws applicable to any online service “reasonably likely to be accessed by children,” and enacting social media-specific laws requiring enhanced protections and often parental consent to children under 18 who use social media services. Many of these laws have been challenged successfully on First Amendment and other grounds, but other laws are spawning aggressive enforcement.
Among these state laws are Texas’ Securing Children Online Through Parental Empowerment Act (SCOPE Act), the majority of which came into effect on September 1, 2024,[70] and the California Protecting Our Kids from Social Media Addiction Act, only parts of which are currently set to take effect on March 6, 2025.[71] The Texas SCOPE Act takes a restrictive approach to collection and use of children’s data, while the California law is the first aiming to protect children from social media “addiction.” Both laws are shaping the youth legal landscape, setting templates for other states to follow, but the California law is currently being challenged, and we anticipate continued constitutional challenges asserting that other such laws restrict expressive speech. Even so, regulators are not slowing down their efforts pending these challenges.
For example, in October 2024–just one month after the Texas SCOPE Act came into effect–the Texas Attorney General’s Office announced its first action under the law seeking up to $10,000 per violation.[72] The Texas Attorney General’s Office also recently announced the launch of investigations into over a dozen companies in connection with the SCOPE Act and Texas’ omnibus privacy law that includes youth-specific provisions.[73]
Enforcement authorities also have sought to hold companies liable for alleged online harms to children under general state consumer protection laws prohibiting unfair and deceptive practices, which are not subject to the same constitutional concerns. Additionally, parents and families of children, as well as school districts, have similarly leveraged general consumer protection and other laws to pursue claims against online companies relating to purported youth harms, resulting in extensive multidistrict and class action litigation in this area.
b. Global Focus on Youth Privacy and Safety
Global lawmakers and regulators are also focused on youth privacy and safety online. Omnibus privacy laws outside the U.S. do not accord special treatment to children’s data, but some contain some similar restrictions to COPPA, such as requiring parental consent to process children’s data (e.g., the European Union (EU)’s General Data Protection Regulation) or prohibiting online platforms from targeting ads to children under 18 (e.g., the EU’s Digital Services Act (DSA), a sweeping EU regulation). As in the U.S., there is a similar global trend towards more prescriptive and aggressive laws concerning youth online activity.
For example, under the DSA, in-scope platforms can be fined up to 6% of global annual turnover by the European Commission (EC), which is the primary enforcing authority, for failing to conduct required risk assessments considering the impact of new features and service on harm to minors, among other concerns. The EC has already requested information from, and in some instances launched investigations into several companies in connection with, the collection and use of minors’ data under the DSA.[74] Similarly in the UK, Ofcom has been appointed to enforce the UK Online Safety Act (OSA) and has published drafts for consultation and finalized versions of its mandatory Codes of Practice. In addition, in recent years, many EU privacy regulators have been focused on enforcing against companies whose services can be accessed by children, and the UK Information Commissioner’s Office steadily continues to enforce its Children Code, also known as its Age Appropriate Design Code, which it published in 2020. And in APAC, Australia recently took steps to ban youth under the age of 16 from creating social media accounts–although implementing regulations have yet to be published.[75]
These laws underscore the challenges global companies will face in restructuring their compliance plans within tight timeframes.
The privacy and safety of children online are top concerns for the FTC, other enforcement authorities, lawmakers, and families worldwide. To that end, companies that conduct business online should take care to assess their legal obligations and practical risks under the amended COPPA Rule, as well as under youth-related laws across jurisdictions, given increased regulatory attention to child-directed services and features under an expanding landscape of child-focused regulation.
Again, Gibson Dunn has extensive experience advising multinational companies operating online services on a wide variety of regulatory and law enforcement investigation, enforcement, strategic counseling, litigation, and appellate matters relating to child and teen privacy and safety. We are closely monitoring developments within the youth legal landscape, and we are available to discuss these issues as applied to your particular situation.
[1] Press Release, Fed. Trade Comm’n, FTC Finalizes Changes to Children’s Privacy Rule Limiting Companies’ Ability to Monetize Kids’ Data (Jan. 16, 2025), https://www.ftc.gov/news-events/news/press-releases/2025/01/ftc-finalizes-changes-childrens-privacy-rule-limiting-companies-ability-monetize-kids-data; see also Fed. Trade Comm’n, Children’s Online Privacy Protection Rule, Final Rule Amendments (Jan. 16, 2025), https://www.ftc.gov/system/files/ftc_gov/pdf/coppa_sbp_1.16_0.pdf.
[2] Children’s Online Privacy Protection Rule, 89 Fed. Reg. 2034 (proposed Jan.11, 2024) (to be codified at 16 C.F.R. pt. 312).
[3] Press Release, Fed. Trade Comm’n, FTC Seeks Comments on Children’s Online Privacy Protection Act Rule (July 25, 2019), https://www.ftc.gov/news-events/news/press-releases/2019/07/ftc-seeks-comments-childrens-online-privacy-protection-act-rule.
[4] Children’s Online Privacy Protection Rule, supra note 1, at 1.
[5] On January 20, 2025, President Trump issued an order imposing a regulatory freeze on all executive agencies. See White House, Regulatory Freeze Pending Review (Jan. 20, 2025), https://www.whitehouse.gov/presidential-actions/2025/01/regulatory-freeze-pending-review/. While the extent to which independent agencies like the FTC are subject to the order may be subject to litigation, the presidential memorandum signals skepticism regarding actions taken by such agencies in the final days of the Biden administration. The FTC may choose to take steps consistent with Section 2 of the memorandum, which would involve withdrawal of the final COPPA Rule for review by a Republican majority (which, if re-approved, would then be sent to the federal register for publication). Accordingly, the publication in the federal register and implementation of the COPPA Rule should be monitored, as it could be subject to other actions taken to delay or revoke it, such as through the Congressional Review Act. See 5 U.S.C. §§ 801 et seq.
[6] See Andrew N. Ferguson, Comm’r, Fed. Trade Comm’n, Concurring Statement of Commissioner Andrew N. Ferguson COPPA Rule Amendments Matter Number P195404 (Jan. 16, 2025), https://www.ftc.gov/system/files/ftc_gov/pdf/ferguson-coppa-concurrence-revised.pdf.
[7] See Adjustments to Civil Penalty Amounts, 90 Fed. Reg. 5580 (Jan. 17, 2025) (to be codified at 16 C.F.R. pt. 1). The FTC annually adjusts the civil penalty amount applicable to COPPA violations based on inflation, pursuant to the Federal Civil Penalties Inflation Adjustment Act Improvements Act of 2015. See Press Release, Fed. Trade Comm’n, FTC Publishes Inflation-Adjusted Civil Penalty Amounts for 2024 (Jan. 11, 2024), https://www.ftc.gov/news-events/news/press-releases/2024/01/ftc-publishes-inflation-adjusted-civil-penalty-amounts-2024?utm_source=govdelivery. Accordingly, civil penalty violation amounts will rise in future years.
[8] See, e.g., S.2073, Kids Online Safety and Privacy Act, 118th Cong. (as passed by Senate, July, 30, 2024).
[9] Fed. Trade Comm’n, Complying with COPPA: Frequently Asked Questions (Jan. 2024), https://www.ftc.gov/business-guidance/resources/complying-coppa-frequently-asked-questions.
[10] Id.
[11] 16 C.F.R. §§ 312.4 – 312.5. All citations to the COPPA Rule are to the COPPA Rule as amended, unless otherwise stated.
[12] Id. at § 312.6.
[13] Id. at § 312.8.
[14] Id. at § 312.10.
[15] Id. at § 312.2.
[16] Children’s Online Privacy Protection Rule, supra note 1, at 9-10.
[17] 16 C.F.R. § 312.2; Complying with COPPA: Frequently Asked Questions, supra note 10.
[18] Children’s Online Privacy Protection Rule, supra note 1, at 8.
[19] Id. at 9.
[20] 16 C.F.R.§ 312.2. Examples of biometric data include “fingerprints; handprints; retina patterns; iris patterns; genetic data, including a DNA sequence; voiceprints; gait patterns; facial templates; or faceprints.”
[21] Id. at § 312.4(c)(1)(iii).
[22] Id. at § 312.4(c)(1)(iv).
[23] Id. at §§ 312.4(a) – (c)(1).
[24] Id. at § 312.4(d).
[25] Id. at § 312.4(d)(2).
[26] Id. at § 312.4(d)(3).
[27] Id. at § 312.4(d)(4).
[28] Id. at § 312.4(d)(2).
[29] Id. at § 312.5(a)(1).
[30] Id. at § 312.5(b)(2)(ii).
[31] Id. at § 312.5(b)(2)(vi)
[32] Id. at § 312.5(b)(2)(vii).
[33] Id. at § 312.5(b)(2)(ix). See also id. at § 312.2 (modifying the definition of “online contact information” to include a “mobile telephone number” in order to “give [companies] another way to initiate the process of seeking parental consent quickly and effectively.” Children’s Online Privacy Protection Rule, supra note 1, at 16).
[34] 16 C.F.R. § 312.5(c)(9).
[35] See, e.g., 106. Fed. Trade Comm’n, Enforcement Policy Statement Regarding the Applicability of the COPPA Rule to the Collection and Use of Voice Recordings (Oct. 20, 2017), https://www.ftc.gov/system/files/documents/public_statements/1266473/coppa_policy_statement_audiorecordings.pdf.
[36] 16 C.F.R. § 312.5(c)(9).
[37] Id. at § 312.5(a)(2); Children’s Online Privacy Protection Rule, supra note 1, at 106.
[38] 16 C.F.R. § 312.5(a)(2).
[39] Id. at § 312.10.
[40] Id.
[41] Id.
[42] Id.
[43] Id. at § 312.8(a).
[44] Id. at § 312.8(b).
[45] Id. at § 312.8(b)(1)-(3).
[46] Id. at § 312.8(c).
[47] Children’s Online Privacy Protection Rule, supra note 1, at 159. See generally 16 C.F.R. § 312.11.
[48] 16 C.F.R. § 312.11(g).
[49] Id. at § 312.5(c)(4).
[50] Children’s Online Privacy Protection Rule, supra note 1, at 116.
[51] Id. at 118-19. The American Civil Liberties Union argued the proposal was inconsistent with the COPPA statute given the statute states regulations “shall” permit operators to respond “more than once directly to a specific request from a child” when parents are provided notice and an opportunity to opt out. Id. at 117-18.
[52] Id. at 3-4. See also Complying with COPPA: Frequently Asked Questions, supra note 10, Section N.
[53] Children’s Online Privacy Protection Rule, supra note 1, at 4.
[54] Id.
[55] Id. at 56-61.
[56] Id. at 88-89.
[57] Lina M. Khan, Chair, Fed. Trade Comm’n, Statement of Chair Lina M. Khan Regarding the Final Rule Amending the Children’s Online Privacy Protection Rule Commission File No. P195404 (Jan. 16, 2025), https://www.ftc.gov/system/files/ftc_gov/pdf/statement-of-chair-lina-m-khan-re-coppa-amendments-1-16-2025.pdf.
[58] Id. at 1.
[59] Id. at 4.
[60] Andrew N. Ferguson, Comm’r, Fed. Trade Comm’n, Concurring Statement of Commissioner Andrew N. Ferguson COPPA Rule Amendments Matter Number P195404 (Jan. 16, 2025), https://www.ftc.gov/system/files/ftc_gov/pdf/ferguson-coppa-concurrence-revised.pdf.
[61] Id. at 1-3.
[62] Id. at 3.
[63] Id.
[64] Alvaro M. Bedoya, Comm’r, Fed. Trade Comm’n, Statement of Commissioner Alvaro M. Bedoya Joined by Commissioner Rebecca Kelly Slaughter Notice of Final Rulemaking to Update the Children’s Online Privacy Protection Rule (COPPA Rule) (Jan. 16, 2025), https://www.ftc.gov/system/files/ftc_gov/pdf/bedoya-coppa-statement-2025-01-16.pdf.
[65] Press Release, Fed. Trade Comm’n, Fortnite Video Game Maker Epic Games to Pay More Than Half a Billion Dollars over FTC Allegations of Privacy Violations and Unwanted Charges (Dec. 19, 2022), https://www.ftc.gov/news-events/news/press-releases/2022/12/fortnite-video-game-maker-epic-games-pay-more-half-billion-dollars-over-ftc-allegations.
[66] Press Release, Fed. Trade Comm’n, Genshin Impact Game Developer Will be Banned from Selling Lootboxes to Teens Under 16 without Parental Consent, Pay a $20 Million Fine to Settle FTC Charges (Jan. 17, 2025), https://www.ftc.gov/news-events/news/press-releases/2025/01/genshin-impact-game-developer-will-be-banned-selling-lootboxes-teens-under-16-without-parental.
[67] Andrew N. Ferguson, Comm’r, Fed. Trade Comm’n, Statement of Commissioner Andrew N. Ferguson Concurring in Part and Dissenting in Part In the Matter of Cognosphere, LLC, (Jan. 17, 2025), https://www.ftc.gov/system/files/ftc_gov/pdf/ferguson-cognosphere-concurrence.pdf.
[68] In September 2024, the House Energy and Commerce Committee passed COPPA 2.0 by a voice vote. In July 2024, the U.S. Senate passed the Kids Online Safety and Privacy Act, which included COPPA 2.0, by a 91-3 vote. In July 2023, the Senate Commerce, Science, and Transportation Committee unanimously passed COPPA 2.0. See Press Release, Ed Markey, Sen. of Mass., Senator Markey Celebrates FTC’s Update to Children’s Online Privacy Rule, (Jan. 16, 2025), https://www.markey.senate.gov/news/press-releases/senator-markey-celebrates-ftcs-update-to-childrens-online-privacy-rule.
[69] Id.
[70] See Securing Children Online through Parental Empowerment (SCOPE) Act, H.B. 18, 88th Leg., R.S. (2023).
[71] See Protecting Our Kids from Social Media Addiction Act, S.B. 976, 88th Leg. (2024).
[72] See Press Release, Ken Paxton, Att’y Gen. of Tex., Attorney General Ken Paxton Sues TikTok for Sharing Minors’ Personal Data In Violation of Texas Parental Consent Law (Oct. 3, 2024), https://www.texasattorneygeneral.gov/news/releases/attorney-general-ken-paxton-sues-tiktok-sharing-minors-personal-data-violation-texas-parental.
[73] See Press Release, Ken Paxton, Att’y Gen. of Tex., Attorney General Ken Paxton Launches Investigations into Character.AI, Reddit, Instagram, Discord, and Other Companies over Children’s Privacy and Safety Practices as Texas Leads the Nation in Data Privacy Enforcement (Dec. 12, 2024), https://www.texasattorneygeneral.gov/news/releases/attorney-general-ken-paxton-launches-investigations-characterai-reddit-instagram-discord-and-other.
[74] See Press Release, Eur. Comm’n, Commission opens formal proceedings against Meta under the Digital Services Act related to the protection of minors on Facebook and Instagram (May 15, 2024), (IP/24/2664); see also Press Release, Eur. Comm’n, Commission opens formal proceedings against TikTok under the Digital Services Act (Feb. 18, 2024), (IP/24/926).
[75] Press Release, Austl. eSafety Comm’r, Social Media Age Restrictions (Dec. 20, 2024), https://www.esafety.gov.au/about-us/industry-regulation/social-media-age-restrictions.
Gibson Dunn lawyers are available to assist in addressing any questions you may have about these developments. Please contact the Gibson Dunn lawyer with whom you usually work, the authors, or any leader or member of the firm’s Privacy, Cybersecurity & Data Innovation practice group:
United States:
Ashlie Beringer – Co-Chair, Palo Alto (+1 650.849.5327, aberinger@gibsondunn.com)
Ryan T. Bergsieker – Denver (+1 303.298.5774, rbergsieker@gibsondunn.com)
Gustav W. Eyler – Washington, D.C. (+1 202.955.8610, geyler@gibsondunn.com)
Cassandra L. Gaedt-Sheckter – Palo Alto (+1 650.849.5203, cgaedt-sheckter@gibsondunn.com)
Svetlana S. Gans – Washington, D.C. (+1 202.955.8657, sgans@gibsondunn.com)
Lauren R. Goldman – New York (+1 212.351.2375, lgoldman@gibsondunn.com)
Stephenie Gosnell Handler – Washington, D.C. (+1 202.955.8510, shandler@gibsondunn.com)
Natalie J. Hausknecht – Denver (+1 303.298.5783, nhausknecht@gibsondunn.com)
Jane C. Horvath – Co-Chair, Washington, D.C. (+1 202.955.8505, jhorvath@gibsondunn.com)
Martie Kutscher Clark – Palo Alto (+1 650.849.5348, mkutscherclark@gibsondunn.com)
Kristin A. Linsley – San Francisco (+1 415.393.8395, klinsley@gibsondunn.com)
Timothy W. Loose – Los Angeles (+1 213.229.7746, tloose@gibsondunn.com)
Vivek Mohan – Palo Alto (+1 650.849.5345, vmohan@gibsondunn.com)
Rosemarie T. Ring – Co-Chair, San Francisco (+1 415.393.8247, rring@gibsondunn.com)
Ashley Rogers – Dallas (+1 214.698.3316, arogers@gibsondunn.com)
Sophie C. Rohnke – Dallas (+1 214.698.3344, srohnke@gibsondunn.com)
Eric D. Vandevelde – Los Angeles (+1 213.229.7186, evandevelde@gibsondunn.com)
Benjamin B. Wagner – Palo Alto (+1 650.849.5395, bwagner@gibsondunn.com)
Debra Wong Yang – Los Angeles (+1 213.229.7472, dwongyang@gibsondunn.com)
Europe:
Ahmed Baladi – Co-Chair, Paris (+33 (0) 1 56 43 13 00, abaladi@gibsondunn.com)
Kai Gesing – Munich (+49 89 189 33-180, kgesing@gibsondunn.com)
Joel Harrison – Co-Chair, London (+44 20 7071 4289, jharrison@gibsondunn.com)
Lore Leitner – London (+44 20 7071 4987, lleitner@gibsondunn.com)
Vera Lukic – Paris (+33 (0) 1 56 43 13 00, vlukic@gibsondunn.com)
Lars Petersen – Frankfurt/Riyadh (+49 69 247 411 525, lpetersen@gibsondunn.com)
Robert Spano – London/Paris (+44 20 7071 4000, rspano@gibsondunn.com)
Asia:
Connell O’Neill – Hong Kong (+852 2214 3812, coneill@gibsondunn.com)
Jai S. Pathak – Singapore (+65 6507 3683, jpathak@gibsondunn.com)
© 2025 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
Gibson Dunn’s Workplace DEI Task Force aims to help our clients develop creative, practical, and lawful approaches to accomplish their DEI objectives following the Supreme Court’s decision in SFFA v. Harvard. Prior issues of our DEI Task Force Update can be found in our DEI Resource Center. Should you have questions about developments in this space or about your own DEI programs, please do not hesitate to reach out to any member of our DEI Task Force or the authors of this Update (listed below).
Key Developments
On January 20, President Trump issued an executive order titled “Defending Women from Gender Ideology Extremism and Restoring Biological Truth to the Federal Government,” which defines “sex” as “an individual’s immutable biological classification as either male or female” and directs federal agencies to “enforce laws governing sex-based rights, protections, opportunities, and accommodations to protect men and women as biologically distinct sexes.” The order also directs federal agencies to ensure that funds awarded via federal grants do not promote “gender ideology,” a term it defines to include “the idea that there is a vast spectrum of genders that are disconnected from one’s sex” and that “replaces the biological category of sex with an ever-shifting concept of self-assessed gender identity.” More information on this executive order can be found in our January 21, 2025 client alert.
Also on January 20, President Trump issued an executive order titled “Ending Radical and Wasteful Government DEI Programs And Preferencing,” which directs the termination of all DEI programs, policies, and activities in the federal government, including for federal contractors and grantees, and directs the termination of “equity-related” grants or contracts. The order also directs agencies to create a list of all federal contractors who have provided DEI trainings to federal employees and federal grant recipients who received grants to “provide or advance DEI, DEIA, or ‘environmental justice’ programs, services, or activities since January 20, 2021.” More information on this executive order can be found in our January 21, 2025 client alert.
On January 21, President Trump issued an executive order titled “Ending Illegal Discrimination and Restoring Merit-Based Opportunity.” The order rescinds several executive actions issued by prior administrations, including Executive Order 11246, which imposed affirmative action obligations on federal contractors in addition to non-discrimination requirements. Federal contracts and grants must now include (1) a clause requiring the recipient to agree that compliance “with applicable Federal anti-discrimination laws” is a “material” term of the contract or grant, and (2) a certification that the contractor or grant recipient “does not operate any programs promoting DEI that violate any applicable Federal anti-discrimination laws.” The order also directs agency heads to submit to the White House within 120 days recommendations for enforcing federal civil-rights laws and encouraging the private sector to end “illegal discrimination and preferences, including DEI.” Agencies must identify “up to nine” large companies or non-profits for “potential civil compliance investigations.” More information on this executive order can be found in our January 22, 2025 client alert.
Also on January 21, President Trump issued an Executive Order titled “Keeping Americans Safe in Aviation.” The order directs the Secretary of Transportation and the Federal Aviation Administrator to “immediately return to non-discriminatory” and “merit-based hiring.” The order rescinds any previous DEI initiatives by the Federal Aviation Administration “in favor of hiring, promoting, and otherwise treating employees on the basis of individual capacity, competence, achievement, and dedication.” The Secretary of Transportation and the Federal Aviation Administrator are instructed to review “past performance and performance standards of all individuals in critical safety positions” and to replace individuals who fall below those standards.
On January 21, President Trump named Commissioner Andrea R. Lucas as Acting Chair of the EEOC. Lucas, previously an attorney at Gibson Dunn, has served as an EEOC Commissioner since 2020. She is the EEOC’s only current Republican appointee. Upon her appointment, Acting Chair Lucas stated, “Consistent with the President’s Executive Orders and priorities, my priorities will include rooting out unlawful DEI-motivated race and sex discrimination; protecting American workers from anti-American national origin discrimination; defending the biological and binary reality of sex and related rights, including women’s rights to single‑sex spaces at work; protecting workers from religious bias and harassment, including antisemitism; and remedying other areas of recent under-enforcement.” In the past three years, Lucas has initiated 38 commissioner charges, more than any other commissioner.
On January 23, Texas Attorney General Ken Paxton and nine other State Attorneys General issued a letter to financial institutions including BlackRock, Goldman Sachs, Morgan Stanley, JPMorgan Chase, Bank of America, and Citigroup, warning that their DEI and ESG commitments could lead to enforcement actions if found to violate legal, contractual, or fiduciary obligations. The Attorneys General stated they would extend to each financial institution “an opportunity to avoid a lengthy enforcement action” by responding to thirty-five questions related to the institutions’ DEI and ESG efforts. The Attorneys General expressed concern that the institutions “appear to have embraced race- and sex-based quotas and to have made business and investment decisions based not on maximizing shareholder and asset value, but in the furtherance of political agendas.”
On January 10, following a four-day bench trial, the U.S. District Court for the Northern District of Texas held that American Airlines violated ERISA by allowing its investment manager, BlackRock, to invest its employees’ 401(k) Plan in environmental, social, and governance (“ESG”) objectives, which the court defined to include companies’ efforts to “promot[e] racial and gender diversity, equity, and inclusion (‘DEI’) programs and hiring practices.” The court made detailed findings of fact about Blackrock’s ESG-related initiatives, American’s corporate ESG goals, and the relationship between the two companies—which the court described as “incestuous,” noting that Blackrock was one of American’s largest investors and had “financed approximately $400 million of American’s corporate debt at a time when American was experiencing financing difficulties.” The court concluded that, due to American’s non-pecuniary interest in ESG and its relationship with BlackRock, the company “failed to loyally investigate BlackRock’s ESG investment activities” and ensure its employees’ 401(k) Plan was invested in a manner that furthered their best financial interests. However, because the court concluded that American acted “according to prevailing industry practices,” it found no violation of the fiduciary duty of prudence occurred. The court requested further briefing on damages and remedies.
Media Coverage and Commentary:
Below is a selection of recent media coverage and commentary on these issues:
- The New York Times, “The Cheat Sheet on Trump’s First Week” (January 25): Sarah Kessler of The New York Times DealBook writes that “President Trump made it clear his attacks on diversity, equity and inclusion programs won’t be restricted to the federal government,” and that “[i]n general, legal experts consider policies that provide opportunities or benefits to a specific group based on race or gender to be vulnerable” to challenge by the new administration. “Executives are anxious to find out which agencies will conduct investigations and enforcement actions, and what they may do to make examples out of target companies,” said Jason Schwartz, the labor and employment co-chair at Gibson Dunn. According to Kessler, the biggest question in boardrooms is which companies will be the first targets. Schwartz said checking the list of “woke companies” on the website of America First Legal, a Trump-aligned group, might be “a good starting place for hints.”
- ABC News: ABC News anchor Linsey Davis interviews Gibson Dunn’s Jason Schwartz about the impact of President Trump’s executive orders.
- Bloomberg, “Companies Parse What Makes a DEI Program Illegal Under Trump” (January 23): Clara Hudson, Isabel Gottlieb, and Andrew Ramonas of Bloomberg write that President Trump’s recent executive order targeting DEI “will further galvanize corporate diversity rollbacks” and “accelerate shifts” in how companies address diversity, including by prompting “more businesses to shut down their diversity teams or fold them into other areas of their operations.” Bloomberg reports that these rollbacks had already started, stating that “[w]hile much of corporate America has steadfastly pursued diversity initiatives,” many businesses have altered or eliminated diversity initiatives following “mounting conservative attacks” and the Supreme Court’s SFFA They report that many companies had renamed or rebranded their programs, but that President Trump’s recent order “aims to blunt” that strategy by calling out any diversity program “whether specifically denominated ‘DEI’ or otherwise.” The authors quote Gibson Dunn’s Jason Schwartz, who recommends that companies consider whether they can broaden the eligibility requirements for their DEI initiatives while still meeting program objectives. Schwartz says that corporate “goals remain the same”—to attract “the best talent from the broadest, most robust diverse pipeline.”
- The Washington Post, “In first days, Trump deals ‘death blow’ to DEI and affirmative action” (January 23): Julian Mark, Taylor Telford, and Susan Svrluga of The Washington Post report on President Trump’s initial actions, which they describe as seeking to “eviscerate the surviving remnants of affirmative action” and put a “hard stop” to DEI initiatives in the federal government. They report on Trump’s actions in his first week in office, which include “order[ing] U.S.-run diversity offices to close and scores of their workers to [be] put on administrative leave,” and “suspend[ing] dozens of contracting programs aimed at minorities and women.” The article quotes the EEOC’s three Democratic members, who said that President Trump’s rescission of the 1965 executive order directing federal contractors to take “affirmative action” measures has removed “a source of protection” for “millions of Americans.” In reference to President Trump’s direction that the Attorney General and agency heads identify “nine potential civil compliance investigations” of large entities, including publicly traded corporations, large nonprofits, and universities with endowments over $1 billion, the article quotes Gibson Dunn’s Jason Schwartz, who describes the order as a direction to “find nine big whales and make examples of them.” The article also quotes Schwartz’s description of a provision in the order that may have been designed to create a basis for False Claims Act liability: “They are handing out sheriff’s badges to private citizens to sue about government contractor DEI programs,” Schwartz said. The article quotes Noah Feldman, a constitutional law professor at Harvard Law School, who says these actions indicate that President Trump is “testing the boundaries” of the Supreme Court’s affirmative action rulings and attempting to extend their reach from educational institutions into the private sector. According to Ricardo Mimbela, an ACLU spokesperson, the ACLU is “analyzing” the executive orders and assessing how to “protect people’s fundamental rights.”
- CBS News, “Group of Attorneys General Urge Walmart to Reconsider Ending DEI Initiatives” (January 14): CBS News’s Christian Olaniran reports on the January 9 letter to Walmart CEO Doug McMillon, sent by thirteen Democratic state attorneys general, expressing “concern regarding Walmart’s recent decision to step away from its commitments to diversity, equity, and inclusion.” The letter highlighted the company’s recent decisions to “phase out supplier diversity programs, close down the Center for Racial Equality, end training for staff, and remove the words ‘diversity’ and ‘DEI’ from company documents and employee titles.” The letter acknowledged that corporations have faced “anti-DEI pressure,” but argued that the “decision to jettison DEI initiatives is not required by law” and that companies with diverse leadership “overperform” compared to those without. Olaniran’s reporting also referenced recent changes in DEI policies at other companies, including McDonald’s and Meta.
- The Washington Post, “Target Becomes Latest Company to Roll Back DEI Programs” (January 24): Hannah Ziegler and Julian Mark of The Washington Post report on Target’s decision to scale back many of its DEI initiatives in the wake of “a tougher legal environment for those programs and new threats from the White House.” In a January 24 press release, the company stated that it intended to make several changes to its policies including, among other things, ending its three-year DEI goals, ceasing to participate in external diversity-focused surveys, ensuring its employee resource groups are open to all; and evolving its supplier diversity efforts. The company stated “[w]e remain focused on driving our business by creating a sense of belonging for our team, guests and communities through a commitment to inclusion.”
Case Updates:
Below is a list of updates in new and pending cases:
1. Contracting claims under Section 1981, the U.S. Constitution, and other statutes:
- Desai v. Paypal, No. 1:25-cv-00033-AT (S.D.N.Y. 2025): On January 2, 2025, Andav Capital and its founder Nisha Desai sued PayPal, alleging that PayPal unlawfully discriminates by administering its investment program for minority-owned businesses in a way that favors Black and Latino applicants. Desai, an Asian-American woman, alleges PayPal violated Section 1981, Title VI, and New York state anti-discrimination law by failing to fully consider her funding application and announcing first-round investments only in companies with “at least one general partner who was black or Latino.” She seeks a declaratory judgment that the investment program is unlawful, an injunction barring PayPal from “knowing or considering race or ethnicity” in administering the program, and damages.
- Latest update: The docket does not yet reflect that PayPal has been served.
- Do No Harm v. Pfizer, Inc., No. 23-15 (2nd Cir. 2022): On September 15, 2022, Do No Harm filed suit against Pfizer, alleging that Pfizer’s Breakthrough Fellowship Program unlawfully excludes white and Asian-American applicants on the basis of race in violation of federal and state laws. On December 16, 2022, the U.S. District Court for the Southern District of New York dismissed the case after finding Do No Harm lacked standing to seek a preliminary injunction when it “failed to identify a single injured member by name” who could demonstrate that they were willing and able to apply to the fellowship. On March 6, 2024, a panel of the Second Circuit upheld the dismissal. On March 20, 2024, Do No Harm filed a petition for rehearing.
- Latest update: On January 10, 2025, the Second Circuit reversed the dismissal of Do No Harm’s lawsuit, concluding “that the district court applied the wrong standard in dismissing” Do No Harm’s case for lack of standing because “[t]he burden for establishing standing at the dismissal stage is lower” than that for a preliminary injunction. The Second Circuit remanded the case to the district court to assess standing “applying the standard applicable at the pleading stage.”
- Hierholzer v. Guzman, No. 24-1187 (4th Cir. 2025): In January 2023, Marty Hierholzer alleged that the Small Business Administration (SBA) discriminated on the basis of race when it denied his application to SBA’s 8(a) program. Through the 8(a) program, the SBA provides financial assistance to small businesses owned by “socially and economically disadvantaged individuals.” SBA regulations provide a rebuttable presumption of social disadvantage to members of certain racial groups and an opportunity for members of other groups to establish social disadvantage and 8(a) eligibility. Hierholzer is of Scottish and German descent. The U.S. District Court for the Eastern District of Virginia held that Heirholzer’s claims were moot after a separate district court ruling out of Tennessee enjoined the SBA from using the rebuttable presumption standard. The court also found Hierholzer lacked standing because he did not allege 8(a) eligibility and did not sufficiently plead economic or social disadvantage. Heirholzer appealed to the Fourth Circuit.
- Latest update: On January 3, 2025, the Fourth Circuit held that the district court erred in treating Hierholzer’s claims as moot because the decision enjoining the SBA’s rebuttable presumption “has not resulted in a final judgment.” However, the Court found Hierholzer lacked standing because, even if the presumption were enjoined, Hierholzer failed to plausibly allege that he could satisfy other race neutral eligibility requirements for the program.
- Brooke Henderson, et al. v. Springfield R-12 School District, et al., No. 23-01374 (8th Cir. 2023): On August 18, 2021, two educators sued a Springfield, Missouri school district alleging that the district’s mandatory equity training violated their First Amendment rights. The educators claimed that the equity training constituted compelled speech, content and viewpoint discrimination, and an unconstitutional condition of employment. The at-issue Fall 2020 equity training included sessions on anti-bias, anti-racism, and white supremacy. On January 12, 2023, the district court granted the defendants’ motion for summary judgment. The plaintiffs appealed the decision to the U.S. Court of Appeals for the Eighth Circuit. Oral argument was held on February 15, 2024. Counsel for the plaintiffs argued that the training compelled educators to engage in political speech, while counsel for the defendants argued that the educators were not compelled because they did not face punishment. On September 13, 2024, a panel of the Eighth Circuit unanimously held that the plaintiffs’ fear of punishment was too speculative to constitute injury under the First Amendment and affirmed the decision below. On November 27, 2024, the Eighth Circuit granted a petition for rehearing en banc.
- Latestupdate: On January 15, 2025, oral argument was held before the court en banc. Counsel for the plaintiffs argued that the equity training was compelled speech in violation of the First Amendment because silence was not an option—the training required the plaintiffs to take a stand or to face consequences in the form of being labelled unprofessional. Counsel for the defendants argued the plaintiffs would not face punishment if they stayed silent; the point of the training was merely to encourage discussion.
- American Alliance for Equal Rights v. McDonald’s Corporation et al., No. 3:25-cv-00050 (M.D. Tenn. 2025): On January 12, 2025, the American Alliance for Equal Rights (AAER) filed a complaint against McDonald’s and International Scholarship & Tuition Services, Inc. (ISTS), alleging that they operate a college scholarship program that “discriminates against high-schoolers based on their ethnicity,” in violation of § 1981. AAER alleges that the HACER scholarship program, which ISTS administers on McDonald’s behalf, “is open only to Hispanics.” AAER claims that the program “flatly” bars non-Hispanic students from applying “based on their ethnic heritage” and is therefore unlawful. AAER seeks declaratory and injunctive relief barring consideration of race, ethnicity, ancestry, or nationality in consideration of scholarship applications, as well as a preliminary injunction to stop the program from closing the application window for current applicants on February 6, 2025. Gibson Dunn represents McDonald’s in this action.
- Latest update: McDonald’s deadline for responding to the motion for preliminary injunction is February 3, 2025.
2. Challenges to statutes, agency rules, and regulatory decisions:
- Do No Harm v. Gianforte, No. 6:24-cv-00024-BMM-KLD (D. Mont. 2024): On March 12, 2024, Do No Harm filed a complaint on behalf of “Member A,” a white female dermatologist in Montana, alleging that a Montana law requiring the governor to “take positive action to attain gender balance and proportional representation of minorities resident in Montana to the greatest extent possible” when making appointments to the twelve-member Medical Board violates the Equal Protection Clause. Do No Harm alleges that since ten seats are currently held by six women and four men, Montana law requires that the remaining two seats be filled by men, which would preclude Member A from holding the seat. On May 3, 2024, Governor Gianforte moved to dismiss the complaint for lack of subject matter jurisdiction, arguing that Do No Harm lacks standing because Member A has not applied for or been denied any position. Gianforte also argued that the plaintiff’s pre-enforcement challenge was not ripe because his administration does not interpret the statute as a quota. On May 24, 2024, Do No Harm filed an amended complaint, describing additional Members B, C, and D, who are each “qualified, ready, willing, and able to be appointed” to the board. On June 7, Gianforte moved to dismiss the amended complaint, arguing again that the pseudonymous members lacked standing and that the case still was not ripe because the statute imposed only reporting requirements regarding diversity, so it posed no threat to the new members.
- Latest update: On January 10, 2025, Magistrate Judge De Soto recommended that the case be dismissed for lack of subject matter jurisdiction. Magistrate Judge De Soto found Do No Harm lacked standing because it did not allege “facts demonstrating that at least one Member is both ‘able and ready’ to apply for a Board seat in the reasonably foreseeable future.” For the same reasons, the Magistrate Judge found the case unripe.
- Do No Harm v. Edwards, No. 5:24-cv-16-JE-MLH (W.D. La. 2024): On January 4, 2024, Do No Harm sued then-Governor Edwards of Louisiana over a 2018 law requiring a certain number of “minority appointee[s]” to be appointed to the State Board of Medical Examiners. Do No Harm brought the challenge under the Equal Protection Clause and requested a permanent injunction against the law. On February 28, 2024, Governor Edwards answered the complaint, denying all allegations including allegations related to Do No Harm’s standing. On December 20, 2024, Governor Jeff Landry—who replaced Governor Edwards—moved to dismiss for lack of subject matter jurisdiction. He contended that, because he signed a declaration indicating that he does not intend to enforce the challenged law, the plaintiff’s claims are moot. Governor Landry also argued that the suit is barred by sovereign immunity.
- Latest update: On January 10, 2025, Do No Harm filed an opposition to the motion to dismiss, asserting that Governor Landry’s declaration did not moot the case because the statute remains on the books and a “future governor will be bound to enforce the racially discriminatory aspects of [the law] regardless of Governor Landry’s declaration.”
- Simon et al. v. Kay Ivey, et al. 25-cv-00067 (N.D. Al. 2025): On January 14, 2025 three professors and three students within the University of Alabama system and the Alabama NAACP filed a complaint against Alabama Governor Kay Ivey and the University of Alabama Board of Trustees, alleging that Alabama Senate Bill 129, which bans DEI programs at state agencies, local boards of education, and public universities, violates the First and Fourteenth Amendments. The Alabama NAACP alleges that the law “censor[s] dissenting viewpoints” by limiting the teaching of and prohibiting the funding of student groups and school offices associated with “divisive concepts.” SB 129 covers several “divisive topics,” including that race, gender, or identity makes one “inherently superior or inferior,” that moral character is determined by race, color, religion, sex, ethnicity, or national origin, and “that fault, blame, or bias should be assigned to members of a race, color, religion, sex, ethnicity, or national origin, on the basis of race, color, religion, sex, ethnicity.” The plaintiffs allege that SB 129’s limitations constitute viewpoint discrimination in violation of the First Amendment, undercut their right to freedom of association, are void for vagueness, and violate the Equal Protection Clause by intentionally discriminating against Black people, “specifically Black students and Black educators, who are more likely to benefit from discussions on these topics.” Plaintiffs request that the law be declared unconstitutional and both preliminarily and permanently enjoined.
- Latest update: The docket does not yet reflect that the defendants have been served.
- National Association of Scholars v. Granholm, No. 25-cv-00077 (W.D. Tex. 2025): On January 16, 2025, the National Association of Scholars—a group of professors, faculty, and researchers at colleges and universities across the United States—sued the United States Department of Energy, alleging that the Department’s Office of Science unlawfully requires research grant applicants to show how they would “promote diversity, equity, and inclusion in research projects” through its Promoting Inclusive and Equitable Research plan. The Association alleges that requiring grant applicants to show how they would promote DEI in their projects violates applicants’ First Amendment rights by requiring them to express ideas with which they disagree, that the Department lacked statutory authority to adopt the plan, and that the plan violates the procedural requirements of the Administrative Procedure Act. The Association seeks declaratory and injunctive relief.
- Latest update: The docket does not yet reflect that the defendants have been served.
Legislation Updates:
- On January 23, Congressman Tom Tiffany (R-WI) introduced the Fairness, Anti-Discrimination and Individual Rights Act (H.R. 711), referred to as the “FAIR Act.” If enacted, the bill would prohibit intentional discrimination or preferential treatment on the basis of race, color, or national origin by the federal government or its agents with respect to “[any] Federal contract or subcontract[,] federal employment[,] or any other federally conducted program or activity.” In addition, the bill would prohibit the federal government from encouraging or requiring “preference” on the basis of race, color, or national origin. It defines “preference” to include any advantage such as “a quota, set-aside, numerical goal, timetable, or other numerical objective.” The bill’s prohibitions extend to state and private entities that receive federal aid, including educational institutions that receive federal funding. The bill also calls for an audit of all federal agencies and departments within six months of its enactment to ensure compliance, and it creates a private right of action for individuals who believe they were discriminated against.
Gibson Dunn’s lawyers are available to assist in addressing any questions you may have regarding these developments. Please contact the Gibson Dunn lawyer with whom you usually work, any member of the firm’s Labor and Employment practice group, or the following practice leaders and authors:
Jason C. Schwartz – Partner & Co-Chair, Labor & Employment Group
Washington, D.C. (+1 202-955-8242, jschwartz@gibsondunn.com)
Katherine V.A. Smith – Partner & Co-Chair, Labor & Employment Group
Los Angeles (+1 213-229-7107, ksmith@gibsondunn.com)
Mylan L. Denerstein – Partner & Co-Chair, Public Policy Group
New York (+1 212-351-3850, mdenerstein@gibsondunn.com)
Zakiyyah T. Salim-Williams – Partner & Chief Diversity Officer
Washington, D.C. (+1 202-955-8503, zswilliams@gibsondunn.com)
Molly T. Senger – Partner, Labor & Employment Group
Washington, D.C. (+1 202-955-8571, msenger@gibsondunn.com)
Blaine H. Evanson – Partner, Appellate & Constitutional Law Group
Orange County (+1 949-451-3805, bevanson@gibsondunn.com)
© 2025 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
From the Derivatives Practice Group: Happy New Year! In late 2024, ISDA released the first version of the Equity Derivatives Clause Library. Not surprisingly, the regulatory agencies were quiet over the holidays.
New Developments
- Customer Advisory: Avoiding Fraud May be Your Best Resolution. A new CFTC customer advisory suggests adding “spotting scams” to your list of New Year’s resolutions. The Office of Customer Education and Outreach’s Avoiding Fraud May be Your Best Resolution says that with scammers robbing billions of dollars from Americans through relationship investment scams, resolving to be careful about who you trust online, staying informed, and learning all you can about trading risks are admirable 2025 resolutions.
- CFTC Approves Final Rule on Margin Adequacy, Treatment of Separate Accounts of a Customer by Futures Commission Merchants. On December 20, 2024, the CFTC announced a final rule to implement requirements for futures commission merchants related to margin adequacy and the treatment of separate accounts of a customer. The rule finalizes the Commission’s proposal, published in the Federal Register in March, to codify the no-action position in CFTC staff letter 19-17 regarding separate account treatment.
- CFTC Approves Final Rule Regarding Safeguarding and Investment of Customer Funds. On December 17, the CFTC announced that it approved a final rule amending the CFTC’s regulations that govern how futures commission merchants and derivatives clearing organizations safeguard and invest customer funds held for the benefit of customers engaging in futures, foreign futures, and cleared swaps transactions. The amendments revise the list of permitted investments in CFTC Regulation 1.25 and make other related changes and specifications. The amendments also eliminate the CFTC requirement that an FCM deposit customer funds with depositories that provide the CFTC with read-only electronic access to such accounts. The compliance date for the revisions is 30 days after the final rule is published in the Federal Register, except for the revisions to the Segregation Investment Detail Reports (“SIDR”) specified in CFTC Regulations 1.32, 22.2(g)(5), and 30.7(l)(5), and the revisions to the customer risk disclosure statement required under CFTC Regulation 1.55. The compliance date for the revisions to the SIDR and the risk disclosure statement is March 31, 2025.
- CFTC Grants QC Clearing LLC DCO Registration. On December 17, 2024, the CFTC announced that it issued QC Clearing LLC an Order of Registration as a derivatives clearing organization under the Commodity Exchange Act. QC Clearing LLC permitted to clear, in its capacity as a DCO, fully collateralized positions in futures contracts, options on futures contracts, and swaps.
New Developments Outside the U.S.
- ESMA Launches Selection of the Consolidated Tape Provider for Bonds. On January 3, ESMA announced the launch of the first selection procedure for the Consolidated Tape Provider (“CTP”) for bonds. Entities interested to apply are encouraged to register and submit their requests to participate in the selection procedure by February 7, 2025.The CTP aims to enhance market transparency and efficiency by consolidating trade data from various trading venues into a single and continuous electronic stream. This consolidated view of market activity is intended to help market participants to access accurate and timely information and make better-informed decisions, leading to more efficient price discovery and trading. [NEW]
- ESMA Publishes Feedback Received to Proposed Review of Securitization Disclosure Templates. On December 20, ESMA published a Feedback Statement summarizing the responses it received to its Consultation Paper on the securitization disclosure templates under the Securitization Regulation (“SECR”). Overall, respondents acknowledge the need for further improvements to the securitization transparency regime but recommend postponing the template review due to concerns about its timeline in relation to a broader SECR review. [NEW]
- ESMA Consults on the Internal Control Framework for Some of its Supervised Entities. On December 19, ESMA launched a consultation on draft Guidelines related to the Internal Control Framework for some of its supervised entities. ESMA said that the proposed draft Guidelines build on the Internal Control Guidelines currently in place for Credit Rating Agencies and extend them to include also Benchmark Administrators, and Market Transparency Infrastructures (Trade Repositories, Data Reporting Services Providers and Securitization Repositories). The draft Guidelines outline ESMA’s expectations for the components and characteristics of an effective internal control system, intended to ensure: a strong framework, detailing the internal control environment and informational aspects, and effective internal control functions, including compliance, risk management, and internal audit. The draft Guidelines also explain how ESMA applies proportionality in its expectations regarding the internal controls for a supervised entity. According to ESMA, the consultation is primarily aimed at ESMA supervised entities and prospective applicants for ESMA supervision.
- ESMA Releases Last Policy Documents to Get Ready for MiCA. On December 17, ESMA published its last package of final reports containing Regulatory Technical Standards and guidelines ahead of the full entry into application of the Markets in Crypto Assets Regulation. Specifically, the package includes Regulatory Technical Standards on market abuse and guidelines on reverse solicitation, suitability, crypto-asset transfer services, qualification of crypto-assets as financial instruments and maintenance of systems and security access protocols.
New Industry-Led Developments
- ISDA Publishes Equity Definitions Clause Library. On December 20, ISDA announced it has published version 1 of the ISDA Equity Derivatives Clause Library. The ISDA Equity Derivatives Clause Library provides drafting options with respect of certain clauses that parties can choose to include in an equity derivatives transaction that incorporates the 2002 ISDA Equity Derivatives Definitions. [NEW]
The following Gibson Dunn attorneys assisted in preparing this update: Jeffrey Steiner, Adam Lapidus, Marc Aaron Takagaki, Hayden McGovern, and Karin Thrasher.
Gibson Dunn’s lawyers are available to assist in addressing any questions you may have regarding these developments. Please contact the Gibson Dunn lawyer with whom you usually work, any member of the firm’s Derivatives practice group, or the following practice leaders and authors:
Jeffrey L. Steiner, Washington, D.C. (202.887.3632, jsteiner@gibsondunn.com)
Michael D. Bopp, Washington, D.C. (202.955.8256, mbopp@gibsondunn.com)
Michelle M. Kirschner, London (+44 (0)20 7071.4212, mkirschner@gibsondunn.com)
Darius Mehraban, New York (212.351.2428, dmehraban@gibsondunn.com)
Jason J. Cabral, New York (212.351.6267, jcabral@gibsondunn.com)
Adam Lapidus – New York (212.351.3869, alapidus@gibsondunn.com )
Stephanie L. Brooker, Washington, D.C. (202.887.3502, sbrooker@gibsondunn.com)
William R. Hallatt , Hong Kong (+852 2214 3836, whallatt@gibsondunn.com )
David P. Burns, Washington, D.C. (202.887.3786, dburns@gibsondunn.com)
Marc Aaron Takagaki , New York (212.351.4028, mtakagaki@gibsondunn.com )
Hayden K. McGovern, Dallas (214.698.3142, hmcgovern@gibsondunn.com)
Karin Thrasher, Washington, D.C. (202.887.3712, kthrasher@gibsondunn.com)
© 2025 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit our website.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
Trade association CTIA has successfully challenged the Federal Communications Commission’s “net neutrality” rule on behalf of the wireless-communications industry.
The U.S. Court of Appeals for the Sixth Circuit set aside the order in full, agreeing with arguments pressed by CTIA and a broader industry coalition that the FCC lacks statutory authority to impose heavy-handed common-carrier regulations on broadband Internet access service.
In the Communications Act of 1934, as amended, Congress enacted a light-touch regulatory regime for “information services” under Title I, and a much more expansive common-carrier-type regulatory regime for “telecommunications services” under Title II. Similarly, for mobile services, Congress subjected “private mobile services” only to light-touch regulation, while imposing common-carrier-type regulations on “commercial mobile services.” For many years, the FCC correctly treated broadband generally, and mobile broadband in particular, as an “information service” and “private mobile service” subject only to light-touch regulation. The FCC briefly departed from that approach in 2015, but quickly restored its original position in 2018; the D.C. Circuit deferred to the FCC’s position both times under the doctrine of Chevron deference, without resolving which approach reflected the better reading of the statute.
In May 2024, the FCC adopted a new order purporting to resurrect its 2015 approach by classifying broadband as a “telecommunications service” and mobile broadband as a “commercial mobile service”—thereby subjecting both fixed and mobile broadband to heavy-handed, innovation-stifling regulation designed for common carriers. CTIA and other industry groups challenged the order as unlawful, arguing (among other things) that the FCC’s new classification violated the plain text of the Communications Act, and that the Supreme Court’s decision overruling Chevron meant that the court could not defer to the FCC.
On January 2, 2025, a unanimous panel of the Sixth Circuit set aside the FCC’s order in full, agreeing with arguments pressed by CTIA and other industry groups. Looking to the plain language of the statute, the court held that broadband providers “offer only an ‘information service’ under 47 U.S.C. § 153(24), and therefore, the FCC lacks the statutory authority to impose its desired net-neutrality policies through the ‘telecommunications service’ provision of the Communications Act, id. § 153(51).” The court held that broadband satisfies the statutory definition of an “information service” because it allows users to retrieve and otherwise utilize information via telecommunications, and rejected the FCC’s counterarguments. The court went on to hold that the FCC’s reclassification of mobile broadband as a common-carrier “commercial mobile service” was likewise unlawful under the plain language of the statute, which requires a commercial mobile service to be “interconnected with the public switched network,” i.e., the 10-digit telephone network. Because mobile Internet service is not a service interconnected with the phone network, the court agreed with CTIA that mobile broadband “may not be regulated as a common carrier.”
The Sixth Circuit’s ruling is a significant victory for broadband providers generally and for the wireless-communications industry specifically, and it represents one of the first examples of a court applying the Supreme Court’s Loper Bright decision to reject an agency’s interpretation of a statute and foreclose future reliance on that interpretation. As the court explained, its interpretation of the plain text of federal law brings an end to “the FCC’s vacillations” over the appropriate classification of broadband. It thus brings greater stability to the industry and locks in place Title I’s light-touch regulatory framework, which fosters a dynamic broadband ecosystem, drives investment and innovation in next-generation networks, and promotes vibrant competition. The decision, CTIA – The Wireless Ass’n v. FCC, No. 24-3508 (6th Cir.), is available here.
Gibson Dunn’s lawyers are available to assist with any questions you may have regarding the decision and its impact on the wireless-communications industry. Please contact the Gibson Dunn lawyer with whom you usually work in the firm’s Administrative Law and Regulatory practice group, or the following practice leaders and members:
Eugene Scalia – Washington, D.C. (+1 202.955.8210, escalia@gibsondunn.com)
Helgi C. Walker – Washington, D.C. (+1 202.887.3599, hwalker@gibsondunn.com)
Stuart F. Delery – Washington, D.C. (+1 202.955.8515, sdelery@gibsondunn.com)
Russell Balikian – Washington, D.C. (+1 202.955.8535, rbalikian@gibsondunn.com)
Jonathan C. Bond – Washington, D.C. (+1 202-887-3704, jbond@gibsondunn.com)
© 2025 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit our website.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
A Survey of Disclosures from the S&P 100 During the Four Years Following Adoption of the Securities and Exchange Commission Rule.
Human capital resource disclosures by public companies have continued to be a focus since the U.S. Securities and Exchange Commission (the “Commission”) adopted the new rules in 2020, not only for companies making the disclosures, but employees, investors, and other stakeholders reading them. This alert updates the alert we issued in November 2023, “Form 10-K Human Capital Disclosures Continue to Evolve,” available here, and reviews disclosure trends among S&P 100 companies categorized into 28 topic areas. Each of these companies has now included human capital disclosure in their past four annual reports on Form 10-K. This alert also provides practical considerations for companies as we head into 2025.
Overall, our findings indicate that companies are generally making only minor changes to their disclosures year over year, and these minor changes generally included shortening of company disclosures, maintaining or decreasing the number of topics covered, and including slightly less quantitative information in some areas.[1] Specifically, we identified the following trends regarding the S&P 100 companies’ human capital disclosures compared to the previous year:
- Length of disclosure. Fifty-seven percent of surveyed companies decreased the length of their disclosures, 34% increased the length of their disclosures, and the length of the remaining 9% remained the same.
- Number of topics covered. Forty-one percent of surveyed companies decreased the number of topics covered, 13% increased the number of topics covered, and the remaining 46% covered the same number of topics.
- Breadth of topics covered. Across all companies, the prevalence of 10 topics increased, nine topics decreased, and nine topics remained the same.
- The most significant year-over-year increases in frequency involved Culture Initiatives (30% to 35%) and Pay Equity (48% to 50%) disclosures.
- The most significant year-over-year decrease involved COVID-19 disclosures, which declined in frequency from 34% to 1%. Other year-over-year decreases related to disclosures addressing Diversity Targets and Goals (21% to 14%), Diversity in Promotion (29% to 26%), Quantitative Diversity Statistics regarding Gender (63% to 60%), and Community Investment (28% to 25%).
- Most common topics covered. This year, the topics most commonly discussed generally remained consistent with the previous two years. For example, Talent Development, Diversity and Inclusion, Talent Attraction and Retention, Employee Compensation and Benefits, and Monitoring Culture remained the five most frequently discussed topics. The topics least discussed this most recent year, however, changed slightly from that of the previous year as COVID-19 disclosures, and Diversity Targets and Goals dropped into the five least frequently covered topics.
- Industry trends. Within the technology and finance industries, the trends that we saw in the previous year regarding the frequency of topics disclosed generally remained the same.
I. Background on the Requirements
As we previously discussed in our client alert titled “Discussing Human Capital: A Survey of the S&P 500’s Compliance with the New SEC Disclosure Requirement One Year After Adoption,” available here, on August 26, 2020, the Commission voted three-to-two to approve amendments to Items 101, 103, and 105 of Regulation S-K, including the principles-based requirement to discuss a registrant’s human capital resources to the extent material to an understanding of the registrant’s business taken as a whole.[2] Specifically, public companies’ human capital disclosure must include “the number of persons employed by the registrant, and any human capital measures or objectives that the registrant focuses on in managing the business (such as, depending on the nature of the registrant’s business and workforce, measures or objectives that address the development, attraction, and retention of personnel).”
Notably, since 2021 the Commission’s agenda list has included new human capital disclosure rules that were expected to be more prescriptive than the current rules,[3] in part, because one of the main criticisms of the existing human capital rules is lack of comparability across companies. The future of these rules is even less clear now as Chair Gensler who pushed for these rules (along with other rules, such as climate change) announced that he will be leaving the SEC in January 2025 in light of the new incoming administration. In the meantime, as our survey demonstrates, while company human capital disclosures vary—which is expected under the principles-based regime—comparability across the disclosures exists. The next four sections show the relevant data from our survey.[4]
II. Disclosure Topics
Our survey classifies human capital disclosures into 28 topics, each of which is listed in the following chart, along with the number of companies that discussed the topic in each of 2021, 2022, 2023, and 2024. Each topic is described more fully in the sections following the chart.
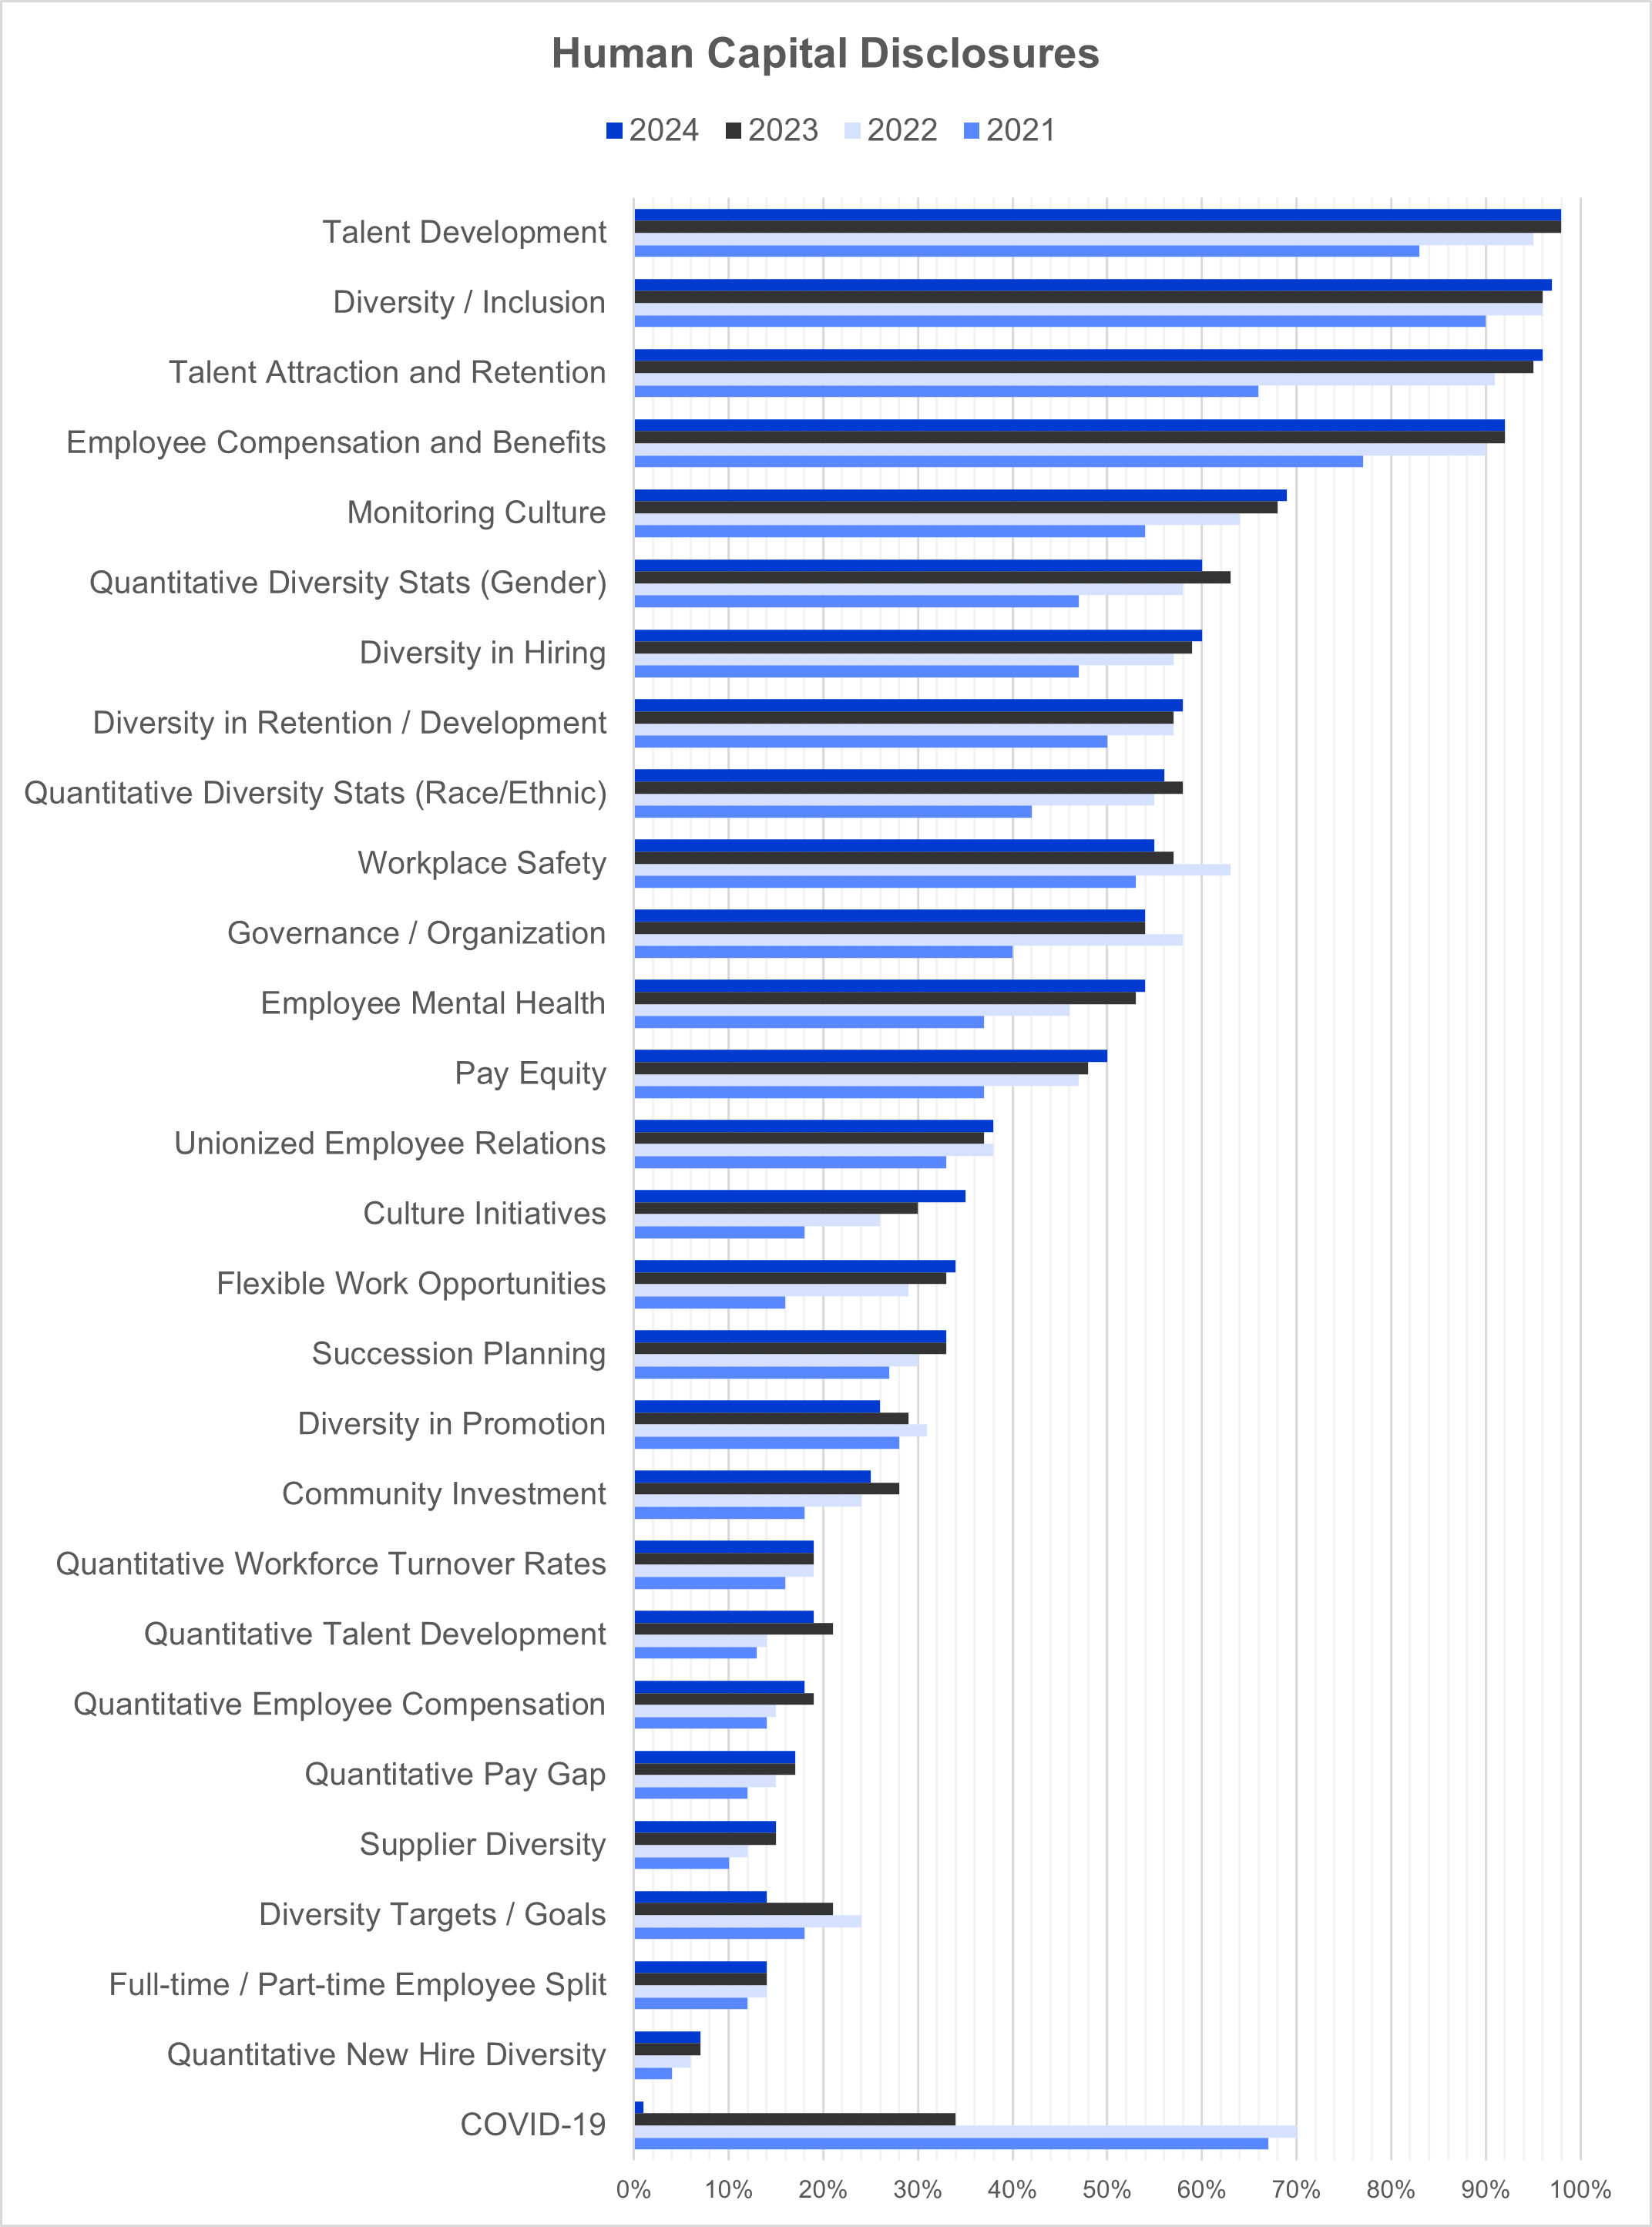 |
A. Workforce Composition
Among S&P 100 companies, 58% included disclosures relating to workforce composition in one or more of the following categories:
- Full-time/part-time employee split. While most companies provided the total number of full-time employees, only 14% of the companies surveyed included a quantitative breakdown of the number of full-time versus part-time employees or salaried versus hourly employees, consistent with the previous two years. Similarly, 66% of companies provided statistics on the number of seasonal employees and/or independent contractors or a breakdown of employees by business segment, job function, or geographical location, the same as the previous year, and up from and 60% in 2021.
- Unionized employee relations. Of the companies surveyed, 38% stated that some portion of their workforce was part of a union, works council, or similar collective bargaining agreement.[5] These disclosures generally included a statement providing the company’s opinion on the quality of labor relations, and in many cases, disclosed the number of unionized employees.
- Quantitative workforce turnover rates. Although a majority of companies discussed employee turnover and the related topics of talent attraction and retention in a qualitative way (as discussed in Section II.B. below), only 19% of companies surveyed provided specific employee turnover rates (whether voluntary or involuntary), consistent with the previous two years.
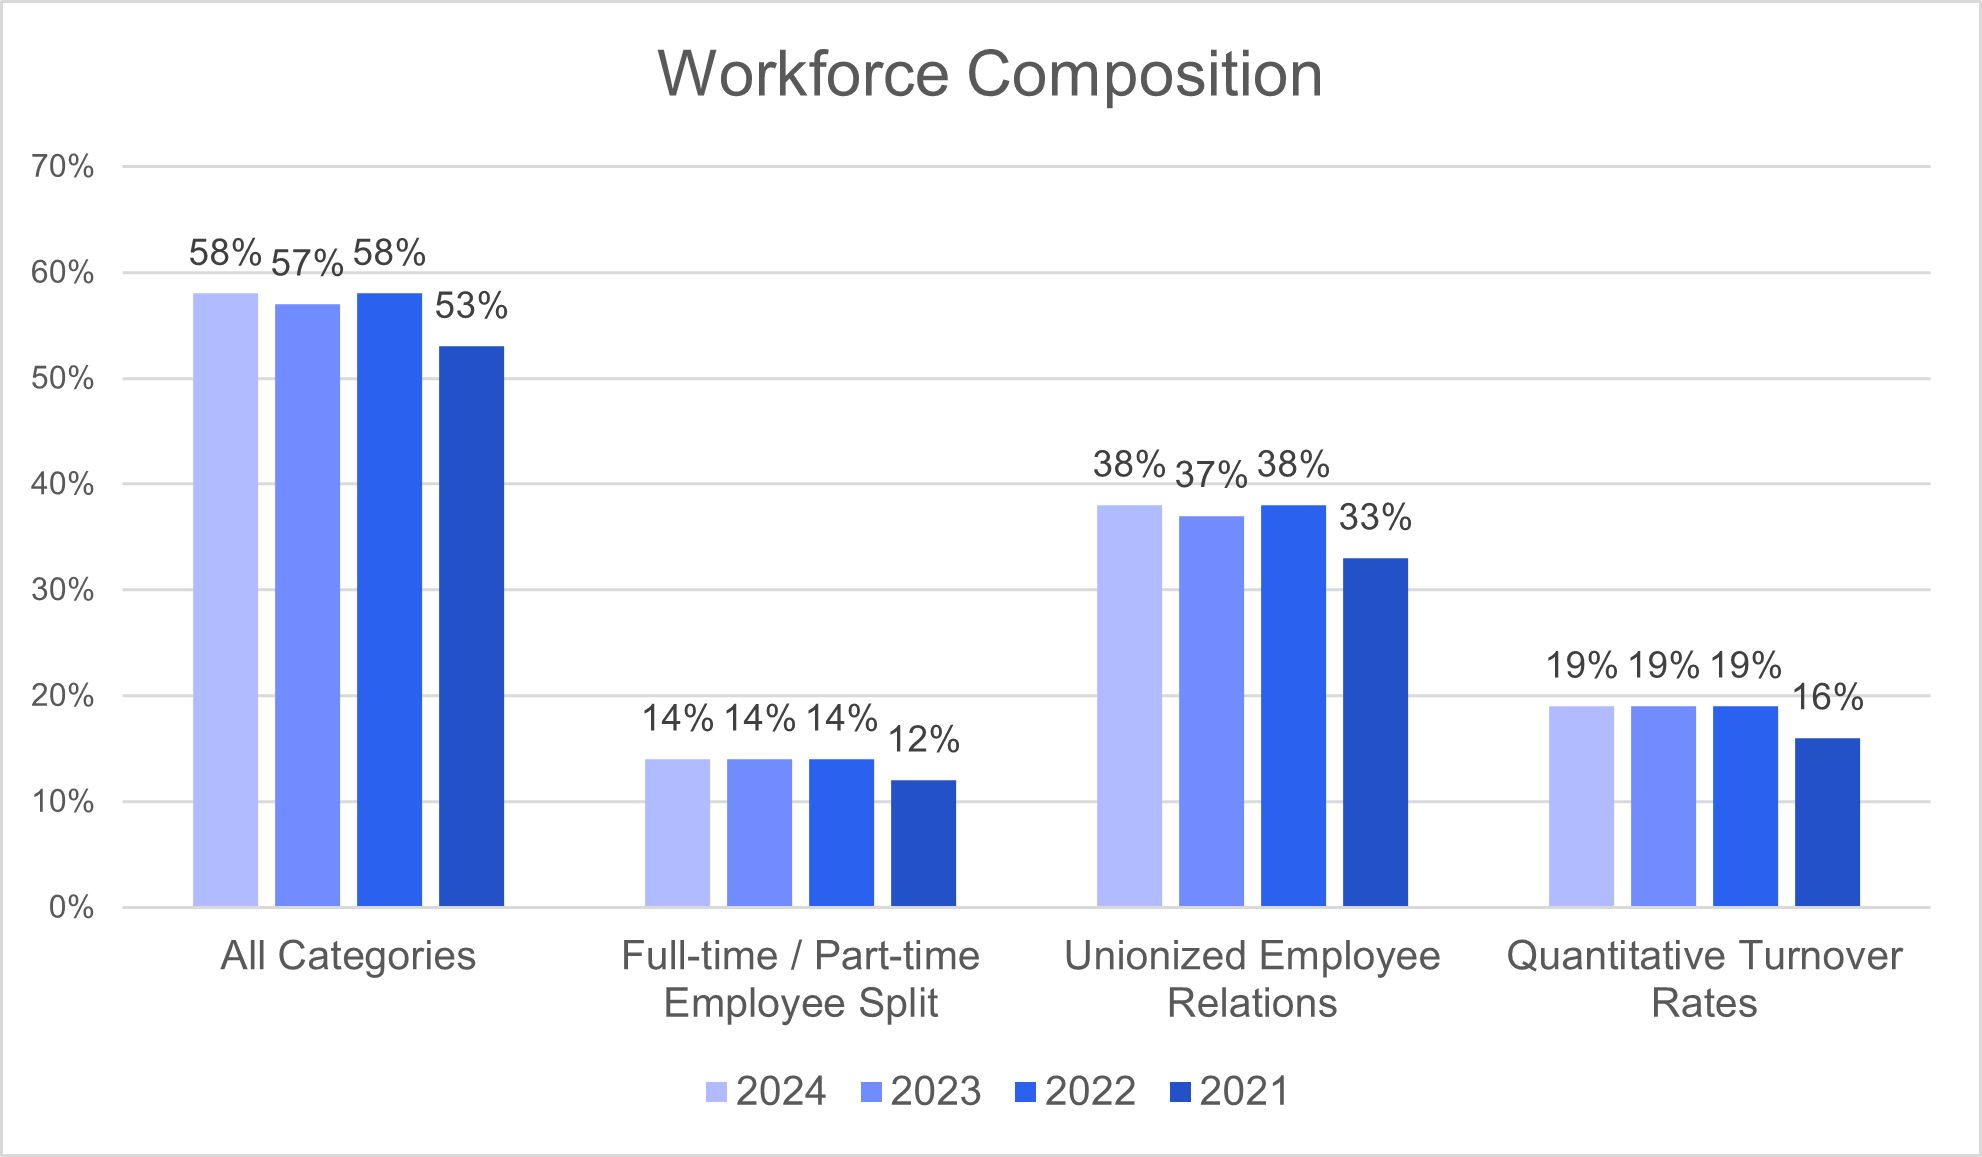 |
B. Diversity
Among S&P 100 companies, 97% included disclosures relating to diversity in one or more of the following categories:
- Diversity and inclusion. This was the most common diversity-related disclosure topic, with 97% of companies including a qualitative discussion regarding the company’s commitment to diversity, equity, and inclusion (“DEI”), consistent with the previous two years and up slightly from 91% in 2021. The depth of these disclosures varied, ranging from generic statements expressing the company’s support of diversity in the workforce to detailed examples of actions taken to recruit and support underrepresented groups and increase the diversity of the company’s workforce.
- Priorities within diversity. Companies disclosed different areas of focus for diversity efforts and programming within the organization. The most common disclosure was diversity in the company’s hiring practices (60% of companies in 2024, up dramatically from 47% in 2021), followed by diversity in the retention or development of the company’s current workforce (58% of companies in 2024, up slightly from 50% in 2021), diversity in the company’s promotion practices (26% of companies in 2024, down from a high of 31% in 2022), and finally diversity in the company’s suppliers (15% of companies in 2024, up slightly from 10% in 2021). A decreasing minority of companies also discussed, in qualitative or quantitative terms, the companies’ commitments to aspirational diversity goals or targets (14% of companies in 2024, down from a high of 24% of companies in 2022), with such decrease likely due to the heightened legal risk associated with DEI programs following the June 2023 United States Supreme Court decision in Students for Fair Admissions v. Harvard.
- Quantitative diversity statistics. Many companies also included a quantitative breakdown of the gender or racial representation of the company’s workforce: 60% included statistics on gender and 56% included statistics on race or ethnicity (down slightly compared to 2023, but up significantly from 47% and 42%, respectively, in 2021). Companies generally provided gender statistics on both a global and U.S. basis, whereas nearly all companies provided race or ethnicity statistics for their U.S. workforce only. Most companies provided these statistics in relation to their workforce generally, regardless of position; however, an increased subset (40% in 2024, compared to 25% in 2021) included separate statistics for different classes of employees (e.g., managerial, vice president and above, etc.). Similarly, 12% of companies also provided separate statistics for their boards of directors (compared to 10% in each of 2023 and 2022 and 4% in 2021). Some companies also included numerical goals for gender or racial representation, either in terms of overall representation, promotions, or hiring—11% of companies included these diversity goals or targets (compared to 15% in 2023, 18% in 2022, and 14% in 2021).
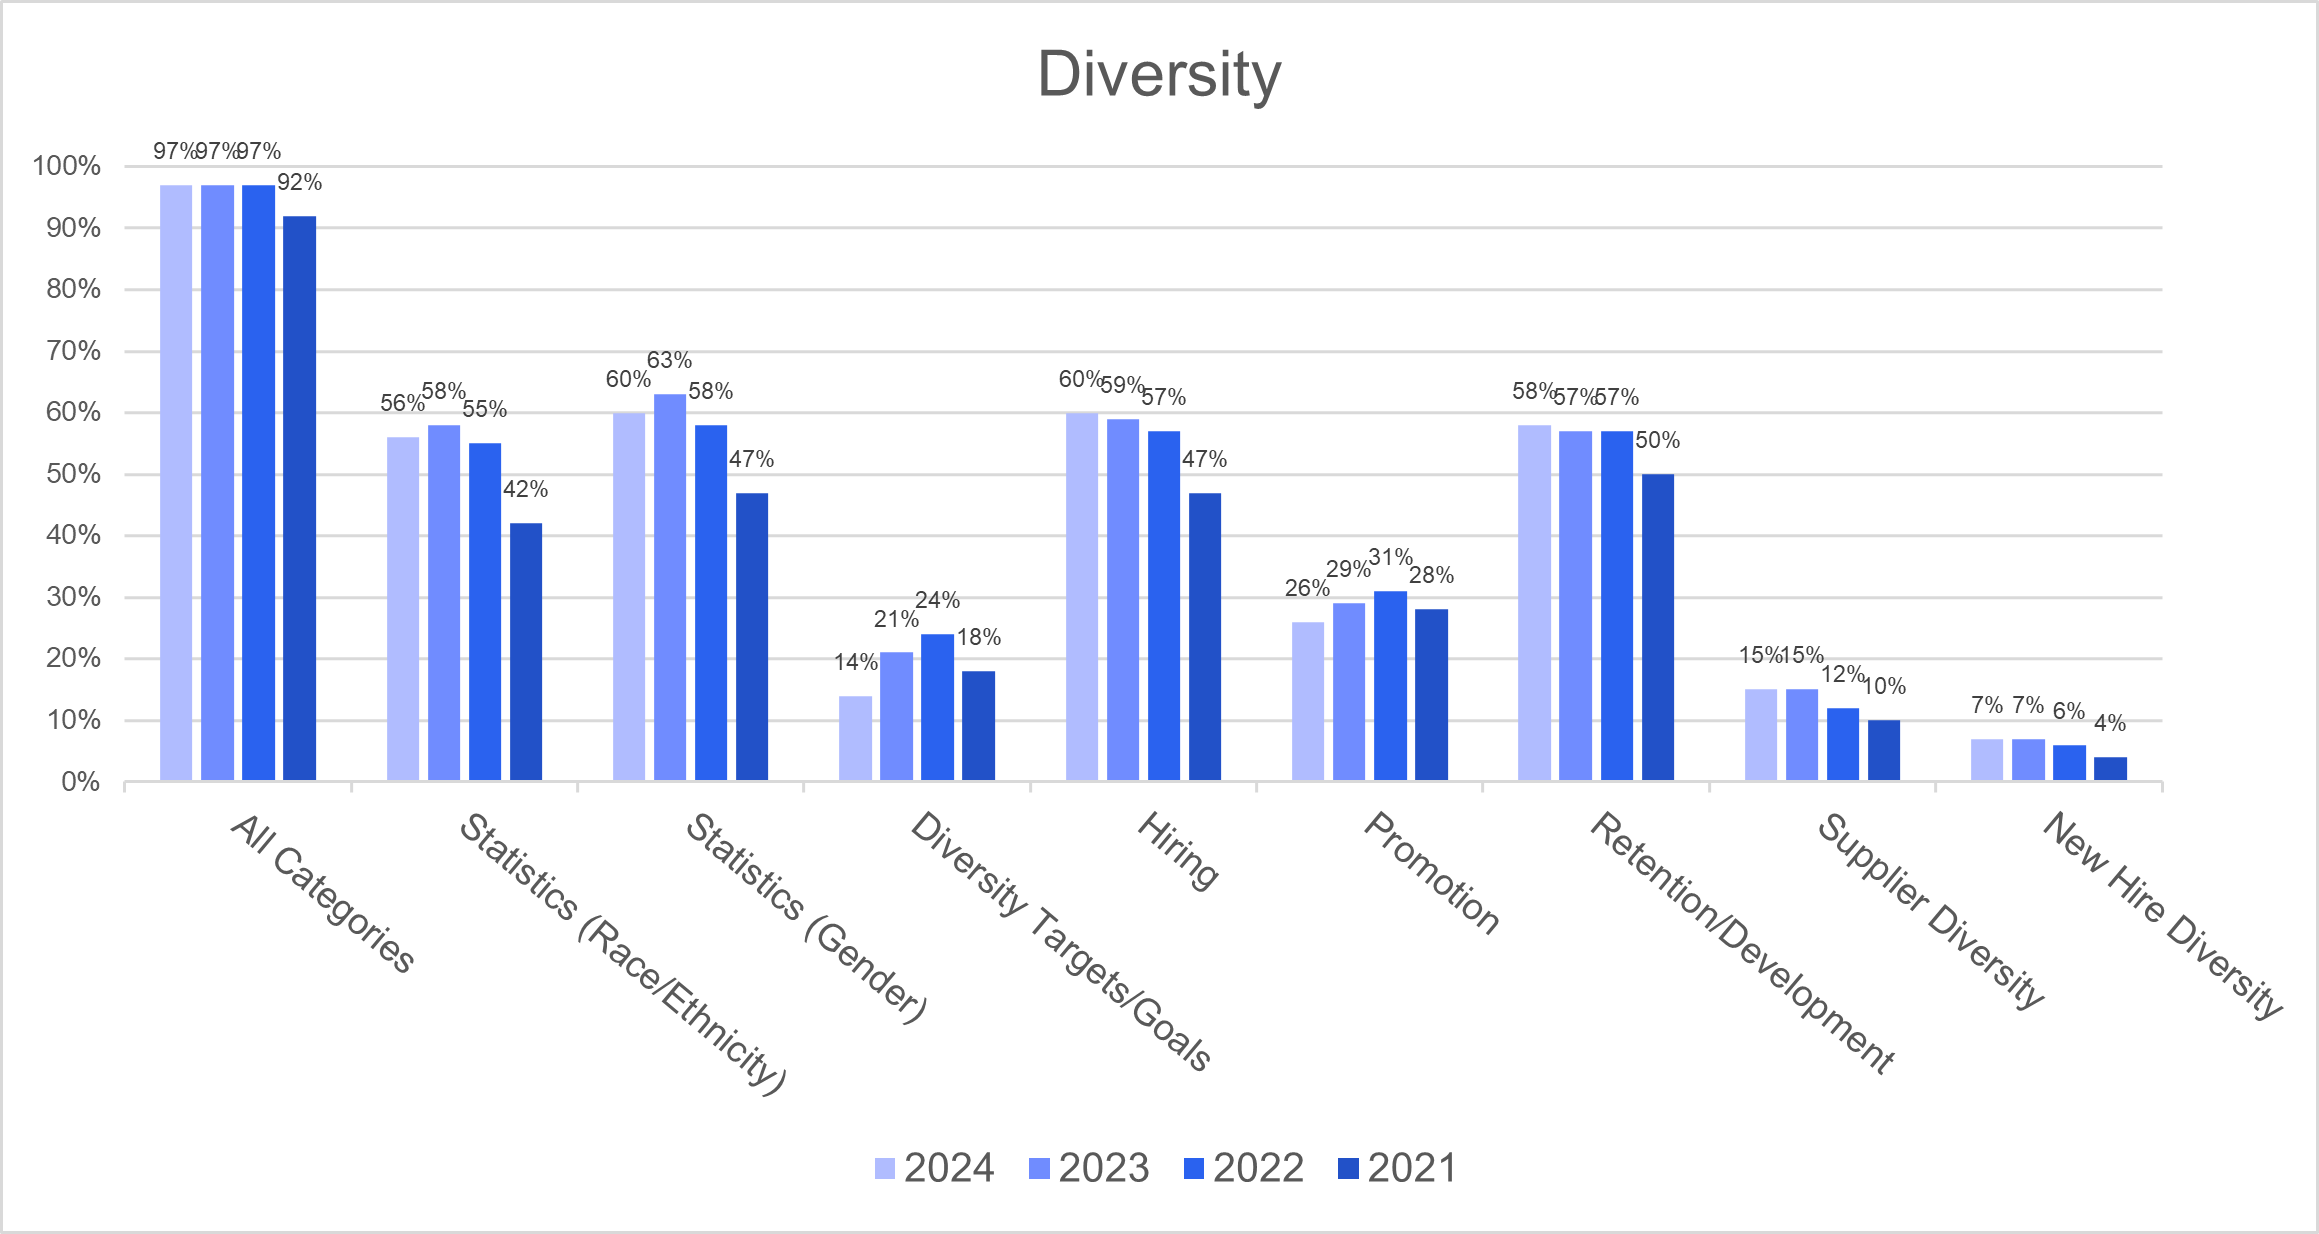 |
C. Recruiting, Training, Succession
Among S&P 100 companies, 99% included disclosures relating to talent and succession planning in one or more of the following categories:
- Talent attraction and retention. These disclosures were generally qualitative and focused on efforts to recruit and retain qualified individuals. While general statements regarding recruiting and retaining talent were very common, with 96% of companies including this type of disclosure (relatively flat in the prior two years, but up significantly from 66% in 2021), quantitative measures of retention, like workforce turnover rate, were uncommon, with only 19% of companies disclosing such statistics (as noted above).
- Talent development. Disclosures related to talent development were the most common category, with 98% of companies including a qualitative discussion regarding employee training, learning, and development opportunities, up from 83% in 2021. This disclosure tended to focus on the workforce as a whole rather than specifically on senior management. Companies generally discussed training programs such as in-person and online courses, leadership development programs, mentoring opportunities, tuition assistance, and conferences. Some companies discussed quantitative figures related to talent development, such as the number of hours employees spent on learning and development or the company’s investment in development resources, with 19% of companies including this type of disclosure.
- Succession planning. Only 33% of companies surveyed addressed their succession planning efforts, which may be a function of succession being a focus area primarily for executives rather than the human capital resources of a company more broadly. However, this is up from 27% of companies who discussed succession planning in 2021.
 |
D. Employee Compensation[6]
Among S&P 100 companies, 92% included disclosures relating to employee compensation, up from 77% in 2021. All of those companies included a qualitative description of the compensation and/or benefits program offered to employees, with a small minority providing quantitative measures such as minimum or average wages or investment in benefits (17% of companies surveyed in 2024, up from 12% in 2021). Of the companies surveyed, 50% addressed pay equity practices or assessments (up from 37% in 2021), and substantially fewer companies included quantitative measures of the pay gap between racially or ethnically diverse and nondiverse employees or male and female employees (17% of companies surveyed in 2024, up from 12% in 2021).
 |
E. Health and Safety
Among S&P 100 companies, 77% included disclosures relating to health and safety in one or both of the following categories:
- Workplace safety. Of the companies surveyed, 55% included qualitative disclosures relating to workplace health and safety, down from 63% in 2022, typically consisting of statements about the company’s commitment to safety in the workplace generally and compliance with applicable regulatory and legal requirements. However, 9% of companies surveyed provided quantitative disclosures in this category, generally focusing on historical and/or target incident or safety rates or investments in safety programs. These quantitative disclosures tended to be more prevalent among industrial, energy, and manufacturing companies.
- Employee mental health. In connection with disclosures about benefits provided to employees, including benefits intended to support employees’ general wellness or wellbeing, 54% of companies disclosed initiatives taken to support employees’ mental or emotional health and wellbeing, up from 37% in 2021.
 |
F. Culture and Engagement
In addition to the many instances where companies included general descriptions of their commitment to company culture and values, 83% of S&P 100 companies discussed specific initiatives they were taking related to culture and engagement in one or more of the following categories:
- Culture and engagement initiatives. Specific disclosures relating to practices and initiatives undertaken to build and maintain their culture and values have increased steadily each year, with 35% of the companies surveyed providing such disclosure, up from 18% in 2021. These companies most commonly discussed efforts to communicate with employees (e.g., through town halls, CEO outreach, trainings, or conferences and presentations) and to recognize employee contributions (e.g., awards programs and individualized feedback). Many companies also discussed culture in the context of diversity-related initiatives designed to help foster an inclusive culture.
- Monitoring culture. Of the companies surveyed 69% provided disclosures about the ways that companies monitor culture and employee engagement, up from 54% in 2021. Companies generally disclosed the frequency of employee surveys used to track employee engagement and satisfaction, with some reporting on the results of these surveys, sometimes measured against prior year results or industry benchmarks, and ways in which company management or the board utilized survey results.
- Flexible Work Opportunities. About one-third of S&P 100 companies describe flexible working arrangements, including remote or hybrid work or scheduling adjustments to accommodate different ways of working, with 34% of companies provided such disclosure in 2024, compared to 16% in 2021. Although many of these companies discussed this topic in previous years, past mentions of measures related to flexible work environments were generally in connection with COVID-related safety concerns, whereas recent discussions are increasingly related to talent acquisition and retention.
- Community investment. Some companies disclosed information about community investment, partnerships, donations, or volunteer programs sponsored by the company, with 25% of companies surveyed providing such disclosure in 2024, compared to 28% in 2023 and 18% in 2021. Many companies discussed their community investment efforts as offshoots of or in conjunction with their diversity, equity, and inclusion efforts.
 |
G. COVID-19
The number of S&P 100 companies that included information regarding COVID-19 and its impact on company policies and procedures or on employees dropped to only one companies making such disclosure, compared to 34% in 2023 and 70% in 2022. This sharp decline in COVID-19 disclosures is consistent with a more general trend of companies discussing COVID-19 less frequently as a result of its decreasing significance and illustrates the expected evolution of disclosure resulting from a principles-based framework.
H. Human Capital Management Governance and Organizational Practices
Just over half of S&P 100 companies (54% of those surveyed, compared to 40% in 2021) addressed their governance and organizational practices (such as oversight by the board of directors or a committee and the organization of the human resources function).
III. Industry Trends
One of the main rationales underlying the adoption of principles-based—rather than prescriptive—requirements for human capital disclosures is that the relative significance of various human capital measures and objectives varies by industry. This is reflected in the following industry trends that we observed:[7]
- Technology Industries (E-Commerce, Internet Media & Services, Hardware, Software & IT Services, and Semiconductors). For the 22 companies in the Technology Industries, at least 63% discussed each of talent development and training opportunities, talent attraction, recruitment and retention, employee compensation, employee mental health, and diversity. Compared to the S&P 100 as a whole, relatively uncommon disclosures among this group included part-time and full-time employee statistics (5%), succession planning (9%), supplier diversity (5%), diversity in retention and development (41%), quantitative diversity statistics regarding race/ethnicity and gender (41% and 45%, respectively), and unionized employee relations (18%). However, these industries continued to see increased rates of disclosure compared to the S&P 100 for quantitative turnover rates (41%), flexible work opportunities (45%), culture initiatives (45%), and qualitative pay equity (59%).
- Finance Industries (Asset Management & Custody Activities, Consumer Finance, Commercial Banks, and Investment Banking & Brokerage). For the 13 companies in the Finance Industries, a large majority continued to include quantitative diversity statistics regarding race (85%) and gender (92%) (matching that of the last two years) and qualitative disclosures regarding employee compensation (92%), and, compared to other industries, a relatively higher number discussed diversity in hiring (85%), employee mental health (77%), flexible work opportunities (69%), pay equity (69%), and quantified their pay gap (46%). Relatively uncommon disclosures among this group included part-time and full-time employee statistics, unionized employee relations, quantitative workforce turnover rates, diversity targets and goals, quantitative new hire diversity, supplier diversity, and workplace safety (in each case less than 16%).
- Pharmaceutical Industries (Biotechnology & Pharmaceuticals). For the eight companies in the Pharmaceutical Industries, at least 87% discussed each of diversity, workplace safety, monitoring culture, talent attraction and retention, talent development, and employee compensation. Compared to the S&P 100 as a whole, relatively uncommon disclosures among this group included succession planning (13%), quantitative pay gap (0%), and diversity targets and goals (0%). However, these industries continued to see increased rates of disclosure compared to the S&P 100 for supplier diversity (38%), workplace safety (88%), culture initiatives (50%), and flexible work opportunities (75%).
IV. Disclosure Format
The format of human capital disclosures in S&P 100 companies’ annual reports on Form 10‑K continued to vary greatly.
Word Count. The length of the disclosures ranged from 106 to 1,809 words, with the following statistical trends in the past four years:
| 2024 | 2023 | 2022 | 2021 | |
| Minimum word count | 106 | 106 | 109 | 105 |
| Maximum word count | 1,809 | 2,094 | 1,995 | 1,931 |
| Median | 913 | 1,035 | 959 | 818 |
| Mean | 946 | 1,002 | 976 | 825 |
Metrics. The disclosure requirement specifically asks for a description of “any human capital measures or objectives that the registrant focuses on in managing the business” (emphasis added). Our survey revealed that companies are increasingly providing quantitative metrics, with 84% of companies providing disclosure in at least one of the quantitative categories we discuss above (compared to 87% in 2023, 80% in 2022, and 67% in 2021) and only 8% electing not to include any type of quantitative metrics beyond headcount numbers (compared to 7% in 2023, 10% in 2022 and 14% in 2021).
Graphics. Although the minority practice, 26% of companies surveyed also included tables, charts, graphics or similar formatting used to draw attention to particular elements, compared to 26% in 2023, 24% in 2022 21% in 2021, which were generally used to present statistical data, such as diversity statistics or breakdowns of the number of employees by geographic location.
Categories. Most companies organized their disclosures by categories similar to those discussed above and included headings to define the types of disclosures presented.
V. Upcoming Rulemaking and Investor Advisory Committee Recommendations
At its meeting on September 21, 2023, the Commission’s Investor Advisory Committee (“IAC”) approved subcommittee recommendations (the “IAC Recommendations”) to expand required human capital management disclosures.[8] The IAC Recommendations contain prescriptive disclosure requirements—many of which have been previously considered as part of the 2020 rulemaking—for various quantitative metrics in the business description of Form 10-K under Item 101(c) of Regulation S-K (including headcount, turnover, compensation, and demographic data) as well as narrative disclosure in Management Discussion and Analysis. For details regarding the IAC Recommendations, please refer to “Form 10-K Human Capital Disclosures Continue to Evolve,” available here.
According to the most recent Regulatory Flexibility agenda, a human capital management rule proposal that was originally slated for October 2021 was expected to be issued in October 2024.[9] However, no rule was ever proposed, and many expect regulatory priorities to change with the upcoming shift in the administration, including SEC Chair Gary Gensler’s upcoming departure on January 20, 2025. We therefore do not expect that the Commission will be adopting IAC’s recommendations in the near term as Republican commissions have in the past generally favored principles-based disclosure over prescriptive disclosure requirements.
VI. Comment Letter Correspondence
Comment letter correspondence from the staff of the Division of Corporation Finance (the “Staff”), which often helps put a finer point on principles-based disclosure requirements like this one, has shed relatively little light on how the Staff believes the new requirements should be interpreted. Consistent with what we found at this time in the prior three years, the comment letters, all of which involved reviews of registration statements, were generally issued to companies whose disclosures about employees were limited to the bare-bones items companies have discussed historically, such as the number of persons employed and the quality of employee relations. From these companies, the Staff simply sought a more detailed discussion of the company’s human capital resources, including any human capital measures or objectives upon which the company focuses in managing its business. There were also a few comment letters where the Staff asked companies to clarify statements in their human capital disclosures or expand their human capital disclosures based on related risks identified in their risk factors.[10] Based on our review of the responses to those comment letters, we have not seen a company take the position that a discussion of human capital resources was immaterial and therefore unnecessary.
VIII. Conclusion
Based on our survey, companies continue to be thoughtful about their human capital disclosures—expanding their disclosures in some areas (e.g., culture initiatives and pay equity) and reducing them in others (e.g., COVID-19, diversity targets and goals, diversity in promotion, and community investment)—in response to ever-changing circumstances. That is precisely what principles-based disclosure rules are designed to elicit.
To that end, as companies prepare for the upcoming Form 10-K reporting season, they should consider the following:
- Confirm (or reconfirm) that the company’s disclosure controls and procedures support the statements made in human capital disclosures knowing that controls in the HR department may not be as rigorous as accounting controls. These disclosures create legal liability risks and should be treated accordingly.
- Companies may want to compare their own disclosures against what their industry peers did these past four years, including specifically any notable changes to disclosures made in the past year.
- Remind stakeholders internally that these disclosures likely will continue to evolve. This is especially true with the change in administration that could result in companies focusing on fewer or different issues. The types of measures and objectives that a company focuses on in managing its business and that are material to each company may also change in response to current events, as was shown by essentially the complete removal of COVID-19 related disclosures from 10-K filings the past two years and the decrease in disclosures relating to diversity targets and goals over the same period.
- If you continue to disclose targets, expect the SEC staff to ask you to disclose the progress that management has made. You may wish to reconsider the utility in disclosing specific targets.
- Addressing in the upcoming disclosure, if not already disclosed, the progress that management has made with respect to any significant objectives it has set regarding its human capital resources as investors are likely to focus on year-over-year changes and the company’s performance versus stated goals.
- Addressing significant areas of focus highlighted in engagement meetings with investors and other stakeholders. In a 2024 survey, human capital management was one of the top five issues (aside from financial performance) most important to investors when evaluating companies.[11]
- Revalidating the methodology for calculating quantitative metrics and assessing consistency with the prior year. Former Chairman Clayton commented that he would expect companies to “maintain metric definitions constant from period to period or to disclose prominently any changes to the metrics.”
[1] Data provided is as of November 10, 2024 and is based on the companies currently included within the S&P 500, so some statistics are slightly different than they were in the prior surveys. The categorization data necessarily involves subjective assessment and should be considered approximate.
[2] See 17 C.F.R. § 229.101(c)(2)(ii).
[3] Agency Rule List – Spring 2024 Securities and Exchange Commission, Office of Information and Regulatory Affairs (2024), available here.
[4] Note that companies often include additional human capital management-related disclosures in their ESG/sustainability/social responsibility reports, on their websites, and in their proxy statements, but these disclosures are outside the scope of the survey, which is focused on disclosures included in Part I, Item 1 of annual reports on Form 10-K.
[5] While never expressly required by Regulation S-K, as a result of disclosure review comments issued by the Division of Corporation Finance over the years and a decades-old and since-deleted requirement in Form 1-A, it has been a relatively common practice to discuss collective bargaining and employee relations in the Form 10-K or in an IPO Form S-1, particularly since the threat of a workforce strike could be material.
[6] Our survey reviewed the employee compensation disclosures contained in Part I, Item 1 of each company’s Form 10-K and did not separately review any employee compensation information included in companies’ financial statements or the notes thereto.
[7] For purposes of our survey, we grouped companies in similar industries based on both their four-digit Standard Industrial Classification code and their designated industry within the Sustainable Industry Classification System. The industry groups discussed in this section cover 43% of the companies included in our survey.
[8] Available at https://www.sec.gov/files/spotlight/iac/20230921-recommendation-regarding-hcm.pdf.
[9] Agency Rule List – Spring 2024 Securities and Exchange Commission, Office of Information and Regulatory Affairs (2024), available here.
[10] See, e.g., comments issued to Concentra Group Holdings Parent, Inc. (available at https://www.sec.gov/Archives/edgar/data/2014596/000000000024003738/filename1.pdf) and PACS Group, Inc. (available at https://www.sec.gov/Archives/edgar/data/2001184/000000000024000134/filename1.pdf).
[11] See PwC’s Global Investor Survey 2024, available at https://www.pwc.com/gx/en/issues/c-suite-insights/global-investor-survey.html.
Gibson Dunn’s lawyers are available to assist with any questions you may have regarding these developments. To learn more about these issues, please contact the Gibson Dunn lawyer with whom you usually work in the firm’s Securities Regulation and Corporate Governance or Labor and Employment practice groups, or any of the following practice leaders and members:
Securities Regulation and Corporate Governance:
Elizabeth Ising – Co-Chair, Washington, D.C. (+1 202.955.8287, eising@gibsondunn.com)
James J. Moloney – Co-Chair, Orange County (+1 949.451.4343, jmoloney@gibsondunn.com)
Lori Zyskowski – Co-Chair, New York (+1 212.351.2309, lzyskowski@gibsondunn.com)
Aaron Briggs – San Francisco (+1 415.393.8297, abriggs@gibsondunn.com)
Thomas J. Kim – Washington, D.C. (+1 202.887.3550, tkim@gibsondunn.com)
Brian J. Lane – Washington, D.C. (+1 202.887.3646, blane@gibsondunn.com)
Julia Lapitskaya – New York (+1 212.351.2354, jlapitskaya@gibsondunn.com)
Ronald O. Mueller – Washington, D.C. (+1 202.955.8671, rmueller@gibsondunn.com)
Michael Scanlon – Washington, D.C.(+1 202.887.3668, mscanlon@gibsondunn.com)
Michael A. Titera – Orange County (+1 949.451.4365, mtitera@gibsondunn.com)
Labor and Employment:
Jason C. Schwartz – Co-Chair, Washington, D.C. (+1 202.955.8242, jschwartz@gibsondunn.com)
Katherine V.A. Smith – Co-Chair, Los Angeles (+1 213.229.7107, ksmith@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
On December 3, 2024, a federal district court in Texas ruled that the Corporate Transparency Act (CTA) is likely unconstitutional and preliminarily enjoined its enforcement nationwide. Accordingly, the rule’s requirements cannot currently be enforced against entities that would otherwise be subject to the rule. Thus, as it currently stands, reporting companies that were required to make a CTA filing by the end of the year are not required to do so, although that posture could change very quickly depending on the government’s next steps. This update briefly describes the ruling and what it means for CTA compliance moving forward.[1]
The Corporate Transparency Act, enacted in 2021, requires all corporations, limited liability companies, and certain other entities created (or, as to non-U.S. entities, registered to do business) in any U.S. state or tribal jurisdiction to file a beneficial ownership interest (BOI) report with the U.S. Financial Crimes Enforcement Network (FinCEN) identifying, among other information, the natural persons who are beneficial owners of the entity.[2] A regulation, the Reporting Rule, helps implement the CTA by specifying compliance deadlines—including a January 1, 2025 deadline for companies created or registered to do business in the United States before January 1, 2024—and detailing what information must be reported to FinCEN.[3]
On March 1, 2024, the U.S. District Court for the Northern District of Alabama ruled that the CTA is unconstitutional.[4] The court permanently enjoined the government from enforcing the CTA, but only as to the plaintiffs in that case.[5] The government appealed, and the Eleventh Circuit heard oral argument on September 27. The Eleventh Circuit’s decision in that case remains pending.
The December 3, 2024 Ruling
Six plaintiffs, among which include a small business named Texas Top Cop Shop, Inc. and the National Federation of Independent Business (NFIB), brought a lawsuit challenging the constitutionality of the CTA and the Reporting Rule on various grounds. On December 3, 2024, Judge Amos L. Mazzant of the U.S. District Court for the Eastern District of Texas granted the plaintiffs’ motion for a preliminary injunction.[6] Like the Northern District of Alabama, the court held that the CTA exceeds Congress’s enumerated powers. Specifically, in a 79-page opinion, Judge Mazzant ruled that it was likely that the plaintiffs would be able to prove that:
- The CTA is not a proper exercise of Commerce Clause power because it does not regulate a channel or instrumentality of interstate commerce or any activity that substantially affects commerce[7]; and
- The CTA cannot be justified under the Necessary and Proper Clause because, contrary to the government’s assertions, it is not rationally related to any enumerated power to regulate commerce, conduct foreign affairs, or collect taxes.[8]
The court’s reasoning about the scope of the Commerce Clause, Necessary and Proper Clause, foreign affairs power, and taxing power echoed that of the Northern District of Alabama. While the Northern District of Alabama enjoined enforcement of the CTA against only the plaintiffs in that case, the Eastern District of Texas went further. Observing that an injunction pertaining to plaintiff NFIB’s approximately 300,000 members would be tantamount to a nationwide injunction, the court concluded that it was appropriate to preliminarily enjoin enforcement of the CTA and the Reporting Rule nationwide.[9] Moreover, the court invoked its power under the Administrative Procedure Act’s stay provision, 5 U.S.C. § 705, to “postpone the effective date of” the Reporting Rule.[10]
Potential U.S. Government Response
The government has 60 days to appeal the district court’s preliminary injunction to the U.S. Court of Appeals for the Fifth Circuit, though it may do so earlier.[11] The government may also ask the district court or the Fifth Circuit for an emergency stay of the district court’s preliminary injunction in full or in part during the pendency of any appeal. Any such emergency application would be considered by the Fifth Circuit on an expedited basis. If the Fifth Circuit leaves the district court’s order in place, the government could then seek emergency relief in the Supreme Court, which could also stay the injunction pending appeal.
In the meantime, FinCEN will likely issue a notice clarifying its position on the impact of the district court’s order, including potentially extending the January 1, 2025 filing deadline.
Ultimately, the validity of the CTA is unlikely to be resolved nationwide without Supreme Court review or unanimous decisions from the federal courts of appeals who consider the question. Notably, district courts in Michigan,[12] Oregon,[13] and Virginia[14] have denied similar requests for preliminary injunctions against enforcement of the CTA. The Eastern District of Virginia, for example, concluded that the CTA is an exercise of Congress’s Commerce Clause power because it regulates an activity—operating a corporate entity as a going concern—that in the aggregate substantially affects interstate commerce.[15]
What the Ruling Means for Entities Subject to the CTA
Given the district court’s nationwide preliminary injunction and stay of the Reporting Rule’s effective date, the rule’s requirements cannot currently be enforced against entities that would otherwise be subject to the rule. Thus, as it currently stands, reporting companies that were required to make a CTA filing are not required to do so.
Given the possibility of either the Fifth Circuit or the Supreme Court staying the district court’s order pending appeal, however, reporting entities’ legal obligations are subject to change on short notice, and as a general matter companies should not assume that the January 1, 2025 deadline will ultimately be extended without further guidance from FinCEN. If either the Fifth Circuit or Supreme Court stay the district court’s order pending appeal, the Reporting Rule will become enforceable again, and the rule’s deadlines will become effective as to all entities that are not parties to the litigation in the Northern District of Alabama—though FinCEN may adjust those deadlines depending on how long the district court’s order remains in effect. It also remains to be seen whether the incoming administration will continue to defend the constitutionality of the CTA or not, although as a general rule the Department of Justice typically defends the constitutionality of federal statutes regardless of administration.[16]
Entities that believe they may be subject to the Reporting Rule should closely monitor this matter, and consult with their CTA advisors as necessary, to understand whether and when they need to comply with the Reporting Rule’s requirements and to allow for sufficient lead time in advance of any filing deadline.
We note that this ruling deals only with the federal CTA passed by Congress, not similar legislation passed by states such as New York, which have enacted similar requirements.[17] Gibson Dunn will continue to monitor CTA developments closely.
[1] Prior alerts by Gibson Dunn explaining the Corporate Transparency Act are available at: https://www.gibsondunn.com/top-12-developments-in-anti-money-laundering-enforcement-in-2023; https://www.gibsondunn.com/the-impact-of-fincens-beneficial-ownership-regulation-on-investment-funds; https://www.gibsondunn.com/the-corporate-transparency-act-reminders-and-key-updates-including-fincen-october-3-faqs.
[2] See William M. (Mac) Thornberry National Defense Authorization Act for Fiscal Year 2021, Pub. L. 116-283, Div. F., § 6403 (adding 31 U.S.C. § 5336).
[3] 31 C.F.R. § 1010.380.
[4] Nat’l Small Business United v. Yellen, 721 F. Supp. 3d 1260 (N.D. Ala. 2024); see https://www.gibsondunn.com/corporate-transparency-act-declared-unconstitutional-what-it-means-for-you.
[5] Nat’l Small Business Union et al. v. Yellen et al., No. 5:22-cv-01448, Dkt. 52 (N.D. Ala. 2024).
[6] Texas Top Cop Shop, Inc. et al. v. Garland et al., No. 4:24-CV-478, Dkt. 30 (E.D. Tex. Dec. 3, 2024).
[7] Id. at 35–53.
[8] Id. at 53–73.
[9] Id. at 74–75, 77.
[10] Id. at 78.
[11] Fed. R. App. P. 4(a)(1)(B).
[12] Small Business Ass’n of Mich. et al. v. Yellen et al., No. 1:24-cv-00314-RJJ-SJB, Dkt. 24 (W.D. Mich. Apr. 26, 2024).
[13] Firestone et al. v. Yellen et al., No. 3:24-cv-1034-SI, Dkt. 18 (D. Ore. Sept. 20, 2024).
[14] Cmty. Ass’ns Inst. et al. v. Yellen et al., No. 1:24-cv-1597 (MSN/LRV), Dkt. 40 (E.D. Va. Oct. 24, 2024).
[15] Id. at 14; see also Firestone, supra note 13, at 12–14.
[16] See https://www.gibsondunn.com/tools-of-transition-procedural-devices-could-help-president-elect-implement-agenda.
[17] See S.995-B/A.3484-A
Gibson Dunn has deep experience with issues relating to the Bank Secrecy Act, the Corporate Transparency Act, other AML and sanctions laws and regulations, and challenges to Congressional statutes and administrative regulations.
For assistance navigating white collar or regulatory enforcement issues, please contact the authors, the Gibson Dunn lawyer with whom you usually work, or any leader or member of the firm’s Anti-Money Laundering, Administrative Law & Regulatory, Investment Funds, Real Estate, or White Collar Defense & Investigations practice groups.
Please also feel free to contact any of the following practice group leaders and members and key CTA contacts:
Anti-Money Laundering:
Stephanie Brooker – Washington, D.C. (+1 202.887.3502, sbrooker@gibsondunn.com)
M. Kendall Day – Washington, D.C. (+1 202.955.8220, kday@gibsondunn.com)
David Ware – Washington, D.C. (+1 202-887-3652, dware@gibsondunn.com)
Ella Capone – Washington, D.C. (+1 202.887.3511, ecapone@gibsondunn.com)
Sam Raymond – New York (+1 212.351.2499, sraymond@gibsondunn.com)
Chris Jones – Los Angeles (+1 213.229.7786, crjones@gibsondunn.com)
Administrative Law and Regulatory:
Stuart F. Delery – Washington, D.C. (+1 202.955.8515, sdelery@gibsondunn.com)
Eugene Scalia – Washington, D.C. (+1 202.955.8673, dforrester@gibsondunn.com)
Helgi C. Walker – Washington, D.C. (+1 202.887.3599, hwalker@gibsondunn.com)
Matt Gregory – Washington, D.C. (+1 202.887.3635, mgregory@gibsondunn.com)
Investment Funds:
Kevin Bettsteller – Los Angeles (+1 310.552.8566, kbettsteller@gibsondunn.com)
Shannon Errico – New York (+1 212.351.2448, serrico@gibsondunn.com)
Greg Merz – Washington, D.C. (+1 202.887.3637, gmerz@gibsondunn.com)
Real Estate:
Eric M. Feuerstein – New York (+1 212.351.2323, efeuerstein@gibsondunn.com)
Jesse Sharf – Los Angeles (+1 310.552.8512, jsharf@gibsondunn.com)
Lesley V. Davis – Orange County (+1 949.451.3848, ldavis@gibsondunn.com)
Anna Korbakis – Orange County (+1 949.451.3808, akorbakis@gibsondunn.com)
White Collar Defense and Investigations:
Stephanie Brooker – Washington, D.C. (+1 202.887.3502, sbrooker@gibsondunn.com)
Winston Y. Chan – San Francisco (+1 415.393.8362, wchan@gibsondunn.com)
Nicola T. Hanna – Los Angeles (+1 213.229.7269, nhanna@gibsondunn.com)
F. Joseph Warin – Washington, D.C. (+1 202.887.3609, fwarin@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
In this update, we explore the possible impacts of the 2024 presidential election on emissions regulations for light- and heavy-duty motor vehicles and on- and off-road engines, known collectively as “mobile sources.”
Based on actions during President-elect Trump’s previous term, we anticipate that the second Trump Administration will move swiftly to rescind and replace federal rules regarding mobile source emissions and seek to limit California’s authority to regulate such emissions. Below we outline the anticipated implications for industry of forthcoming changes to the existing federal and California regulations, related anticipated litigation, and potential compliance and enforcement considerations for industry.
The key takeaways for industry are:
- The second Trump Administration is likely to deny pending requests by California for authorization to adopt and enforce its own mobile source emissions regulations and to revoke existing preemption waivers allowing California to issue mobile source greenhouse gas (GHG) standards in particular.
- If these waivers are later restored, manufacturers may face retroactive enforcement by the California Air Resources Board (CARB), which has recently stated in other contexts that it will seek to enforce its regulations back to the state law effective date upon the receipt of a preemption waiver or authorization.
- New litigation surrounding the denial or revocation of California’s waivers is likely to arise, but any cases seeking to restore California’s waivers will be heard by a judiciary—including a Supreme Court—shaped by the appointees of the first Trump Administration.
- From an enforcement perspective, the U.S. Environmental Protection Agency (EPA) will retain primacy for mobile source enforcement even if the next Trump Administration moves back to a policy focused on state-first enforcement. If the EPA de-prioritizes GHG enforcement, the balance of the enforcement docket may shift to criteria pollutant cases, such as enforcement related to NOx or PM emissions.
Federal Rules
During the first Trump Administration, the U.S. Environmental Protection Agency (EPA) undertook efforts to change mobile source emission rules, in particular by replacing an increasingly strict GHG emissions regime from the Obama Administration with rules that did not become more stringent year-over-year. We anticipate that during President-elect Trump’s second term, his administration may move again to reduce the stringency of the previous administration’s emissions regulations pertaining to GHGs.
First Trump Administration Recission of Federal Rules
In August 2018, the EPA, along with the National Highway Traffic Safety Administration (NHTSA), initiated a rulemaking to amend the existing tailpipe emissions standards and fuel economy requirements for passenger cars and light trucks and establish new standards for model years 2021 through 2026.[1] This action, which was finalized in April 2020, froze the federal GHG emissions and fuel economy standards at model year 2020 levels through 2026.[2]
Lessons for the Second Trump Administration
During the second Trump Administration, we anticipate that the EPA will again take action to rescind the previous administration’s vehicle and engine emissions standards, particularly GHG standards. Based on campaign statements and Project 2025, an extensive suite of policy proposals from major conservative groups including many appointees from President-elect Trump’s first administration,[3] the EPA will likely rescind the Biden EPA’s model year 2027 through 2032 light- and medium-duty vehicle emissions standards.[4] The Trump Administration’s replacement rule will likely slow the rate at which the GHG standards ramp up.[5] We also anticipate that the Trump Administration’s replacement rule will significantly reduce the pressure on manufacturers to meet emissions standards through the sale of electric vehicles (although this seems less certain given the anticipated role that Tesla CEO Elon Musk will have in the second Trump Administration).[6]
Project 2025 also contemplates that NHTSA will amend its fuel economy standards and return to the minimum average fuel economy standards specified by Congress for model year 2020 vehicles, including levels aimed at achieving a fleet-wide average of 35 miles per gallon.[7] NHTSA may also reconsider existing fuel economy credits for electric vehicles.[8]
California Rules
Outlook for Section 209 Waivers
Under the Clean Air Act, states are expressly preempted from adopting or enforcing emissions standards for new motor vehicles and engines.[9] However, a statutory exemption exists for California: EPA has authority under Section 209 to issue a preemption waiver to California to establish, and enforce, its own standards for new motor vehicle and engine emissions that are at least as strict as the federal standards, if certain statutory criteria are met.[10] Currently, eight California rules are under waiver or authorization review by EPA, including the following CARB rules with significant compliance implications and costs for the regulated industry:
|
California Rule |
Federal Register Notice |
|
Heavy-Duty Omnibus Low NOx Waiver Request |
87 Fed. Reg. 35765 (Jun. 13, 2022) |
|
Commercial Harbor Craft Authorization Request |
88 Fed. Reg. 25636 (Apr. 27, 2023) |
|
Advanced Clean Car II Waiver Request |
88 Fed. Reg. 88908 (Dec. 26, 2023) |
|
In-Use Locomotive Authorization Request |
89 Fed. Reg. 14484 (Feb. 27, 2024) |
|
Advanced Clean Fleets Waiver Request |
89 Fed. Reg. 57151 (Jul. 12, 2024) |
In addition, for some other recent rules, such as the Zero-Emissions Forklift Rule, which mandates a complete transition to powertrains with no tailpipe emissions, CARB has not yet submitted a waiver application to the EPA.
If these waiver and authorization requests are not finalized during President Biden’s lame-duck period, they likely will be denied by a Trump EPA. Based on the Trump EPA’s approach during the first administration, it is likely that President-elect Trump’s EPA will revoke existing waivers granted to California. The ability of California to secure waivers or authorizations from the EPA during the second Trump Administration based on new requests is also questionable.
In particular, campaign statements and Project 2025 indicate that the next Administration will revoke any Section 209(b) waiver that does not apply only to California-specific issues such as ground-level ozone, including any waiver to issue vehicle GHG standards.[11] President-elect Trump campaigned on a platform that no state should have the authority to ban gasoline-powered cars, which implicates California’s waiver that has been used to order the phase-out of gas-powered vehicles and transition to electric vehicles beginning in model year 2026 through model year 2035.[12]
CARB Response to Waiver Recission and Restoration During the First Trump Administration
Looking back to the first Trump Administration may provide a preview of future conflict between CARB and the Trump EPA regarding Section 209 waivers. During the first Trump Administration, in August 2018, the EPA proposed to withdraw CARB’s previously granted Section 209(b) waiver for its Advanced Clean Cars regulation.[13] In September 2019, the EPA finalized this rule, revoking California’s Section 209(b) waiver to enforce unique state motor vehicle GHG standards for model years 2021 through 2025.[14]
During the interim period between the Trump EPA’s initial proposal to revoke California’s waiver and the actual revocation, CARB modified its existing GHG rules for model years 2021 through 2026 to state that, should the EPA change federal emission standards, vehicle and engine manufacturers who complied with the federal standards would no longer be considered in compliance with the significantly differing California standards.[15] In other words, CARB declared that it would no longer accept compliance with federal emissions standards as a safe harbor if the EPA were to revise the federal rules. In doing so, California departed from a prior deal struck with industry and EPA in promulgating the first harmonized GHG program at the outset of the Obama Administration (which, in turn, resolved years of litigation relating to state regulation of GHGs from motor vehicles).[16]
Next, in the summer of 2019, CARB and four automakers announced their entry into “Framework Agreements.”[17] The Framework Agreements imposed alternative GHG standards for model year 2021 through 2026 light-duty vehicles, and were described by the Trump EPA as “a voluntary agreement with four automobile manufacturers that amongst other things, requires the manufacturers to refrain from challenging California’s GHG and [Zero-Emission Vehicle] programs, and provides that California will accept automobile manufacturer compliance with a less stringent standard” than either the existing California program or the federal regulations promulgated in 2012.[18]
As a result, during the period when CARB’s waiver was revoked, manufacturers were subject to significant regulatory uncertainty. Some manufacturers complied with the federal regulations, which EPA and NHTSA maintained were the only lawful regulations. Other manufacturers entered into agreements with CARB to comply with the requirements of the Framework Agreement. Overlaying all of this, CARB’s own original GHG emissions standards remained the law in California, and CARB maintained that their waiver was improperly revoked, raising the specter of retroactive enforcement should it be restored.[19]
In March 2022, under President Biden, the EPA reinstated California’s Section 209(b) waiver to issue and enforce motor vehicle GHG standards.[20] OEMs expressed concern that CARB could seek to retroactively enforce its separate standards for the period during which California’s waiver had been revoked.[21] This was particularly challenging because, during the period where CARB’s waiver was withdrawn, many manufacturers followed the federal regulations and made decisions that fixed their vehicle production strategies for model years 2021 and 2022, leaving them with a lack of lead time to comply with CARB’s regulations after its waiver was reinstated.
Potential CARB Retroactive Enforcement in the Second Trump Administration
The potential for retroactive enforcement will remain a challenge in the new Trump Administration. CARB has indicated in several contexts that it will seek to enforce state law retroactively upon the receipt of EPA waiver or authorization. For example, CARB’s Advanced Clean Fleets (ACF) waiver request is still pending with EPA,[22] but in December 2023, CARB issued an “Enforcement Notice” stating that it “reserves all of its rights to enforce the ACF regulation in full for any period for which a waiver is granted” including back to the effective date of the rule under California law.[23] In comments on the EPA waiver proceeding on this rule, one comment rightfully pointed out that “to apply the waiver retroactively violates both the [Clean Air Act] and basic principles of due process” and observed that CARB has increasingly sought to assert this position for its rules pending waiver determinations.[24] In October 2024, CARB clarified that it would not retroactively enforce certain aspects of the ACF regulation, but this clarification did not comprehensively address all ACF requirements.[25] Notably, CARB has not provided similar clarifications for other rules.
During a second Trump Administration, CARB may renew its threats of retroactive enforcement for regulations between the period of a regulation becoming California law and receipt of a waiver or authorization from EPA. This would lead to significant regulatory uncertainty (and due process concerns) for automakers and engine manufacturers, as a Trump EPA is likely to delay or deny California’s waiver and authorization requests. Furthermore, if existing waivers are rescinded and then restored by a later administration, manufacturers may again face the situation where federal regulations were technically the sole law of the land, but California alleges the waiver revocation was improper, its regulations were still valid, and that it can retroactively enforce following the restoration. This Damocles’ sword could hang over industry’s head until the issue of California’s authority is decided by the U.S. Supreme Court or the next Democratic Administration.
Waiver Litigation
EPA’s decision to reinstate CARB’s waiver is also currently being challenged in federal court by a group of states and fuel producers. Petitioners argue that the EPA exceeded its authority under the CAA and violated a constitutional requirement to treat states equally in terms of their sovereign authority.[26] The DC Circuit held that the Petitioners did not have standing to raise the statutory claims, and it rejected Petitioners’ constitutional claim on the merits.[27] Although the petition for certiorari remains pending before the Supreme Court, a Trump Administration revocation could render this case moot by again revoking the California waiver.
However, even if the existing litigation is mooted, new waiver litigation is likely to arise. Specifically, in the event that the Trump EPA denies or revokes any of California’s waivers, new litigation will almost certainly commence to challenge such decisions, including litigation brought by the State of California.[28]
In those cases—or if the existing waiver litigation proceeds to the Supreme Court—the second Trump Administration will have an advantage that the first Trump Administration did not: the benefit of a federal judiciary, and a Supreme Court, shaped by President-elect Trump’s first term.[29] In addition, the Supreme Court’s 2024 decision in Loper Bright provides the courts with greater latitude to question agency decisions that previously may have received the benefit of Chevron deference.[30] As a result, cases trying to restore California’s waivers may face more of an uphill battle during the second Trump Administration than during the first.
Implications for Enforcement
Federal Enforcement
During the first Trump Administration, EPA policy emphasized coordination with states and allowing state agencies to take the lead in enforcement. Even under a state-focused enforcement policy, EPA remains the lead for any enforcement pursuant to Title II of the Clean Air Act relating to mobile sources and fuels, especially if California’s waivers to enforce its own mobile source emission standards are delayed, denied, or revoked. Thus, EPA’s Office of Enforcement and Compliance Assurance (OECA) will retain primacy for Title II enforcement even if the next Trump Administration moves back to a policy focused on state-first enforcement.
Furthermore, where GHG enforcement becomes less of a priority, OECA may then seek to fill its enforcement docket with criteria pollutant cases. For vehicle and engine manufacturers, this could include enforcement related to NOx or PM emissions, for example. Enforcement actions under the first Trump Administration included three major mobile source cases focused on criteria emissions all of which were focused on non-U.S. manufacturers.
CARB Enforcement
As discussed above, the recission and reinstatement of CARB’s Advanced Clean Cars waiver created significant uncertainty for manufacturers regarding enforcement risks, as the fundamental issues of which regulations were in effect, and when, were in question. To date, this dilemma and the related due process concerns created by this positioning have not been squarely addressed in the context of enforcement or an as-applied constitutional challenge.
Should a similar situation develop during the second Trump Administration, another potential method for manufacturers to seek certainty on enforcement is to enter into an agreement with CARB where CARB agrees to exercise its enforcement discretion with respect to certain regulatory terms in exchange for support for CARB’s legal positions and regulations. CARB has taken this approach not only on a manufacturer-by-manufacturer basis as mentioned above, but also entered into an agreement with a trade association and a coalition of manufacturers in the association’s membership.[31] But such an approach could face retaliation by the Trump Administration: during President-elect Trump’s first term, the U.S. Department of Justice briefly sought to investigate the manufacturers involved in these agreements for violations of antitrust law.[32]
Conclusion
In his second term, President-elect Trump is likely to target California’s authority to regulate mobile source emissions, and especially GHG emissions. Lessons from the first Trump Administration indicate that CARB may respond by taking an aggressive position on retroactive enforcement to induce manufacturers to comply with California regulations during any waiver revocation period. The question of CARB’s authority to retroactively enforce mobile source emissions regulations, and the related due process concerns, has not been decided by a court or squarely addressed in litigation.
Meanwhile, even if EPA’s enforcement program shifts Title I enforcement to the states, Title II mobile source emissions enforcement will remain a federal concern. In particular, mobile source criteria pollutant cases, and especially those targeting foreign manufacturers, are likely to continue to remain part of OECA’s docket throughout President-elect Trump’s second administration.
[1] See The Safer Affordable Fuel-Efficient (“SAFE”) Vehicles Rule for Model Years 2021-2026 Passenger Cars and Light Trucks, 83 Fed. Reg. 42986 (proposed Aug. 24, 2018).
[2] See The Safer Affordable Fuel-Efficient (“SAFE”) Vehicles Rule for Model Years 2021-2026 Passenger Cars and Light Trucks, 85 Fed. Reg. 24174 (Apr. 30, 2020). Under the direction of the Biden Administration, in March 2022, EPA instituted stricter GHG standards for model years 2023 through 2026. Revised 2023 and Later Model Year Light-Duty Vehicle Greenhouse Gas Emissions Standards, 86 Fed. Reg. 74434 (Dec. 30. 2021). In April 2024, the Biden EPA promulgated model year 2027 through 2032 light- and medium-duty vehicle emissions standards, including GHG standards. Multi-Pollutant Emissions Standards for Model Years 2027 and Later Light-Duty and Medium-Duty Vehicles, 89 Fed. Reg. 27842 (Apr. 18, 2024). Currently, no major federal rules are pending for non-road engines or vehicles, or other Title II sources.
[3] BrieAnna J. Frank, Project 2025 is an effort by the Heritage Foundation, not Donald Trump | Fact check, USA TODAY (July 10, 2024, 12:05 PM ET), https://www.usatoday.com/story/news/factcheck/2024/07/10/trump-project-2025-heritage-foundation-fact-check/74340278007/.
[4] See Mandy M Gunasekara, Environmental Protection Agency, in Project 2025: Presidential Transition Project, 417, 426 (Paul Dans and Steven Groves, eds., 2023), static.project2025.org/2025_MandateForLeadership_CHAPTER-13.pdf.
[5] Id.
[6] See Ryan Hanrahan, Trump Vows to ‘End the Electric Vehicle Mandate’ in GOP Acceptance Speech, Farm Policy News (July 22, 2024), https://farmpolicynews.illinois.edu/2024/07/trump-vows-to-end-the-electric-vehicle-mandate-in-gop-acceptance-speech/.
[7] See Diana Furchtgott-Roth, Project 2025 Chapter 19 Department of Transportation 627 (2024), static.project2025.org/2025_MandateForLeadership_CHAPTER-19.pdf.
[8] See id.
[9] See 42 U.S.C. § 7543.
[10] 42 U.S.C. §§ 7543(b), (e). Clean Air Act Section 209(b), 42 U.S.C. § 7543(b), pertains to preemption waivers for on-road vehicles and engines. Under Section 209(e), 42 U.S.C. § 7543(e), EPA may issue authorization for California to adopt and enforce its own non-road vehicle or engine emission standards.
[11] See Gunasekara, supra note 3.
[12] Alexandra Ulmer and David Shepardson, Trump says no state would be allowed to ban gasoline-powered cars if he is elected, Reuters (Oct. 4, 2024), https://www.reuters.com/business/autos-transportation/trump-says-no-state-would-be-allowed-ban-gas-powered-cars-if-he-is-elected-2024-10-03/.
[13] See The Safer Affordable Fuel-Efficient (“SAFE”) Vehicles Rule for Model Years 2021-2026 Passenger Cars and Light Trucks, 83 Fed. Reg. at 42999.
[14] See The Safer Affordable Fuel-Efficient Vehicles Rule Part One: One National Program, 84 Fed. Reg. 51310, 51337 (Sept. 27, 2019).
[15] See In re Air Resources Board, OAL Matter No. 2018-1114-03, Cal. Office of Admin. Law, (Dec. 12, 2018), https://www.arb.ca.gov/regact/2018/leviii2018/form400dtc.pdf.
[16] See Letter from Mary D. Nichols, Chairman, CARB, to U.S. EPA and U.S. Dep’t of Transp. (July 28, 2011), https://www.epa.gov/sites/default/files/2016-10/documents/carb-commitment-ltr.pdf (“California commits to propose to revise its standards on GHG emissions from new motor vehicles for model-years MYs 2017 through 2025, such that compliance with the GHG emissions standards adopted by EPA for those model years that are substantially as described in the July 2011 Notice of Intent, even if amended after 2012, shall be deemed compliance with the California GHG emissions standards . . . .”).
[17] Press Release, CARB, California and major automakers reach groundbreaking framework agreement on clean emission standards (July 25, 2019), https://ww2.arb.ca.gov/news/california-and-major-automakers-reach-groundbreaking-framework-agreement-clean-emission. Later, CARB also agreed to allow an additional OEM to enter into a Framework Agreement. See CARB, Framework Agreements on Clean Cars, https://ww2.arb.ca.gov/resources/documents/ framework-agreements-clean-cars (last visited Nov. 11, 2024).
[18] The Safer Affordable Fuel-Efficient Vehicles Rule Part One: One National Program, 84 Fed. Reg at 51329 n.211. In contemporaneous public statements, CARB explained that they offered the Framework Agreements to manufacturers that “support[ed] . . . California’s authority to set vehicle emissions standards” after EPA had indicated its intent to revoke CARB’s Section 209(b) waiver. Media Advisory, CARB, Mary Nichols to Explain Why CARB Is Not Attending the 2019 Los Angeles Auto Show (Nov. 20, 2019), https://ww2.arb.ca.gov/news/media-advisory-mary-nichols-explain-why-california-air-resources-board-not-attending-2019-los. The Framework Agreements were finalized in August 2020 after the revocation of California’s waiver under Section 209(b) of the Clean Air Act to regulate GHG emissions.
[19] See Letter from CARB Regarding Revised 2023 and Later Model Year Light-Duty Vehicle Greenhouse Gas Emissions Standards, Docket ID No. EPA-HQ-OAR-2021-020, to Michael Regan, EPA Administrator, at 9 (Sept. 27, 2021), https://ww2.arb.ca.gov/sites/default/files/2021-10/2021-9-27-final-carb-my-2023-26-usepa-ghg-stds-ccessible.pdf; see also Union of Concerned Scientists v. Nat’l Highway Traffic Safety Admin., No. 19-1230, consolidated with Nos. 19-1239, 1241, 1242, 1243, 1243, 1246, 1249, 1174, and 1178, (D.C. Cir., filed Dec. 26, 2019).
[20] California State Motor Vehicle Pollution Control Standards, 87 Fed. Reg. 14332 (Notice of Decision, Mar. 14, 2022).
[21] See, e.g., Toyota Motors North America, Comment Letter on California State Motor Vehicle Pollution Control Standards; Advanced Clean Car Program; Reconsideration of a Previous Withdrawal of a Waiver of Preemption, Docket No. EPA-HQ-OAR-2021-0257(July 6, 2021 at 4–5) (raising concerns of retroactive enforcement in public comments to EPA’s proposed reconsideration of California’s waiver).
[22] See Opportunity for Public Hearing and Public Comment; California State Motor Vehicle Pollution Control Standards, 89 Fed. Reg. 57151 (Jul. 12, 2024).
[23] CARB, Advanced Clean Fleets Regulation, Enforcement Notice (Dec. 28, 2023) https://ww2.arb.ca.gov/sites/default/files/2023-12/231228acfnotice_ADA.pdf.
[24] Truck and Engine Manufacturers Association, Comment Letter on California State Motor Vehicle Pollution Control Standards; Advanced Clean Fleets Regulation; Request for Waiver of Preemption and Authorization; Opportunity for Public Hearing and Comment, EPA-HQ-OAR-2023-0589 (Sept. 12, 2024) (“. . . to apply the waiver retroactively violates both the CAA and basic principles of due process. The Due Process Clause of the U.S. Constitution requires a government to provide individuals with “an opportunity (1) to know what the law is and (2) to conform their conduct accordingly. Landgraf v. USI Film Prods., 511 U.S. 244, 265 (1994). Retroactive laws contravene “the bedrock due process principle that the people should have fair notice of what conduct is prohibited.” PHH Corp. v. CFPB, 839 F.3d 1, 46 (D.C. Cir. 2016), reinstated in relevant part, 881 F.3d 75, 83 (D.C. Cir. 2018) (en banc). . . . Accordingly, applying CARB’s regulations retroactively would undermine due process generally and as specifically incorporated into the CAA’s preemption waiver provisions. As a result, it is clear that California has no authority to apply its mobile source standards until after a waiver is granted.”).
[25] CARB, Advanced Clean Fleets Regulation, Enforcement Notice (Dec. 28, 2023, updated Oct. 25, 2024) https://ww2.arb.ca.gov/sites/default/files/2024-10/241025acfnotice_ADA.pdf (stating CARB has “decided to exercise its enforcement discretion” to refrain from enforcement action as to certain aspects of the rule “until U.S. EPA grants a preemption waiver . . . or[]determines a waiver is not necessary.”).
[26] See Ohio v. EPA, 98 F.4th 288, 293 (DC Cir. 2024), petition for cert. filed, No. 24-450 (U.S. Oct. 22, 2024).
[27] Id. at 294.
[28] See Press Release, Office of Governor Gavin Newsom, Governor Newsom convenes a special session of the Legislature to protect California values (Nov. 7, 2024), https://www.gov.ca.gov/2024/11/07/special-session-ca-values/ (calling for the California Legislature to allocate additional funding for state agencies “to pursue robust affirmative litigation against any unlawful actions by the incoming Trump Administration, as well as defend against federal lawsuits aimed at undermining California’s laws and policies.”).
[29] See Blanca Begert and Alex Nieves, It’s Already Trump’s World. California Is Just Living In It., Politico (Oct. 15, 2024 5:00 AM EDT), https://www.politico.com/news/2024/10/15/trump-california-environment-supreme-court-00183585.
[30] Loper Bright Enterprises v. Raimondo, 603 U.S. ___, 144 S. Ct. 2244 (2024).
[31] Press Release, CARB, CARB and truck and engine manufacturers announce unprecedented partnership to meet clean air goals (July 6, 2023), https://ww2.arb.ca.gov/news/carb-and-truck-and-engine-manufacturers-announce-unprecedented-partnership-meet-clean-air.
[32] See, e.g., Timothy Puko and Ben Foldy, Justice Department Launches Antitrust Probe Into Four Auto Makers” Wall St. J. (Sept. 6, 2019, 5:55 PM ET), https://www.wsj.com/articles/justice-department-launches-antitrust-probe-into-four-auto-makers-11567778958.
The following Gibson Dunn lawyers prepared this update: Stacie Fletcher, Rachel Levick, and Veronica J.T. Goodson.
Gibson Dunn’s lawyers are available to assist in addressing any questions you may have regarding these developments. To learn more about these issues, please contact the Gibson Dunn lawyer with whom you usually work, the authors, or any leader or member of the firm’s Environmental Litigation and Mass Tort practice group:
Environmental Litigation and Mass Tort:
Stacie B. Fletcher – Washington, D.C.
(+1 202.887.3627, sfletcher@gibsondunn.com)
Rachel Levick – Washington, D.C.
(+1 202.887.3574, rlevick@gibsondunn.com)
Raymond B. Ludwiszewski – Washington, D.C.
(+1 202-955-8665, rludwiszewski@gibsondunn.com)
Veronica J.T. Goodson – Washington, D.C.
(+1 202.887.3719, vgoodson@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
The Final Rule brings the standard for determining when a person has “identified” an overpayment in line with the FCA’s knowledge standard and formalizes a six-month good-faith investigation period—but risks for providers remain.
Introduction
On November 1, 2024, the federal Centers for Medicare and Medicaid Services (CMS) issued a Final Rule (the “Final Rule“) regarding the identification, reporting, and return of overpayments by Medicare participants. The Final Rule applies to participants in Medicare Parts A through D––providers, suppliers, managed care organizations, Medicare Advantage organizations, and prescription drug plan sponsors. The Final Rule will be published in the Federal Register on December 9, 2024, and will go into effect on January 1, 2025.
Under the Affordable Care Act (ACA), recipients of federal health care program funds must report and return any overpayments within 60 days of “identifying” them. The Final Rule starts the 60-day clock for return of overpayments when an entity “knowingly receives or retains an overpayment,” replacing a prior standard—rejected in a 2018 court decision—that had started the clock at the point when an entity “should have determined through . . . reasonable diligence” that it received an overpayment. The Final Rule also introduces a 180-day suspension of the 60-day clock to allow for “good-faith” internal investigations into potential overpayments. Prior to the Final Rule, CMS had suggested that “most” such investigations should be completed within 180 days, but did not make that a formal deadline. However, investigations undertaken in good faith can last well over six months, and in finalizing the rule, CMS declined to reconsider the 180-day timeline or allow for extensions. Because the Final Rule also provides that the period for investigating overpayments ends at the latest when the 180-day suspension period ends, entities may face FCA challenges based on claims that investigations lasting longer than 180 days were not conducted in “good faith.”
Background
An “overpayment” occurs when CMS reimburses an entity for health care goods or services in excess of the amount to which the entity is entitled. Under the ACA, an entity must report and return an overpayment 60 days after the date on which the overpayment is “identified.”[1] The ACA does not specify what it means to “identify” an overpayment. An overpayment not returned by the appropriate deadline is considered an “obligation” under the “reverse” provision of the federal False Claims Act (FCA), which prohibits knowing and improper avoidance of an obligation to pay money to the government.[2]
In a series of regulations promulgated in 2014 and 2016, CMS stated that a Medicare participant “identifies” an overpayment when it “has determined, or should have determined through the exercise of reasonable diligence, that [it] has received an overpayment.”[3] This was essentially a negligence standard, and meant that reverse FCA liability could be premised on something less than recklessness, which is the minimum level of scienter the FCA requires. For several years, the CMS regulations remained intact, and in fact met with deference by some courts—most notably in the case of Kane ex rel. United States v. Healthfirst, Inc., 120 F. Supp. 3d 370 (S.D.N.Y. 2015). There, in analyzing reverse FCA allegations regarding Medicaid overpayments, the court credited CMS’s definition of “identified” in the Medicare context.[4]
Change came in UnitedHealthcare Ins. Co. v. Azar, which struck down the “reasonable diligence” standard.[5] The district court there held that the standard impermissibly created potential FCA liability based on mere negligence as to an obligation to return an overpayment, when the FCA itself requires at least reckless disregard.[6] In response to the UnitedHealthcare decision, CMS proposed a rule in late 2022 that—for the entire Medicare program—defined “identified” by reference to the relatively more stringent definition of “knowing” and “knowingly” contained in the FCA itself.[7]
Both the UnitedHealthcare decision and the 2022 Proposed Rule, however, left a key question unanswered, namely: how can providers avoid being charged with “knowledge” of an overpayment—within the meaning of the FCA—if they take longer than 60 days to conduct a good-faith investigation to determine whether overpayments have occurred? Particularly in large organizations with high volumes of claims, the running of that clock without any action to return monies to the government is very often a sign that a good-faith investigation into potential overpayments remains underway, not that overpayments were quickly identified and are being concealed or disregarded.
While the Final Rule provides a measure of clarity, it ultimately does not answer this question—and in fact, it creates new risks for providers facing potential FCA challenges.
Changes Effectuated by the Final Rule
At the most basic level, the Final Rule codifies the UnitedHealthcare court’s holding by providing that the 60-day clock for repayments begins when an entity “knowingly receives or retains an overpayment,” and explicitly incorporates the FCA’s definition of the word “knowingly.”[8]
The Final Rule also introduces a new provision ostensibly aimed at affording Medicare participants time to conduct internal investigations into potential overpayments. In 2015, CMS acknowledged that such investigations could take around 180 days, but prior to now the agency had not implemented either a requirement that such investigations be completed in that timeframe or an explicit provision tolling the deadline for return of overpayments pending such investigations.[9] The Final Rule, dovetailing off of CMS’s observation in 2015, provides for a maximum 180-day suspension of the 60-day clock to allow providers to conduct internal investigations.[10] In particular, the 180-day suspension applies if a provider has identified at least one overpayment and conducts a “good-faith investigation to determine the existence of related overpayments.”[11]
While the 180-day period seems aimed at providing greater clarity around CMS’s expectations for the timeline for investigating potential overpayments, a six-month investigation period is likely to prove a poor fit for many Medicare participants. Smaller providers facing relatively straightforward overpayment issues may have little trouble completing investigations in 180 days. But larger institutions such as hospitals—for which potential overpayments could span multiple providers and disease states and involve a variety of personnel over long periods of time—are likely to face significant challenges investigating and calculating potential overpayments on a six-month timeframe. Such investigations require time not only by compliance personnel but also by caregivers themselves, who are expected to provide information to aid in the investigation while juggling the non-stop realities of patient care and the operation of the enterprise itself. Even a fast-moving investigation in this sort of setting could easily take more than six months to yield conclusions.
That much could perhaps be addressed by a longer investigation period, at least for large institutional providers. But the Final Rule exacerbates the challenges for such providers by providing that the investigation period closes either when the aggregate overpayments have been identified and calculated or when 180 days have passed.[12] Because the Final Rule states that only a “good-faith” investigation will trigger the 180-day suspension period, the rule creates a risk that the government—or FCA relators—will argue that any investigation longer than 180 days was not conducted in “good faith,” and thus that any provider that does not return putative overpayments within 60 days after the expiration of the 180-day window has acted “knowingly” and faces reverse FCA liability for that reason. As the previous CMS guidance did, the Final Rule leaves open what types of information or scenarios would trigger an obligation to investigate short of having “actual knowledge” of the potential overpayment.
The comments CMS received on the Proposed Rule pointed to the challenges of completing an investigation of potential overpayments within six months. CMS acknowledged that they “heard from many commentators on the issue of time needed for investigations and calculations of overpayments,” and that some comments proposed that the rule include a process to extend the 180-day period for complex investigations, or include an 8-month investigation suspension.[13] Nonetheless, CMS stated that general support for codification of an investigatory period led them to believe that they had “appropriately balanced the needs of providers and suppliers with the required statutory mandates.”[14] It remains to be seen whether or not courts agree with that assertion—particularly in the wake of the Supreme Court’s Loper Bright decision, which empowers federal courts to independently evaluate, rather than defer to, federal agencies’ interpretations of the statutes they implement.[15] For now, Medicare participants undertaking complex overpayment investigations may be faced with a difficult choice in some cases: investigate for longer than 180 days and risk an accusation of “bad faith,” or somehow make a repayment to the payor before the potential overpayment is confirmed and/or quantified. The dilemma appears designed to force on providers a commitment of resources to quickly investigate potential overpayments that may not be available in all cases. Among other questions about how the Final Rule will be implemented, it remains to be seen whether CMS, Medicare Administrative Contractors, and/or potential FCA enforcers will be willing to consider a provider’s facts and circumstances in cases where investigative deadlines cannot be met. Additionally, while this Final Rule is specific to Medicare, FCA cases in other regulatory contexts regularly present the question of the appropriate timeline for internal investigations to identify potential overpayments. It remains to be seen whether the 180-day suspension period and the “good faith” requirement—and the risks they pose—have broader implications for defendants facing FCA investigations and litigation outside the health care arena.
Gibson Dunn will continue to monitor developments related to the Final Rule. And, of course, we would be happy to discuss these developments—and their implications for your business—with you.
[1] 42 U.S.C. § 1320-7k(d).
[2] Id.; 31 U.S.C. § 3729(a)(1)(g).
[3] See, e.g., 42 C.F.R. § 422.326(c) (Medicare Advantage rule); 42 C.F.R. § 401.305(a)(2) (Part A and B rule), 42 C.F.R. § 423.360(c) (Part D rule).
[4] 120 F. Supp. 3d at 383-93.
[5] 330 F. Supp. 3d 173 (D.D.C. 2018), rev’d on other grounds sub nom. UnitedHealthcare Ins. Co. v. Becerra, 16 F.4th 867 (D.C. Cir. 2021).
[6] UnitedHealthcare Ins. Co. v. Azar, 330 F. Supp. 3d at 191.
[7] Contract Year 2024 Medicare Parts A, B, C, and D Overpayment Provisions, 87 Fed. Reg. 79452, 79559 (Dec. 27, 2022).
[8] Dep’t of Health & Hum. Servs., Centers for Medicare & Medicaid Servs., RIN 0938-AV33 and 0938-AU96, at 2446 (emphasis added).
[9] Medicare Program; Contract Year 2015 Policy and Technical Changes to the Medicare Advantage and the Medicare Prescription Drug Benefit Programs, 79 Fed. Reg. 29,844, 29,923 (May 23, 2014).
[10] Dep’t of Health & Hum. Servs., Centers for Medicare & Medicaid Servs., RIN 0938-AV33 and 0938-AU96, at 2447.
[11] Id.
[12] Id.
[13] Id. at 1871-72.
[14] Id. at 1871.
[15] Loper Bright Enterprises v. Raimondo, 144 S. Ct. 2244, 2273 (2024).
Gibson Dunn lawyers regularly counsel clients on the False Claims Act issues and are available to assist in addressing any questions you may have regarding these issues. Please contact the Gibson Dunn lawyer with whom you usually work, the authors, or any leader or member of the firm’s False Claims Act/Qui Tam Defense practice group:
Washington, D.C.
Jonathan M. Phillips – Co-Chair (+1 202.887.3546, jphillips@gibsondunn.com)
Stuart F. Delery (+1 202.955.8515,sdelery@gibsondunn.com)
F. Joseph Warin (+1 202.887.3609, fwarin@gibsondunn.com)
Gustav W. Eyler (+1 202.955.8610, geyler@gibsondunn.com)
Lindsay M. Paulin (+1 202.887.3701, lpaulin@gibsondunn.com)
Geoffrey M. Sigler (+1 202.887.3752, gsigler@gibsondunn.com)
Joseph D. West (+1 202.955.8658, jwest@gibsondunn.com)
San Francisco
Winston Y. Chan – Co-Chair (+1 415.393.8362, wchan@gibsondunn.com)
Charles J. Stevens (+1 415.393.8391, cstevens@gibsondunn.com)
New York
Reed Brodsky (+1 212.351.5334, rbrodsky@gibsondunn.com)
Mylan Denerstein (+1 212.351.3850, mdenerstein@gibsondunn.com)
Denver
John D.W. Partridge (+1 303.298.5931, jpartridge@gibsondunn.com)
Ryan T. Bergsieker (+1 303.298.5774, rbergsieker@gibsondunn.com)
Robert C. Blume (+1 303.298.5758, rblume@gibsondunn.com)
Monica K. Loseman (+1 303.298.5784, mloseman@gibsondunn.com)
Dallas
Andrew LeGrand (+1 214.698.3405, alegrand@gibsondunn.com)
Los Angeles
James L. Zelenay Jr. (+1 213.229.7449, jzelenay@gibsondunn.com)
Nicola T. Hanna (+1 213.229.7269, nhanna@gibsondunn.com)
Jeremy S. Smith (+1 213.229.7973, jssmith@gibsondunn.com)
Deborah L. Stein (+1 213.229.7164, dstein@gibsondunn.com)
Dhananjay S. Manthripragada (+1 213.229.7366, dmanthripragada@gibsondunn.com)
Palo Alto
Benjamin Wagner (+1 650.849.5395, bwagner@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
From the Derivatives Practice Group: The CFTC Global Markets Advisory Committee will hold a virtual meeting on November 21 to discuss expanding the use of non-cash collateral through the use of distributed ledger technology.
New Developments
- CFTC Warns of Potential Dangers for Messaging App Users. On October 31, the CFTC Office of Customer Education and Outreach released a customer advisory alerting messaging app users to beware of schemes to defraud them of assets, specifically crypto assets. Fraudsters are exploiting the default settings of commonly used messaging apps, telephone networks, and mobile devices to lure users into crypto pump-and-dump schemes and other scams. [NEW]
- Commissioner Pham Announces CFTC Global Markets Advisory Committee Meeting on November 21. CFTC Commissioner Caroline D. Pham, sponsor of the Global Markets Advisory Committee (“GMAC”), announced the GMAC will hold a virtual public meeting Thursday, Nov. 21, from 9:30 a.m. to 10:30 a.m. EST. At this meeting, the GMAC will hear a presentation by the Tokenized Collateral workstream of the GMAC’s Digital Asset Markets Subcommittee on expanding use of non-cash collateral through use of distributed ledger technology and consider a recommendation from the Subcommittee. The meeting will also include a presentation by the Utility Tokens workstream of the Digital Asset Markets Subcommittee summarizing their work to-date on defining utility tokens and developing guidance for market participants. [NEW]
- SEC Adopts Rule Amendments and New Rule to Improve Risk Management and Resilience of Covered Clearing Agencies. On October 25, the SEC adopted rule amendments and a new rule to improve the resilience and recovery and wind-down planning of covered clearing agencies. The rule amendments establish new requirements regarding a covered clearing agency’s collection of intraday margin as well as a covered clearing agency’s reliance on substantive inputs to its risk-based margin model. The new rule prescribes requirements for the contents of a covered clearing agency’s recovery and wind-down plan. The rule amendments require that a covered clearing agency that provides central counterparty services has policies and procedures to establish a risk-based margin system that monitors intraday exposures on an ongoing basis, includes the authority and operational capacity to make intraday margin calls as frequently as circumstances warrant (including when risk thresholds specified by the covered clearing agency are breached or when the products cleared or markets served display elevated volatility), and documents when the covered clearing agency determines not to make an intraday call pursuant to its written policies and procedures. [NEW]
- SEC Division of Examinations Announces 2025 Priorities. On October 21, the SEC’s Division of Examinations released its 2025 examination priorities. The Division of Examinations indicated that it will continue to focus on whether security-based swap dealers (“SBSDs”) have implemented policies and procedures related to compliance with security-based swap rules generally, including whether they are meeting their obligations under Regulation SBSR to accurately report security-based swap transactions to security-based swap data repositories and, where applicable, whether they are complying with relevant conditions in SEC orders governing substituted compliance. For other SBSDs, the Division of Examinations said that it may focus on SBSDs’ practices with respect to applicable capital, margin, and segregation requirements and risk management. The Division of Examinations also indicated that it expects to assess whether SBSDs have taken corrective action to address issues identified in prior examinations. Additionally, the Division of Examinations advised that it may begin conducting examinations of registered security-based swap execution facilities in late fiscal year 2025.
New Developments Outside the U.S.
- ESAs Publish 2024 Joint Report on Principal Adverse Impacts Disclosures Under the Sustainable Finance Disclosure Regulation. On October 30, the European Supervisory Authorities (“ESAs”) published their third annual Report on disclosures of principal adverse impacts under the Sustainable Finance Disclosure Regulation (“SFDR”). The Report assesses both entity and product-level Principal Adverse Impact disclosures under the SFDR. These disclosures aim at showing the negative impact of financial institutions’ investments on the environment and people and the actions taken by asset managers, insurers, investment firms, banks and pension funds to mitigate them. [NEW]
- The ESAs Finalize Rules to Facilitate Access to Financial and Sustainability Information on the ESAP. On October 29, the ESAs published the Final Report on the draft implementing technical standards (“ITS”) regarding certain tasks of the collection bodies and functionalities of the European Single Access Point (“ESAP”). The requirements are designed to enable future users to be able to access and use financial and sustainability information effectively and effortlessly in a centralized ESAP platform. [NEW]
- ESMA Consults on Amendments to MiFID Research Regime. On October 28, ESMA launched a consultation on amendments to the research provisions in the Markets in Financial Instruments II (“MiFID II”) Delegated Directive following changes introduced by the Listing Act. The Listing Act introduces changes that enable joint payments for execution services and research for all issuers, irrespective of the market capitalization of the issuers covered by the research. The Consultation Paper includes proposals to amend Article 13 of the MiFID II Delegated Directive in order to align it with the new payment option offered. [NEW]
- ESMA Responds to the Commission Rejection of Certain MiCA Technical Standards. On October 16, ESMA responded to the European Commission proposal to amend the Markets in crypto-assets Regulation (“MiCA”) Regulatory Technical Standards (“RTS”). In their response, ESMA emphasized the importance of the policy objectives behind the initial proposal.
- ESAs Respond to the European Commission’s Rejection of the Technical Standards on Registers of Information under the Digital Operational Resilience Act and Call for Swift Adoption. On October 15, the ESAs issued an Opinion on the European Commission’s rejection of the draft ITS on the registers of information under the Digital Operational Resilience Act. The ESAs raise concerns over the impacts and practicalities of the proposed EC changes to the draft ITS on the registers of information in relation to financial entities’ contractual arrangements with ICT third-party service providers.
- ESMA, ECB and EC Announce Next Steps for the Transition to T+1 Governance. On October 15, ESMA, the European Commission and the European Central Bank announced the next steps to support the preparations towards a transition to T+1 in a Joint Statement. ESMA stressed in the Joint Statement that they believe a coordinated approach across Europe is desirable, with efforts to reach consensus on the timing of any move to T+1.
New Industry-Led Developments
- ISDA Letter to FASB on Share-based Payment from a Customer in a Revenue Contract. On October 21, ISDA submitted a response to the Financial Accounting Standards Board (“FASB”) on File Reference No. 2024-ED100, Derivatives Scope Refinements and Scope Clarification for a Share-based Payment from a Customer in a Revenue Contract. ISDA believes the FASB’s proposal will improve the application and relevance of the Derivatives and Hedging (Topic 815) and Revenue from Contracts with Customers (Topic 606) guidance and has provided potential refinements to the guidance in the letter. [NEW]
- Central Database of Reporting Entity Contact Details for EU and UK EMIR. On October 17, ISDA produced a central database of contact details to assist members resolve reconciliation breaks with counterparties for EU and UK European Market Infrastructure Regulation (“EMIR”) reporting. The central database was created by contributing firms’ submissions and includes details such as entity names, legal entity identifiers and reporting contact emails.
- ISDA, GFXD respond to ESMA on Order Execution Policies. On October 16, ISDA and the Global FX Division of the Global Financial Markets Association responded to a consultation paper from ESMA on “Technical Standards specifying the criteria for establishing and assessing the effectiveness of investment firms’ order execution policies.” In the response, the associations discuss the requirement for pre-selected execution venues, mandatory consumption of consolidated tapes and categorization of financial instruments under the Markets in Financial Instruments Regulation, among other issues.
The following Gibson Dunn attorneys assisted in preparing this update: Jeffrey Steiner, Adam Lapidus, Marc Aaron Takagaki, Hayden McGovern, and Karin Thrasher.
Gibson Dunn’s lawyers are available to assist in addressing any questions you may have regarding these developments. Please contact the Gibson Dunn lawyer with whom you usually work, any member of the firm’s Derivatives practice group, or the following practice leaders and authors:
Jeffrey L. Steiner, Washington, D.C. (202.887.3632, jsteiner@gibsondunn.com)
Michael D. Bopp, Washington, D.C. (202.955.8256, mbopp@gibsondunn.com)
Michelle M. Kirschner, London (+44 (0)20 7071.4212, mkirschner@gibsondunn.com)
Darius Mehraban, New York (212.351.2428, dmehraban@gibsondunn.com)
Jason J. Cabral, New York (212.351.6267, jcabral@gibsondunn.com)
Adam Lapidus – New York (212.351.3869, alapidus@gibsondunn.com )
Stephanie L. Brooker, Washington, D.C. (202.887.3502, sbrooker@gibsondunn.com)
William R. Hallatt , Hong Kong (+852 2214 3836, whallatt@gibsondunn.com )
David P. Burns, Washington, D.C. (202.887.3786, dburns@gibsondunn.com)
Marc Aaron Takagaki , New York (212.351.4028, mtakagaki@gibsondunn.com )
Hayden K. McGovern, Dallas (214.698.3142, hmcgovern@gibsondunn.com)
Karin Thrasher, Washington, D.C. (202.887.3712, kthrasher@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
An overview of International Trade considerations that most frequently impact deal timing, valuation, and ability to operate after closing.
In today’s global economy, geopolitical risks are on the rise and international trade controls are a tool of first resort deployed by the United States and other jurisdictions to achieve foreign policy and national security goals. International trade controls include financial and trade sanctions, export and import controls, national security reviews of foreign direct investment, and (anticipated) controls on outbound investment. These controls can have an impact on a target’s valuation, ability to continue operating in the same manner or in the same jurisdictions as prior to an acquisition or affect deal timing and certainty. Liability for a target’s past conduct can be imputed to the buyer in many circumstances, including for strict liability offenses.
In addition to potential civil and criminal liability, violations of international trade laws can result in other adverse consequences for buyers, including substantial reputational harm, costly government investigations or monitorships, or even halting the deal. Many acquisition targets—especially smaller, fast-growing targets—may lack adequate policies and procedures to mitigate the risk of violating applicable international trade laws. Therefore, it is critical to understand a target’s risk profile, internal controls, and potential exposure to regulatory, commercial, and reputational risks during pre-acquisition due diligence.
1. Dealings with Sanctioned Parties and Sanctioned Jurisdictions
Whether a target is transacting business in violation of applicable U.S. sanctions is often a top concern for buyers and insurers alike. Unlike some other areas of the law, corporate formality in the structure of an acquisition will not always insulate a buyer from civil liability for past violations of the target. Rather, in enforcing U.S. sanctions, the Department of the Treasury’s Office of Foreign Assets Control (“OFAC”) is usually willing to “pierce the corporate veil.” Nor will a buyer’s lack of knowledge regarding the target’s past sanctions violations necessarily shield it from liability. Even inadvertent violations of U.S. sanctions can result in substantial monetary penalties, at times in the tens of millions, and occasionally beyond. In April of this year, the statute of limitations for sanctions violations was expanded from 5 to 10 years.
Consequently, it is critical to focus on potential exposure to sanctioned persons or sanctioned jurisdictions during pre-acquisition due diligence. U.S. sanctions requirements can be understood to fall into two broad categories:
- Dealings with sanctioned parties: U.S. sanctions generally prohibit U.S.-linked business involving “blocked” persons or entities listed on OFAC’s List of Specially Designated Nationals and Blocked Persons (the “SDN List“). Pursuant to OFAC’s 50 Percent Rule, these broad prohibitions extend to entities owned 50% or more by blocked persons, whether directly or indirectly and whether by a single blocked person or in the aggregate.
- Dealings with sanctioned jurisdictions: U.S. sanctions generally prohibit U.S.-linked business involving “comprehensively-sanctioned” jurisdictions, which, as of this writing, include Cuba, Iran, Syria, North Korea, Crimea, and the so-called Luhansk People’s Republic and Donetsk People’s Republic regions of Ukraine.
In addition to direct prohibitions on U.S.-nexus dealings, U.S. persons are generally prohibited from “facilitating” foreign transactions that involve a sanctioned party or sanctioned jurisdiction. Consequently, it is essential to ensure that target companies with an international footprint have adequate policies and procedures in place to avoid and detect transactions that may be prohibited by applicable sanctions.
OFAC encourages companies to employ a “risk-based approach” in designing and deploying sanctions compliance programs (see OFAC’s “Framework for Compliance Commitments“). Risk factors include a company’s size and sophistication, products and services, customers and counterparties, and geographic locations. An adequate sanctions compliance program will often include the use of counterparty “screening” tools (which compare counterparty information, including ultimate beneficial owners, against the SDN List and other relevant restricted party lists) as well as procedures for escalating transactions that pose an unacceptable risk of violating applicable sanctions. Screening protocols should be calibrated according to risk profile as well, including use of “fuzzy logic” algorithms. For some targets, reasonable sanctions compliance measures should include Internet Protocol address-based geo-blocking to prevent persons in sanctioned jurisdictions from accessing a company’s online platform or products.
2. Dealings with Russia, Belarus, and Assessing Diversion Risk
Since Russia’s 2022 full-scale invasion of Ukraine, the United States, in coordination with its allies and partners, has imposed a wide range of restrictions on trade with Russia and Belarus. For example, the United States has prohibited new investment in Russia, the importation into the United States of energy products from Russia, and the exportation of any military or dual-use products to Russia. In addition, OFAC has designated thousands of Russian persons and entities, including Russian oligarchs and family members, and imposed severe restrictions on dealings with Russia’s banking, financial, energy, and military-industrial sector. OFAC has prohibited the provision of certain professional services, to persons located in Russia, including accounting, trust and corporate formation, management consulting, quantum computing, architecture, engineering, certain maritime transportation-related services, and IT services, among others. The Department of Commerce’s Bureau of Industry and Security (“BIS”) has imposed stringent export controls targeting Russia and Belarus, which cover a wide range of industrial and commercial items. In some cases, these restrictions extend to products made outside of the United States that depend upon U.S.-origin software, technology, or tools. As such, any business involving Russia and Belarus, directly or indirectly, can pose substantial international trade-related risks—especially if the target maintains a Russian subsidiary or branch office.
U.S. authorities have been particularly focused on diversion risk and efforts by companies to detect and prevent the illicit transfer of goods to restricted destinations via intermediaries and shell companies. More broadly, acquiring a target that is based in a jurisdiction that has not adopted export controls similar to those maintained in G7 states can carry elevated risk of unlawful diversion in violation of applicable sanctions and export controls. While virtually every industry is potentially at risk, the United States and its partners have issued advisories identifying high priority items that Russia is seeking to support its war effort and high-risk industries, for which trade with Russia is severely curtailed. Buyers should be on the lookout for trading patterns of a target that show a substantial shift in trade away from Russia to identified diversion points, or sudden spikes in sales to higher risk jurisdictions.
3. Export Controls
Many targets, including targets that are not traditional “manufacturers” (such as many producers of software), will also carry compliance obligations under export controls set forth in the Export Administration Regulations (“EAR”). Export controls are used by the United States and other nations to restrict the export of items that would contribute to the military potential of adversary countries or to restrict the export of items necessary to further foreign policy objectives and uphold treaty obligations. U.S. export controls have a broad extraterritorial reach, since the obligation to comply with requirements follows U.S. items wherever they are located and, in some instances, extends to foreign-made products that rely upon U.S.-origin technology, software, or tools. Export control requirements can apply based on the technical parameters and performance capabilities of an item or based upon the intended destination, end user, or end use. In some circumstances, the release of technology to a foreign national may require an export license as a “deemed export” to the country of residence of the recipient of the information.
Export control risks are most commonly presented in acquisitions of target companies that produce items with potential defense applications (i.e., “dual-use” items). These targets oftentimes operate in the aerospace, software, connected devices, and specialized and high-tech manufacturing industries. Of special relevance to targets operating in the software and high-tech industries, most encryption technology and software is subject to specialized export controls. Companies operating in these sectors, therefore, must maintain adequate policies and procedures in order to classify and, if applicable, fulfill the reporting requirements set forth in license exception ENC.
Export controls are a fast-developing area of international trade law. For example, on September 6, 2024, BIS published new regulations to control certain advanced and emerging technologies, including quantum computing, semiconductor manufacturing equipment, and additive manufacturing. These regulations represent an early step towards establishing a plurilateral export control regime to eventually replace the Wassenaar Arrangement, the legacy multilateral export control regime that includes Russia. BIS has also signaled its intent to increase penalties and enhance its enforcement efforts, in conjunction with international export control authorities. It is especially likely, therefore, that export controls-related due diligence obligations will expand during 2025.
4. CFIUS Risk
The Committee on Foreign Investment in the United States (“CFIUS“) reviews foreign direct investments in U.S. businesses for national security risks. CFIUS examines certain transactions in which foreign entities gain control or make certain non-controlling investments in U.S. businesses. At the conclusion of its assessment, CFIUS may impose restrictions that address U.S. national security risks arising from those transactions. In 2018, the Foreign Investment Risk Review and Modernization Act expanded the scope of transactions subject to CFIUS review to include (i) certain non-controlling investments in U.S. businesses that implicate critical technology, critical infrastructure, or sensitive personal data of U.S. citizens and (ii) real estate located near sensitive U.S. military installations. CFIUS devotes particular attention to transactions with investors from adverse jurisdictions and transactions that implicate defense and other key supply chains or emerging technologies, such as AI.
The CFIUS review process, which typically begins with the transaction parties filing a mandatory or voluntary notice to CFIUS, can take 4-6 months or longer. Consequently, where an acquisition implicates CFIUS jurisdiction, deal timing should accommodate the time to submit a notification and receive clearance prior to closing. A completed CFIUS review grants “safe harbor,” preventing future scrutiny from CFIUS. Without this safe harbor, CFIUS retains discretion to review and place conditions on transactions after they have been completed. There is no statute of limitations to CFIUS’s ability to review closed transactions. In relatively rare circumstances, CFIUS may also recommend that the President block or unwind a transaction. CFIUS can assess monetary penalties on parties for failure to make a mandatory filing, for making material misstatements or omissions in a filing, or for failure to comply with a national security mitigation agreement.
5. Outbound Investment: “Reverse CFIUS” Risk
It is widely anticipated that the Department of the Treasury will promulgate “reverse CFIUS” outbound investment regulations during the next year. Currently, these regulations are expected to target investments made by U.S. persons in China, Hong Kong, or Macau and involving certain categories of technologies, including the development and production of semiconductors and microelectronics, quantum information technologies, and artificial intelligence systems. Proposed rules would impose recordkeeping and notification requirements on U.S.-person investors. Additionally, certain investments in advanced critical technologies may be prohibited. Diligence obligations during acquisitions will likely mirror those under current CFIUS regulations to identify transactions within the scope of the outbound investment regime.
6. Forced Labor and Importation Concerns
Some targets will present risks under the Uighur Forced Labor Prevention Act (“UFLPA”). The UFLPA presumptively bars from entry into the United States all products that are manufactured in China’s Xinjiang Uyghur Autonomous Region or produced by a list of entities that have been designated by the interagency Forced Labor Enforcement Task Force (“FLETF”), unless the importer can present “clear and convincing” evidence that the product has not been tainted by the use of forced labor. U.S. Customs and Border Protection (“CBP”), which enforces the UFLPA, has been remarkably aggressive in enforcing these provisions. The UFLPA does not contain a de minimis exception, and CBP has barred shipments from entry into the United States where the goods contained under 1% of Xinjiang-origin content by value.
Accordingly, in addition to reviewing the target’s documentation and conducting interviews with management, it may be necessary in some cases to use business intelligence platforms to “screen” targets and their counterparties for risks related to forced labor in the supply chain. Notably, owing to the absence of a de minimis exception, the UFLPA authorizes CBP to detain shipments that are not themselves manufactured in Xinjiang but contain inputs that originate, in whole or in part, in Xinjiang. As such, even targets that depend on imports from third countries, such as Vietnam, may present elevated risk of violating the UFLPA depending on the products involved.
7. Defense Sector Controls
There are unique considerations for targets operating in the defense sector, even if the target only handles defense-related items as a minority of its sales. In particular, the International Traffic in Arms Regulations (“ITAR”) apply to defense articles, defense services, and related technology. The ITAR, like the EAR, “follow the item” and therefore have broad extraterritorial application. Under the ITAR, persons engaged in the business of manufacturing, exporting or temporarily importing defense articles, or furnishing defense services, are required to register with the Department of State’s Directorate of Defense Trade Controls (“DDTC”). When a registered target is acquired, the target and the buyer are required to notify DDTC within five days of the closing. Where a buyer is a non-U.S. person, the buyer and target must submit a notice to DDTC at least 60 days before closing. These requirements apply even if the transaction is an acquisition of assets or a sale in the course of bankruptcy. A transaction that involves an ITAR registrant that occurs in a multi-step process could trigger multiple notifications. In addition to registration, any export licenses that the target holds authorizing it to send defense articles outside of the United States must be requested to transfer to the new parent entity. It is essential that deal timelines accommodate registration, notification, and transfer requirements, as failure to do so could result in a disruption of business activities.
8. Managing Legacy International Trade Issues
If a target company has failed to adhere to relevant international trade controls, post-closing remediation may be necessary, including the possibility of self-disclosure to relevant government agencies. Under enforcement policies of the U.S. Department of Justice’s National Security Division and the U.S. Department of Commerce, the prompt self-disclosure of a target company’s apparent violations of sanctions and export control laws that occurred prior to acquisition may be eligible for significant mitigation credit. Conversely, a target company that has made serial self-disclosures may have systemic compliance issues, which may result in significant penalties for the buyer. In addition, compliance commitments and consent agreement terms may apply to buyers and related entities, even following acquisition.
Our attorneys are leading industry experts, and we regularly advise on international trade matters on behalf of the world’s largest companies. We efficiently identify the costs and resources needed to implement post-acquisition remediation and assist in integrating the international trade practices of target companies into buyers’ global organizations. We also help manage target companies’ pre-existing compliance gaps and provide holistic assessments on the impacts of such events on the transaction or the buyer’s business.
Gibson Dunn’s lawyers are available to assist in addressing any questions you may have regarding these developments. For further information, please contact the Gibson Dunn lawyer with whom you usually work, the authors, or any leader or member of the firm’s Mergers and Acquisitions, Private Equity, or International Trade practice groups:
International Trade:
Adam M. Smith – Washington, D.C. (+1 202.887.3547, asmith@gibsondunn.com)
Stephenie Gosnell Handler – Washington, D.C. (+1 202.955.8510, shandler@gibsondunn.com)
Christopher T. Timura – Washington, D.C. (+1 202.887.3690, ctimura@gibsondunn.com)
Samantha Sewall – Washington, D.C. (+1 202.887.3509, ssewall@gibsondunn.com)
Michelle A. Weinbaum – Washington, D.C. (+1 202.955.8274, mweinbaum@gibsondunn.com)
Mergers and Acquisitions:
Robert B. Little – Dallas (+1 214.698.3260, rlittle@gibsondunn.com)
Saee Muzumdar – New York (+1 212.351.3966, smuzumdar@gibsondunn.com)
George Sampas – New York (+1 212.351.6300, gsampas@gibsondunn.com)
Private Equity:
Richard J. Birns – New York (+1 212.351.4032, rbirns@gibsondunn.com)
Ari Lanin – Los Angeles (+1 310.552.8581, alanin@gibsondunn.com)
Michael Piazza – Houston (+1 346.718.6670, mpiazza@gibsondunn.com)
John M. Pollack – New York (+1 212.351.3903, jpollack@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
From the Derivatives Practice Group: On October 2, the U.S. Court of Appeals for the D.C. Circuit upheld the order that permits KalshiEX LLC to list contracts that allow Americans to bet on election outcomes.
New Developments
- US Appeals Court Clears Kalshi to Restart Elections Betting. On October 2, the U.S. Court of Appeals for the D.C. Circuit upheld the D.C. District Court’s order that permitted derivatives trading platform KalshiEX LLC to list contracts that allow Americans to bet on election outcomes. The Court said that the CFTC did not show how the agency or the public interest would be harmed by the “event” contracts. The CFTC’s motion was denied “without prejudice to renewal should more concrete evidence of irreparable harm develop during the pendency of appeal.” [NEW]
- CFTC’s Division of Clearing and Risk Announces Staff Roundtable Discussion on New and Emerging Issues in Clearing. On September 27, the CFTC announced that the Division of Clearing and Risk will hold a public roundtable on October 16, to discuss existing, new, and emerging issues in clearing. The roundtable will be held in the Conference Center at CFTC’s headquarters at Three Lafayette Centre, 1155 21st Street N.W., Washington, D.C. The roundtable will include participants from derivatives clearing organizations, futures commission merchants (“FCM”), FCM customers, end-users, custodians, proprietary traders, public interest groups, state regulators, and others. The goal of the roundtable is to gather information and receive expert input from a wide variety of stakeholder groups. Topics to be covered include the custody and delivery of digital assets, digital assets and margin, full collateralization, 24/7 trading, non-intermediated clearing with margin, and conflicts of interest related to vertically integrated entities. [NEW]
- CFTC Requests Public Comment on a Rule Certification Filing by KalshiEX LLC. On September 26, the CFTC requested public comment on a rule certification filing by KalshiEX LLC, which would amend its rulebook to include rules for a request for quote functionality and amendments to its prohibited transactions rule. The CFTC previously stayed KalshiEX LLC’s filing because, according to the CFTC, the submission presents novel or complex issues that require additional time to analyze and is potentially inconsistent with the Commodity Exchange Act or the CFTC’s regulations. Comments must be submitted on or before October 28, 2024.
- CFTC Staff Extends No-Action Position for Certain Reporting Obligations Under the Ownership and Control Reports Final Rule. On September 25, the CFTC’s Division of Market Oversight (“DMO”) issued a no-action letter that extends the current no-action position for reporting obligations under the ownership and control reports final rule (“OCR Final Rule”). The OCR Final Rule, approved in 2013, requires the electronic submission of trader identification and market participant data for special accounts and volume threshold accounts through Form 102 and Form 40. DMO said that it is extending its no-action position to address continuing compliance difficulties associated with certain ownership and control reporting obligations identified by reporting parties and market participants. The position extends DMO’s position under CFTC Letter No. 23-14, stating that DMO will not recommend the CFTC commence an enforcement action for non-compliance with certain obligations. These obligations include, among others, the timing of ownership and control report form filings; certain information required to be reported regarding trading account controllers and volume threshold account controllers on Form 102; the reporting threshold that triggers the reporting of a volume threshold account on Form 102; the filing of refresh updates for Form 102; and responses to certain questions on Form 40. The no-action position will remain in effect until the later of the applicable effective date or compliance date of a CFTC action, such as a rulemaking or order, addressing such obligations.
- CFTC Announces Four Orders Granting Whistleblower Awards – Marking the Most in a Single Day. On September 23, the CFTC announced awards totaling approximately $4.5 million for whistleblowers who, collectively, provided information that led to the success of multiple enforcement actions brought by the CFTC and another authority. The four orders granting awards, to a total of seven whistleblowers, are the most the CFTC has issued on a single day.
- CFTC Staff Extends Temporary No-Action Letter Regarding Capital and Financial Reporting for Certain Non-U.S. Nonbank Swap Dealers Domiciled in the EU and the UK. On September 20, the CFTC’s Market Participants Division (“MPD”) announced it issued a temporary no-action letter extending CFTC Staff Letters No. 21-20 and 22-10 to certain nonbank swap dealers (“SDs”) domiciled in the EU and the UK that are the subject of pending CFTC reviews for comparability determinations regarding capital and financial reporting requirements. As part of the capital and financial reporting requirements for nonbank SDs, the CFTC adopted a substituted compliance framework that permits certain nonbank SDs to rely on compliance with home-country capital and financial reporting requirements in lieu of meeting all or parts of the CFTC’s capital adequacy and financial reporting requirements, provided the CFTC finds the home-country requirements comparable to the CFTC’s requirements. Through CFTC Staff Letter No. 24-13, issued on September 20, MPD is extending a no-action position to eligible nonbank SDs domiciled in the EU and the UK that are not covered by existing CFTC orders addressing capital and financial reporting requirements. The no-action position is conditioned upon the nonbank SDs remaining in compliance with applicable home-country capital and financial reporting requirements and submitting certain financial reporting information to the CFTC. The no-action position will expire by December 31, 2026 or the effective date of any final CFTC action addressing the comparability of capital and financial reporting requirements applicable to the relevant nonbank SDs.
- CFTC Approves Final Guidance Regarding the Listing of Voluntary Carbon Credit Derivative Contracts. On September 20, the CFTC approved final guidance regarding the listing for trading of voluntary carbon credit derivative contracts. The guidance applies to designated contract markets (“DCMs”), which are CFTC-regulated derivatives exchanges, and outlines factors for DCMs to consider when addressing certain Core Principle requirements in the Commodity Exchange Act and CFTC regulations that are relevant to the listing for trading of voluntary carbon credit derivative contracts. The guidance also outlines factors for consideration when addressing certain requirements under the CFTC’s Part 40 Regulations that relate to the submission of new derivative contracts, and contract amendments to the CFTC.
New Developments Outside the U.S.
- ESMA Launches New Consultations Under the MiFIR Review. On October 3, ESMA launched two consultations on transaction reporting and order book data under the Markets in Financial Instruments Regulation (“MiFIR”) Review. ESMA is seeking input on the amendments to the regulatory technical standards (“RTS”) for the reporting of transactions and to the RTS for the maintenance of data relating to orders in financial instruments. [NEW]
- Joint UK Regulators Issue Press Release on the End of LIBOR. On October 1, the Bank of England published a joint press release with the FCA and the Working Group on Sterling Risk-Free Reference Rates on the end of LIBOR. On September 30, the remaining synthetic LIBOR settings were published for the last time and LIBOR came to an end. All 35 LIBOR settings have now permanently ceased. The Working Group has met its objective of finalizing the transition away from LIBOR and will be wound down effective as of October 1. Market participants are encouraged to continue to ensure they use the most robust rates for the relevant currency and should ensure their use of term risk-free reference rates are limited and remain consistent with the relevant guidance on best practice on the scope of use. [NEW]
- ESAs Appoint Director to Lead their DORA Joint Oversight. On October 1, the European Supervisory Authorities appointed Marc Andries to lead their new joint Directorate in charge of oversight activities for critical third-party providers established by the Digital Operational Resilience Act (“DORA”). In his role as DORA Joint Oversight Director, Marc Andries will be responsible for implementing and running an oversight framework for critical third-party service providers at a pan-European scale, contributing to the smooth operations and stability of the EU financial sector. [NEW]
- ESMA 2025 Work Programme: Focus on Key Strategic Priorities and Implementation of New Mandates. On October 1, ESMA published its 2025 Annual Work Programme (AWP). A significant portion of ESMA’s work in 2025 will comprise policy work to facilitate the implementation of the large number of mandates received in the previous legislative cycle, and the preparation of new mandates, such as the European Green Bonds and the ESG Rating Providers Regulations. [NEW]
- ESMA Announces Next Steps for the Selection of Consolidated Tape Providers. On September 30, ESMA announced it will launch the selection procedure for Consolidated Tapes Providers (“CTPs”) bonds on January 3, 2025. In June 2025, ESMA will launch the selection procedure for the CTP for shares and Exchange-Traded Funds with the objective to adopt a reasoned decision on the selected applicant by the end of 2025. [NEW]
- SFC and HKMA Publish Conclusions on Enhancements to OTC Derivatives Reporting Regime for Hong Kong. On September 26, the Securities and Futures Commission and the Hong Kong Monetary Authority jointly published conclusions on proposed enhancements to the over-the-counter (“OTC”) derivatives reporting regime for Hong Kong, indicating that they will mandate (i) the use of unique transaction identifiers, (ii) the use of unique product identifiers and (iii) the reporting of critical data elements beginning on September 29, 2025.
New Industry-Led Developments
- ISDA Responds to UK FCA Consultation on DTO and PTRRS. On September 30, ISDA responded to Financial Conduct Authority (“FCA”) consultation CP24/14 on the derivatives trading obligation (“DTO”) and post-trade risk reduction services (“PTRRS”). In the response, ISDA highlights its support for including certain overnight index swaps based on the US Secured Overnight Financing Rate within the classes of derivatives subject to the DTO and expanding the list of PTRRS exempted from the DTO and other obligations. [NEW]
- ISDA Publishes Results of Survey on AT1 Treatment in DRM Model. On September 27, ISDA published a survey of its members on the development of the dynamic risk management (“DRM”) model. The survey sought to understand the accounting and regulatory treatment of Alternative Tier 1 (“AT1”) financial instruments and to contribute this information to the development of the International Accounting Standards Board’s DRM model. The survey shows that for balance sheet classification under International Financial Reporting Standards, the majority of respondents classify their AT1s as equity; the majority of respondents include their AT1s for interest rate risk in the banking book (“IRRBB”) as equivalent to financial liabilities; and there is strong desire for the inclusion of AT1s in the current net open position. [NEW]
- ISDA Publishes Updated Best Practices for Confirming Reference Obligations or Standard Reference Obligations. On September 25, ISDA published updated Best Practices for Single-name Credit Default Swaps regarding Reference Obligations or Standard Reference Obligations. The document sets out suggested best practices for confirming the Reference Obligation or Standard Reference Obligations for single-name Credit Default Swaps and is an update to the Best Practice Statement that was published by ISDA on November 18, 2014.
- Joint Trade Association Issues Statement on EMIR 3.0 Effective Implementation Dates. On September 23, ISDA, the Alternative Investment Management Association, the European Banking Federation, the European Fund and Asset Management Association and FIA sent a letter urging the European Commission and European supervisory authorities to clarify that market participants are not required to implement the European Market Infrastructure Regulation (“EMIR 3.0”) Level 1 provisions prior to the date of application of the associated Level 2 regulatory technical standards (“RTS”). In the letter, the associations state that they are seeking clarification to avoid firms being required to implement the requirements of EMIR 3.0 twice—first, to comply with the Level 1 provisions once EMIR 3.0 enters into force and then when the associated Level 2 RTS becomes applicable.
- ISDA Publishes Standing Settlement Instructions Suggested Operational Practices. On September 20, ISDA published the ISDA Standing Settlement Instructions (“SSI”) suggested operational practices (“SOP”), which outlines a set of guidelines for the communication, management and usage of SSIs. According to ISDA, the document aims at increasing standardization and efficiency in performing payments for over-the-counter (“OTC”) derivatives and it is an update to the Best Practice Statement that was published by ISDA on August 11, 2010. SOPs for the exchange of SSIs for the purposes of collateral are available in section 1.7 of the Suggested Operational Practices for the OTC Derivatives Collateral Process.
- ISDA Publishes Results of DC Review Consultation. On September 19, ISDA published the results of a market-wide consultation on proposed changes to the structure and governance of the Credit Derivatives Determinations Committees (“DCs”). ISDA reported that the consultation indicated broad market support to implement many of the recommendations, including establishing a separate governance body, implementing certain transparency proposals relating to the publication of DC decisions and appointing up to three independent members of the DCs. Some of the proposals received a significant minority of objections.
The following Gibson Dunn attorneys assisted in preparing this update: Jeffrey Steiner, Adam Lapidus, Marc Aaron Takagaki, Hayden McGovern, and Karin Thrasher.
Gibson Dunn’s lawyers are available to assist in addressing any questions you may have regarding these developments. Please contact the Gibson Dunn lawyer with whom you usually work, any member of the firm’s Derivatives practice group, or the following practice leaders and authors:
Jeffrey L. Steiner, Washington, D.C. (202.887.3632, jsteiner@gibsondunn.com)
Michael D. Bopp, Washington, D.C. (202.955.8256, mbopp@gibsondunn.com)
Michelle M. Kirschner, London (+44 (0)20 7071.4212, mkirschner@gibsondunn.com)
Darius Mehraban, New York (212.351.2428, dmehraban@gibsondunn.com)
Jason J. Cabral, New York (212.351.6267, jcabral@gibsondunn.com)
Adam Lapidus – New York (212.351.3869, alapidus@gibsondunn.com )
Stephanie L. Brooker, Washington, D.C. (202.887.3502, sbrooker@gibsondunn.com)
William R. Hallatt , Hong Kong (+852 2214 3836, whallatt@gibsondunn.com )
David P. Burns, Washington, D.C. (202.887.3786, dburns@gibsondunn.com)
Marc Aaron Takagaki , New York (212.351.4028, mtakagaki@gibsondunn.com )
Hayden K. McGovern, Dallas (214.698.3142, hmcgovern@gibsondunn.com)
Karin Thrasher, Washington, D.C. (202.887.3712, kthrasher@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
Data center developers, investors, AI companies, and energy companies all stand to benefit from the Administration’s support for AI data center development.
With four months left in his administration, President Biden is making a play for the future with a concerted focus on developing infrastructure to support artificial intelligence (AI). A limiting factor in the advancement of AI is the need to build data centers and their associated energy infrastructure to process the extraordinary quantities of information involved in AI computations and development of large language models. Over the past weeks, the Administration has taken several significant steps to promote the development of AI data centers. Data center developers, investors, AI companies, and energy companies all stand to benefit from the Administration’s support for AI data center development.
Several months ago, Gibson Dunn formed an interdisciplinary task force of partners specializing in energy, infrastructure, real estate, digital and AI, environment, litigation, national security, and public policy to provide integrated advice to clients who are actively pursuing opportunities in the data center sector. We are closely tracking the Administration’s efforts regarding AI data centers and are available to help clients to share their insights with the Administration, as well as to take advantage of the opportunities these high-level initiatives may offer in the coming months.
I. White House Roundtable, Interagency Efforts to Promote AI Data Centers
On September 12, 2024, the Biden Administration convened AI industry leaders, utility companies, and high-level Administration officials to discuss how to ensure the United States continues to lead in AI. After the roundtable, the White House announced several new initiatives to promote AI in ways that will advance national security and protect the environment.
Most significantly, the Administration launched its Task Force on AI Datacenter Infrastructure to coordinate federal government policy across agencies. Led by the National Economic Council, National Security Council, and the White House Deputy Chief of Staff’s office, the Task Force involves the highest levels of the Biden Administration, indicating the importance the Administration is placing on this initiative. The Task Force will work with private sector leaders to identify growth opportunities, as well as with agencies to prioritize AI data center projects.
The Administration also announced that it is tasking the Federal Permitting Improvement Steering Council to work with AI data center developers and federal agencies to set comprehensive timelines for project development, provide technical assistance to the permitting agencies, and distribute funding to agencies to expedite the permitting process for data centers. The U.S. Army Corps of Engineers also will be identifying nationwide permits to expedite the construction of AI data centers. AI data centers require substantial amounts of land, water, and energy—all resources protected or regulated by federal, state, and local permitting regimes. This focus on easing the permitting process for data center developers may give investors some comfort about the shorter-term return on their investments and potentially serve as a model for broader infrastructure permitting reform.
II. Department of Energy Developments
Given AI data centers’ need for significant amounts of energy, combined with the Administration’s clean-energy goals, it is no surprise that the Department of Energy (DOE) is taking the lead on several significant projects to support AI data centers. Of interest to clients, the DOE is planning a series of convenings with industry stakeholders to discuss the challenges associated with data centers’ energy needs.
Moreover, multiple offices within the DOE are working to provide solutions to stakeholders. In August, the DOE Office of Policy developed a list of resources to help data center developers, owners and operators, and interconnection stakeholders take advantage of tax credits, financing programs, and technical assistance.
In July, the DOE Secretary of Energy Advisory Board convened a Working Group on Powering AI and Data Center Infrastructure and presented its recommendations to Jennifer Granholm, the Secretary of Energy.
The Working Group’s report encouraged the DOE to adopt several key immediate and longer-term impact recommendations for supporting AI-driven data center power demand while limiting harm to existing customers and greenhouse gas emissions. The Working Group’s three immediate impact recommendations to the DOE encouraged the DOE to:
- explore flexible siting and geographic distribution of AI large language model data centers in an effort to reduce highly concentrated loads;
- foster dialogue between energy utilities, data center developers and operators, and other key stakeholders to manage current electricity supply bottlenecks and encourage real-time data sharing; and
- rapidly assess reliability, cost, performance, and supply chain issues facing generation, storage, and grid technologies to support data center expansion.
As longer term recommendations, the Working Group encouraged the DOE to:
- establish an AI testbed within the DOE to allow researchers to develop and assess algorithms for energy-efficient AI training, and advance the United States’ AI capabilities;
- work with other government agencies and the private sector to develop a standardized and adaptable framework for orchestrating grid services; and
- accelerate and de-risk private investment in emerging technologies, particularly nuclear, geothermal, long-duration storage, and carbon capture and sequestration.
The DOE’s focus on providing data center solutions will continue as it works in conjunction with other government agencies and the private sector to drive development, provide incentives, and discover efficiencies with respect to AI-driven data center power demands.
III. Department of Commerce Developments
Along with the DOE, the Department of Commerce will play a significant role in the Administration’s efforts to promote data center development. The National Telecommunications and Information Administration (NTIA), a component of the Department of Commerce, has invited comments on data center security and supporting data center growth in the United States. The NTIA is tasked with advising the President on issues related to the internet economy, including internet infrastructure, cybersecurity, and online privacy. Much of its work focuses on expanding broadband access and adoption, particularly in rural parts of the country, and the NTIA administers grant funding programs to support expansion of broadband infrastructure.
The NTIA will use the comments to inform its work on a comprehensive report for the executive branch offering policy recommendations about how the federal government can promote data center development. The NTIA is coordinating its efforts with the DOE. The Administration seeks comments on a variety of data center development topics including AI data center usage, barriers to data center competition, supply chain vulnerabilities, risk management practices, staffing shortages, and power supply challenges.
Offering comments to the NTIA will allow interested parties to shape the recommendations made within the executive branch on the best path toward maximizing data center infrastructure. The NTIA’s advisory role and its coordination with the DOE on this report will allow commenters to reach multiple interested executive agencies through this comment process. Comments are due November 4.
Given the economic, strategic, and national security implications of the AI race, these efforts are likely just the start of a federal government campaign to support AI data centers, regardless of outcome of the November elections. In light of the Administration’s keen interest in collaborating with the private sector on AI data center development, industry participants who want to shape the future of AI and data center policy should take this opportunity to make their voices heard.
Gibson Dunn’s Data Center Task Force attorneys are available to assist clients by offering strategic advice; drafting comment letters to agencies; arranging and preparing for high-level executive branch and congressional meetings; and helping clients take advantage of potential opportunities emerging from the rapidly changing regulatory environment.
Gibson Dunn’s lawyers are available to assist in addressing any questions you may have regarding these issues. For additional information about how we may assist you, please contact the Gibson Dunn lawyer with whom you usually work, any leader or member of the firm’s Artificial Intelligence, Energy Regulation & Litigation, National Security, Public Policy, Real Estate, or White Collar Defense & Investigations practice groups, or the following authors:
Vivek Mohan – Co-Chair, Artificial Intelligence Practice Group, Palo Alto (+1 650.849.5345, vmohan@gibsondunn.com)
William R. Hollaway, Ph.D. – Chair, Energy Regulation & Litigation Practice Group, Washington, D.C. (+1 202.955.8592, whollaway@gibsondunn.com)
Tory Lauterbach – Partner, Energy Regulation & Litigation Practice Group, Washington, D.C. (+1 202.955.8519, tlauterbach@gibsondunn.com)
Stephenie Gosnell Handler – Partner, National Security Practice Group, Washington, D.C. (+1 202.955.8510, shandler@gibsondunn.com)
Michael D. Bopp – Co-Chair, Public Policy Practice Group, Washington, D.C. (+1 202.955.8256, mbopp@gibsondunn.com)
Eric M. Feuerstein – Co-Chair, Real Estate Practice Group, New York (+1 212.351.2323, efeuerstein@gibsondunn.com)
F. Joseph Warin – Co-Chair, White Collar Defense & Investigations Practice Group, Washington, D.C. (+1 202.887.3609, fwarin@gibsondunn.com)
Amanda H. Neely – Of Counsel, Public Policy Practice Group, Washington, D.C. (+1 202.777.9566, aneely@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
From the Derivatives Practice Group: This week, the Hong Kong Monetary Authority and Financial Services and the Treasury Bureau published the Consultation Conclusions on the Legislative Proposal to Implement the Regulatory Regime for Stablecoin Issuers in Hong Kong.
New Developments
- President Biden Announced Intent to Nominate Julie Brinn Siegel as a Commissioner of the CFTC. On July 11, President Biden announced his intent to nominate Julie Brinn Siegel to be a Commissioner of the CFTC. Siegel currently serves as the federal government’s deputy chief operating officer as Senior Coordinator for Management at the Office of Management and Budget (OMB). Prior to that, Siegel served as Secretary of the Treasury Janet Yellen’s Deputy Chief of Staff and served as Senior Counsel and Policy Advisor to U.S. Senator Elizabeth Warren (D-MA). Last month, President Biden nominated CFTC Commissioner Johnson to be Assistant Secretary for Financial Institutions at the Department of Treasury and nominated CFTC Commissioner Christy Goldsmith Romero to be Chair and Member of the Federal Deposit Insurance Corporation (FDIC) which, if confirmed by the Senate, would leave open two Democratic Commissioner seats at the CFTC. Siegel, if nominated and confirmed by the Senate, would take the seat of Commissioner Goldsmith Romero.
- First Interagency Fraud Disruption Conference Focuses on Combatting Crypto Schemes Commonly Known as “Pig Butchering.” On July 11, the CFTC and the DOJ’s Computer Crime and Intellectual Property Section’s National Cryptocurrency Enforcement Team (“NCET”) convened the first Fraud Disruption Conference to work on efforts to combat a type of fraud commonly known as “pig butchering”. It is estimated that Americans are scammed out of billions per year, making this a top law enforcement priority. The working group addressed strategies to prevent victimization; using technology to disrupt the fraud; and collaboration on enforcement efforts. Several agencies also collaborated on an anti-victimization messaging campaign to warn Americans to remain vigilant against emerging fraud threats.
- Supreme Court Overrules Chevron, Sharply Limiting Judicial Deference To Agencies’ Statutory Interpretation. On June 28, the Supreme Court overruled Chevron v. Natural Resources Defense Council, a landmark decision that had required courts to defer to agencies’, including the CFTC’s, reasonable interpretations of ambiguous statutory terms. For a more detailed analysis of the ruling please refer to Gibson Dunn’s client alert, available here.
- CFTC Announces Supervisory Stress Test Results. On July 1, the CFTC issued Supervisory Stress Test of Derivatives Clearing Organizations: Reverse Stress Test Analysis and Results, a report detailing the results of its fourth Supervisory Stress Test (“SST”) of derivatives clearing organization (“DCO”) resources. Among other findings, the 2024 report concluded the DCOs studied hold sufficient financial resources to withstand many extreme and often implausible price shocks. The purpose of the analysis was twofold: (1) to identify hypothetical combinations of extreme market shocks, concurrent with varying numbers of clearing member (“CM”) defaults, that would exhaust prefunded resources (DCO committed capital, and default fund), and unfunded resources available to the DCOs (this represents the reverse stress test component), and (2) to analyze the impacts of DCO use of mutualized resources on non-defaulted CMs.
New Developments Outside the U.S.
- ESAs Establish Framework to Strengthen Coordination in Case of Systemic Cyber Incidents. On July 17, the European Supervisory Authorities (“ESAs”) announced they will establish the EU systemic cyber incident coordination framework (“EU-SCICF”), in the context of the Digital Operational Resilience Act (“DORA”), that will aim to facilitate an effective financial sector response to a cyber incident that poses a risk to financial stability, by strengthening the coordination among financial authorities and other relevant bodies in the European Union, as well as with key actors at international level. [NEW]
- ESAs Publish Second Batch of Policy Products under DORA. On July 17, the ESAs published the second batch of policy products under DORA. This batch consists of four final draft regulatory technical standards, one set of Implementing Technical Standards and 2 guidelines, all of which aim at enhancing the digital operational resilience of the EU’s financial sector. [NEW]
- Hong Kong HKMA and FSTB Publishes Results from Stablecoin Consultation. On July 17, 2024, the Hong Kong Monetary Authority (“HKMA”) and Financial Services and the Treasury Bureau (“FSTB”) published the Consultation Conclusions on the Legislative Proposal to Implement the Regulatory Regime for Stablecoin Issuers in Hong Kong (“Consultation Conclusions”). The Consultation Conclusions outlined the legislative proposal to implement a regulatory regime for fiat-referenced stablecoin (“FRS”) issuers in Hong Kong. The regime will primarily focus on representations of value which rest on ledgers that are operated in a decentralized manner in which no person has the unilateral authority to control or materially alter its functionality or operation. Under this regime, FRS issuers will require a license. Foreign entities intending to apply for a license will be required to establish a Hong Kong subsidiary and have key management personnel in the territory. [NEW]
- ESMA Consults on Firms’ Order Execution Policies Under MiFID II. On July 16, ESMA launched a consultation on draft technical standards specifying the criteria for how investment firms establish and assess the effectiveness of their order execution policies. The objective of the proposed technical standards is to foster investor protection by enhancing investment firms’ order execution. [NEW]
- ESMA Publishes 2023 Data on Cross-Border Investment Activity of Firms. On July 15, ESMA announced they completed an analysis of the cross-border provision of investment services during 2023. The main findings include that a total of around 386 firms provided services to retail clients on a cross-border basis in 2023; compared to 2022, the cross-border market for investment services grew by 1.6% in terms of firm numbers, and by 5% in terms of retail clients, while the number of complaints increased by 31%; and Germany, France, Spain, and Italy are the most significant destinations (in terms of number of retail clients) for investment firms providing cross-border services in other Member States. [NEW]
- ESAs Consult on Guidelines under the Markets in Crypto-Assets Regulation. On July 12, the ESAs published a consultation paper on Guidelines under Markets in Crypto-assets Regulation (“MiCA”), establishing templates for explanations and legal opinions regarding the classification of crypto-assets along with a standardized test to foster a common approach to classification.
- ESAs Report on the Use of Behavioral Insights in Supervisory and Policy Work. On July 11, the ESAs published a joint report following their workshop on the use of behavioral insights by supervisory authorities in their day-to-day oversight and policy work. The report provides a high-level overview of the main topics discussed during the workshop held in February 2024 for national supervisors and other competent authorities, where participants explored the added value of behavioral insights in their work by exchanging their experiences and discussing the challenges they face.
- ESMA Publishes the 2024 ESEF Reporting Manual. On July 11, ESMA published the update of its Reporting Manual on the European Single Electronic Format (“ESEF”) supporting a harmonized approach for the preparation of annual financial reports. ESMA has also updated the Annex II of the Regulatory Technical Standards (“RTS”) on ESEF.
- ESMA Publishes Statement on Use of Collateral by NFCs Acting as Clearing Members. On July 10, ESMA issued a public statement on deprioritizing supervisory actions linked to the eligibility of uncollateralized public guarantees, public bank guarantees, and commercial bank guarantees for Non-Financial Counterparties (“NFCs”) acting as clearing members, pending the entry into force of EMIR 3.
- ESMA Launches New Consultations. On July 10, ESMA published a new package of public consultations with the objective of increasing transparency and system resilience in financial markets, reducing reporting burden and promoting convergence in the supervisory approach.
- ESMA Consults on Rules to Recalibrate and Further Clarify the Framework. On July 9, ESMA launched new consultations on different aspects of the Central Securities Depositories Regulation (“CSDR”) Refit. The proposed rules relate to the information to be provided by European CSDs to their national competent authorities (“NCA”s) for the review and evaluation, the information to be notified to ESMA by third-country CSDs, and the scope of settlement discipline.
- ESMA Consults on Liquidity Management Tools for Funds. On July 8, ESMA announced it is seeking input on draft guidelines and technical standards under the revised Alternative Investment Fund Managers Directive (“AIFMD”) and the Undertakings for Collective Investment in Transferable Securities (“UCITS”) Directive. Both Directives aim to mitigate potential financial stability risks and promote harmonization of liquidity risk management in the investment funds sector.
- ESMA Consults on Reporting Requirements and Governance Expectations for Some Supervised Entities. On July 8, ESMA launched two consultations on proposed guidance for some of its supervised entities. The consultations are aimed at the following entities supervised by ESMA: Benchmark Administrators, Credit Rating Agencies, and Market Transparency Infrastructures. The Consultation Paper sets out the information ESMA expects to receive and a timeline for supervised entities to provide the required information. The objective of the Draft Guidelines is to ensure consistency in cross-sectoral reporting.
- ESMA Puts Forward Measures to Support Corporate Sustainability Reporting. On July 5, ESMA published a Final Report on the Guidelines on Enforcement of Sustainability Information (“GLESI”) and a Public Statement on the first application of the European Sustainability Reporting Standards (“ESRS”). ESMA reports that these documents will support the consistent application and supervision of sustainability reporting requirements.
- ESMA Releases New MiCA Rules To Increase Transparency for Retail Investors. On July 4, ESMA published the second Final Report under the Markets in Crypto-Assets Regulation (MiCA) covering eight draft technical standards that aim to provide more transparency for retail investors, clarity for providers on the technical aspects of disclosure and record-keeping requirements, and data standards to facilitate supervision by National Competent Authorities (“NCAs”). The report covers public disclosures, as well as descriptions on how issuers should disclose price-sensitive information to the public to prevent market abuses, such as insider dealing.
- ESMA Reappoints Three Members to its Management Board. On July 4, ESMA announced that it has reappointed three current members to its Management Board. The appointments took place at the Board of Supervisors meeting on July 3. The Management Board, chaired by Verena Ross, Chair of ESMA, is responsible for ensuring that the Authority carries out its mission and performs the tasks assigned to it under its founding Regulation.
New Industry-Led Developments
- ISDA Publishes Whitepaper: Hedge Accounting Under US GAAP. On July 16, ISDA published a whitepaper that explores the issues faced by financial and non-financial institutions in applying hedge accounting for interest rate risk, foreign exchange risk and other risks. It highlights both the prescriptive nature of Accounting Standards Codification 815 and the inconsistent interpretations among auditors, which together create operational burdens and can limit hedging strategies. The paper proposes potential solutions to these challenges, including the expansion of hedge eligibility and the revision of hedge accounting criteria, to allow better use of existing risk management tools. [NEW]
- ISDA and SIFMA Submit Addendum on GIRR Curvature to US Basel III NPR. On July 15, ISDA and the Securities Industry and Financial Markets Association (“SIFMA”) submitted an addendum to the joint US Basel III “endgame” notice of proposed rulemaking. The addendum contains a proposal for general interest rate risk (“GIRR”) curvature to fix an issue that was recently identified. [NEW]
- ISDA Chief Executive Officer Scott O’Malia Offers Informal Comments on Terminating Derivatives Contracts. On July 15, ISDA CEO Scott O’Malia opined on the process to terminate a derivatives contract. ISDA is developing wo initiatives – the ISDA Close-out Framework and the ISDA Notices Hub – that will help ensure a key part of the termination process is more efficient. The ISDA Close-out Framework is designed to illustrate the various steps and decisions firms need to take and is intended as a preparatory tool for future stress events. The ISDA Notices Hub allows the instantaneous delivery and receipt of notices via a secure online platform, eliminating risk exposures and potential losses that can result from delays in terminating derivatives contracts. [NEW]
- Trade Associations Submit Letter on EMIR IM Model Validation. On July 8, ISDA, the Alternative Investment Management Association (“AIMA”), the European Fund and Asset Management Association (“EFAMA”) and the Securities Industry and Financial Markets Association’s asset management group (“SIFMA AMG”) submitted a letter to the ESAs and the European Commission on initial margin (“IM”) model approval requirements set out in the European Market Infrastructure Regulation (“EMIR 3.0”). The letter highlights challenges posed by the three-month period granted to the European Banking Authority and NCAs to validate changes to an IM model and describes how the ISDA Standard Initial Margin Model (“ISDA SIMM”) schedule can be amended to address these issues.
- ISDA Proceeds with Development of an Industry Notices Hub. On July 1, ISDA announced it will proceed with the development of an industry-wide notices hub, following strong support from buy- and sell-side institutions globally. The new online platform will allow instantaneous delivery and receipt of critical termination-related notices and help to ensure address details for physical delivery are up to date, reducing the risk of uncertainty and potential losses for senders and recipients of these notices.
The following Gibson Dunn attorneys assisted in preparing this update: Jeffrey Steiner, Adam Lapidus, Marc Aaron Takagaki, Hayden McGovern, and Karin Thrasher.
Gibson Dunn’s lawyers are available to assist in addressing any questions you may have regarding these developments. Please contact the Gibson Dunn lawyer with whom you usually work, any member of the firm’s Derivatives practice group, or the following practice leaders and authors:
Jeffrey L. Steiner, Washington, D.C. (202.887.3632, jsteiner@gibsondunn.com)
Michael D. Bopp, Washington, D.C. (202.955.8256, mbopp@gibsondunn.com)
Michelle M. Kirschner, London (+44 (0)20 7071.4212, mkirschner@gibsondunn.com)
Darius Mehraban, New York (212.351.2428, dmehraban@gibsondunn.com)
Jason J. Cabral, New York (212.351.6267, jcabral@gibsondunn.com)
Adam Lapidus – New York (212.351.3869, alapidus@gibsondunn.com )
Stephanie L. Brooker, Washington, D.C. (202.887.3502, sbrooker@gibsondunn.com)
William R. Hallatt , Hong Kong (+852 2214 3836, whallatt@gibsondunn.com )
David P. Burns, Washington, D.C. (202.887.3786, dburns@gibsondunn.com)
Marc Aaron Takagaki , New York (212.351.4028, mtakagaki@gibsondunn.com )
Hayden K. McGovern, Dallas (214.698.3142, hmcgovern@gibsondunn.com)
Karin Thrasher, Washington, D.C. (202.887.3712, kthrasher@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
From the Derivatives Practice Group: This week, the CFTC released a report detailing the results of its fourth Supervisory Stress Test of derivatives clearing organization resources. The report concluded the derivatives clearing organization hold sufficient resources to withstand extreme price shocks.
New Developments
- Supreme Court Overrules Chevron, Sharply Limiting Judicial Deference To Agencies’ Statutory Interpretation. Last week, the Supreme Court overruled Chevron v. Natural Resources Defense Council, a landmark decision that had required courts to defer to agencies’, including the CFTC’s, reasonable interpretations of ambiguous statutory terms. For a more detailed analysis of the ruling please refer to Gibson Dunn’s client alert, available here. [NEW]
- CFTC Announces Supervisory Stress Test Results. On July 1, the CFTC issued Supervisory Stress Test of Derivatives Clearing Organizations: Reverse Stress Test Analysis and Results, a report detailing the results of its fourth Supervisory Stress Test (“SST”) of derivatives clearing organization (“DCO”) resources. Among other findings, the 2024 report concluded the DCOs studied hold sufficient financial resources to withstand many extreme and often implausible price shocks. The purpose of the analysis was twofold: (1) to identify hypothetical combinations of extreme market shocks, concurrent with varying numbers of clearing member (“CM”) defaults, that would exhaust prefunded resources (DCO committed capital, and default fund), and unfunded resources available to the DCOs (this represents the reverse stress test component), and (2) to analyze the impacts of DCO use of mutualized resources on non-defaulted CMs. [NEW]
- CFTC Staff Issues a No-Action Letter Regarding Certain Reporting Requirements for Swaps Transitioning from CDOR to CORRA. On June 27, the CFTC Division of Market Oversight (“DMO”) and Division of Data (“DOD”) issued a staff no-action letter regarding certain Part 43 and Part 45 swap reporting obligations for swaps transitioning under the ISDA LIBOR fallback provisions from referencing the Canadian Dollar Offered Rate (“CDOR”), to referencing the risk-free Canadian Overnight Repo Rate Average (“CORRA”) following the cessation of CDOR after June 28, 2024. The letter states DMO and DOD will not recommend the CFTC take enforcement action against an entity for failure to timely report under Part 45 the change in a swap’s floating rate. This letter covers those floating rate changes that are made under the ISDA LIBOR fallback provisions from CDOR to CORRA, but only in the event the entity uses its best efforts to report the change by the applicable deadline in Part 45 and in no case reports the required information later than five business days from, but excluding, July 2, 2024. The letter also states DMO and DOD will not recommend the CFTC take enforcement action against an entity for failure to report under Part 43 the change in the floating rate for a swap modified after execution to incorporate the ISDA LIBOR fallback provisions to transition from referencing CDOR to referencing CORRA.
- CFTC Extends Public Comment Period for Proposed Amendments to Event Contracts Rules. On June 27, the CFTC announced it is extending the deadline for public comment on a proposal to amend its event contract rules. The extended comment period will close on August 8, 2024. The CFTC is providing an extension to allow interested persons additional time to analyze the proposal and prepare their comments. The proposal would amend CFTC Regulation 40.11 to further specify types of event contracts that fall within the scope of Commodity Exchange Act (“CEA”) Section 5c(c)(5)(C) and are contrary to the public interest, such that they may not be listed for trading or accepted for clearing on or through a CFTC-registered entity.
- CFTC Grants ForecastEx, LLC DCO Registration and DCM Designation. On June 25, the CFTC announced that it has issued ForecastEx, LLC an Order of Registration as a DCO and an Order of Designation as a designated contract market (“DCM”) under the CEA. DCO registration was granted under Section 5b of the CEA. DCM designation was granted under Section 5a of the CEA. ForecastEx is a limited liability company registered in Delaware and headquartered in Chicago, Illinois.
- CFTC Approves Final Capital Comparability Determinations for Certain Non-U.S. Nonbank Swap Dealers. On June 25, the CFTC announced it has approved four comparability determinations and related comparability orders granting conditional substituted compliance in connection with the CFTC’s capital and financial reporting requirements to certain CFTC-registered nonbank swap dealers organized and domiciled in Japan, Mexico, the European Union (France and Germany), or the United Kingdom. Pursuant to the orders, non-U.S. nonbank swap dealers subject to prudential regulation by the Financial Services Agency of Japan, the National Banking and Securities Commission of Mexico and the Mexican Central Bank, the European Central Bank, or the United Kingdom Prudential Regulation Authority may satisfy certain CEA capital and financial reporting requirements by being subject to, and complying with, comparable capital and financial reporting requirements under the respective foreign jurisdiction’s laws and regulations, subject to specified conditions.
New Developments Outside the U.S.
- ESMA Puts Forward Measures to Support Corporate Sustainability Reporting. On July 5, ESMA published a Final Report on the Guidelines on Enforcement of Sustainability Information (“GLESI”) and a Public Statement on the first application of the European Sustainability Reporting Standards (“ESRS”). ESMA reports that these documents will support the consistent application and supervision of sustainability reporting requirements. [NEW]
- New MiCA Rules Increase Transparency for Retail Investors. On July 4, ESMA published the second Final Report under the Markets in Crypto-Assets Regulation (MiCA) covering eight draft technical standards that aim to provide more transparency for retail investors, clarity for providers on the technical aspects of disclosure and record-keeping requirements, and data standards to facilitate supervision by National Competent Authorities (“NCAs”). The report covers public disclosures, as well as descriptions on how issuers should disclose price-sensitive information to the public to prevent market abuses, such as insider dealing. [NEW]
- ESMA Reappoints Three Members to its Management Board. On July 4, ESMA announced that it has reappointed three current members to its Management Board. The appointments took place at the Board of Supervisors meeting on July 3. The Management Board, chaired by Verena Ross, Chair of ESMA, is responsible for ensuring that the Authority carries out its mission and performs the tasks assigned to it under its founding Regulation. [NEW]
- EBA and ESMA Publish Guidelines on Suitability of Management Body Members and Shareholders for Entities Under MiCA. On June 27, EBA and ESMA published joint guidelines on the suitability of members of the management body, and on the assessment of shareholders and members with qualifying holdings for issuers of asset reference tokens (“ARTs”) and crypto-asset service providers (“CASPs”), under the MiCA. The first set of guidelines covers the presence of suitable management bodies within issuers of ARTs and CASPs. The second set of guidelines concerns the assessment of the suitability of shareholders or members with direct or indirect qualifying holdings in a supervised entity.
- ESAs Propose Improvements to the Sustainable Finance Disclosure Regulation. On June 18, the EBA, the European Insurance and Occupational Pensions Authority (“EIOPA”), and ESMA (the three European Supervisory Authorities , i.e., “ESAs”)
published a Joint Opinion on the assessment of the Sustainable Finance Disclosure Regulation (“SFDR”). In the joint opinion, the ESAs call for a coherent sustainable finance framework that caters for both the green transition and enhanced consumer protection, considering the lessons learned from the functioning of the SFDR.
New Industry-Led Developments
- ISDA Proceeds with Development of an Industry Notices Hub. On July 1, ISDA announced it will proceed with the development of an industry-wide notices hub, following strong support from buy- and sell-side institutions globally. The new online platform will allow instantaneous delivery and receipt of critical termination-related notices and help to ensure address details for physical delivery are up to date, reducing the risk of uncertainty and potential losses for senders and recipients of these notices. [NEW]
- ISDA Publishes Framework to Prepare for Close Out of Derivatives Contracts. On June 27, ISDA published the ISDA Close-out Framework that market participants can use to help prepare for potential terminations of collateralized derivatives contracts. ISDA stated that the launch of the ISDA Close-out Framework is in response to the March 2023 failure of Signature Bank and SVB in the US, which, according to ISDA, highlighted the complexities of potentially terminating over-the-counter derivatives trading relationships following various post-crisis regulatory reforms. Specifically, the reforms require that in-scope entities post margin for non-cleared derivatives transactions, while various jurisdictions have introduced mandatory stays on termination rights and remedies as part of bank resolution regimes. ISDA stated that the ISDA Close-out Framework is intended to be used as a preparatory resource to help firms coordinate internal business functions and stakeholders and internal and external legal, operational, risk management, infrastructure and other relevant service providers to ensure they are adequately prepared for any potential future stress events.
- ISDA Responds to CCIL on Proposal for USD/INR FX Options. On June 21, ISDA submitted a response to a consultation paper from the Clearing Corporation of India Limited (“CCIL”) on a proposal to introduce an electronic trading platform and clearing and settlement services for USD/INR FX options of up to one year maturity initially. The response sets out the features of the trading platform, the risk management framework and a questionnaire on the parameters of the product. ISDA’s response focuses mainly on the risk management framework aspect, including the margin models and default management framework. It asks for more clarity and transparency on the choice of margin models and encourages the implementation of scheduled variation margin calls and stress-based anti-procyclicality measures.
- ISDA Responds to FSB Consultation on Liquidity Preparedness for Margin and Collateral Calls. On June 18, ISDA submitted a response to the Financial Stability Board’s (FSB) consultation on liquidity preparedness for margin and collateral calls. The response notes that the recommendations are generally sensible and seek to incorporate a proportionate and risk-based approach. It also highlights a number of considerations relevant to the non-bank financial intermediation (“NBFI”) sector’s liquidity preparedness for margin and collateral calls.
The following Gibson Dunn attorneys assisted in preparing this update: Jeffrey Steiner, Adam Lapidus, Marc Aaron Takagaki, Hayden McGovern, and Karin Thrasher.
Gibson Dunn’s lawyers are available to assist in addressing any questions you may have regarding these developments. Please contact the Gibson Dunn lawyer with whom you usually work, any member of the firm’s Derivatives practice group, or the following practice leaders and authors:
Jeffrey L. Steiner, Washington, D.C. (202.887.3632, jsteiner@gibsondunn.com)
Michael D. Bopp, Washington, D.C. (202.955.8256, mbopp@gibsondunn.com)
Michelle M. Kirschner, London (+44 (0)20 7071.4212, mkirschner@gibsondunn.com)
Darius Mehraban, New York (212.351.2428, dmehraban@gibsondunn.com)
Jason J. Cabral, New York (212.351.6267, jcabral@gibsondunn.com)
Adam Lapidus – New York (212.351.3869, alapidus@gibsondunn.com )
Stephanie L. Brooker, Washington, D.C. (202.887.3502, sbrooker@gibsondunn.com)
William R. Hallatt , Hong Kong (+852 2214 3836, whallatt@gibsondunn.com )
David P. Burns, Washington, D.C. (202.887.3786, dburns@gibsondunn.com)
Marc Aaron Takagaki , New York (212.351.4028, mtakagaki@gibsondunn.com )
Hayden K. McGovern, Dallas (214.698.3142, hmcgovern@gibsondunn.com)
Karin Thrasher, Washington, D.C. (202.887.3712, kthrasher@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
In Ryan, LLC v. Federal Trade Commission, the Northern District of Texas concluded “The role of an administrative agency is to do as told by Congress, not to do what the agency think[s] it should do.”
On July 3, 2024, the United States District Court for the Northern District of Texas concluded that the Federal Trade Commission’s Non-Compete Rule, which would retroactively invalidate over 30 million employment contracts and preempt the laws of 46 states, exceeds the FTC’s statutory authority and is arbitrary and capricious in violation of the Administrative Procedure Act. The court preliminarily enjoined enforcement of the Rule and stayed its effective date, but limited the scope of relief to the parties to the case. The court did not issue a nationwide preliminary injunction.
Background
Section 5 of the FTC Act authorizes the FTC “to prevent” the use of “unfair methods of competition” through case-by-case adjudication. Section 6(g) of the Act grants the FTC ancillary powers to support administrative adjudication, including the powers to make recommendations, publish reports, classify corporations, and “make rules and regulations for the purposes of carrying out the provisions of this subchapter.”
On April 23, the FTC promulgated the Non-Compete Rule by a 3-2 vote. The Rule invokes the FTC’s purported authority under Sections 5 and 6 and declares that nearly all non-compete agreements between employers and employees are “unfair methods of competition.” The Rule accordingly prohibits businesses from entering into new non-competes except for those associated with the sale of certain business interests and bans the enforcement of nearly all non-competes (with narrow exceptions for the sale of certain business interests and for agreements with certain senior executives). The Rule also expressly preempted the laws of the 46 states that allow non-compete agreements.
Ryan, LLC, is a global tax-consulting firm headquartered in Dallas. Its principals and other workers are sought-after tax experts, many of whom agree to temporally limited non-compete agreements.
Represented by Gibson Dunn, Ryan filed suit against the FTC in the Northern District of Texas, alleging that the Non-Compete Rule exceeds the FTC’s statutory authority, violates the Administrative Procedure Act, and defies the major questions doctrine, which instructs that federal agencies cannot regulate questions of deep economic and political significance absent clear authority from Congress. A group of trade associations led by the United States Chamber of Commerce intervened in the case to challenge the Rule as well.
The Court’s Opinion
- The court determined that the Non-Compete Rule exceeds the scope of the FTC’s statutory authority. “By a plain reading, Section 6(g) of the Act does not expressly grant the Commission authority to promulgate substantive rules regarding unfair methods of competition.” The court emphasized that, unlike Section 5, Section 6(g) “contains no penalty provision—which indicates a lack of substantive force.” Further, the court noted that “the location of the alleged substantive rulemaking authority is suspect . . . . Section 6(g) is the seventh in a list of twelve almost entirely investigative powers.”
- The court further concluded that the Non-Compete Rule is arbitrary and capricious in violation of the Administrative Procedure Act. First, the Rule “is unreasonably overbroad without a reasonable explanation.” The FTC “lack[ed] . . . evidence as to why they chose to impose such a sweeping prohibition—that prohibits entering or enforcing virtually all non-competes—instead of targeting specific, harmful non-competes.” Second, “the FTC insufficiently addressed alternatives to issuing the Rule.” It “dismissed any possible alternatives, merely concluding that either the pro-competitive justifications outweighed the harms, or that employers had other avenues to protect their interests.”
- The court did not address the major questions doctrine.
- The court determined that Ryan and the intervenors would suffer irreparable harm if the Rule takes effect because they would face “financial injury” and expend “nonrecoverable costs [when] complying with the Rule.”
- The court declined to enter a nationwide preliminary injunction. The preliminary injunction and stay are limited to Ryan and the intervenors, and do not extend to intervenors’ member companies or other nonparties.
What It Means:
- The Non-Compete Rule was scheduled to take effect on September 4. As long as the preliminary injunction and stay are in place, the FTC cannot enforce the Rule against Ryan or the intervenors. Their existing non-compete agreements remain enforceable under federal law, and they are free to enter into new non-compete agreements.
- In the absence of nationwide relief, the Rule will go into effect on September 4 as to all other employers, meaning that state non-compete laws will be preempted, existing non-compete agreements will be retroactively invalidated, and businesses will be unable to enter into new non-compete agreements unrelated to certain sales of businesses.
- The decision is not binding precedent on other courts.
- Proceedings before the district court will continue. The court indicated that it would enter a final ruling on the merits by August 30.
The following Gibson Dunn lawyers prepared this update: Eugene Scalia, Allyson N. Ho, Amir C. Tayrani, Andrew Kilberg, Elizabeth A. Kiernan, Aaron Hauptman, and Josh Zuckerman.
Gibson Dunn’s lawyers are available to assist in addressing any questions you may have regarding the issues discussed in this update. Please contact the Gibson Dunn lawyer with whom you usually work, the authors, or any leader or member of the firm’s Appellate & Constitutional Law, Labor & Employment, Administrative Law & Regulatory, or Antitrust & Competition practice groups:
Appellate and Constitutional Law:
Thomas H. Dupree Jr. – Washington, D.C. (+1 202.955.8547, tdupree@gibsondunn.com)
Allyson N. Ho – Dallas (+1 214.698.3233, aho@gibsondunn.com)
Julian W. Poon – Los Angeles (+ 213.229.7758, jpoon@gibsondunn.com)
Labor and Employment:
Andrew G.I. Kilberg – Washington, D.C. (+1 202.887.3759, akilberg@gibsondunn.com)
Karl G. Nelson – Dallas (+1 214.698.3203, knelson@gibsondunn.com)
Jason C. Schwartz – Washington, D.C. (+1 202.955.8242, jschwartz@gibsondunn.com)
Katherine V.A. Smith – Los Angeles (+1 213.229.7107, ksmith@gibsondunn.com)
Administrative Law and Regulatory:
Eugene Scalia – Washington, D.C. (+1 202.955.8673, escalia@gibsondunn.com)
Helgi C. Walker – Washington, D.C. (+1 202.887.3599, hwalker@gibsondunn.com)
Antitrust and Competition:
Rachel S. Brass – San Francisco (+1 415.393.8293, rbrass@gibsondunn.com)
Svetlana S. Gans – Washington, D.C. (+1 202.955.8657, sgans@gibsondunn.com)
Cynthia Richman – Washington, D.C. (+1 202.955.8234, crichman@gibsondunn.com)
Stephen Weissman – Washington, D.C. (+1 202.955.8678, sweissman@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
In the lead up to the election, the Labour Party proposed extensive reforms to UK employment law as part of “Labour’s Plan to Make Work Pay: Delivering A New Deal for Working People.” Legislation is expected to be put before Parliament within the first 100 days of the Labour Party’s entry into government.
On July 5, 2024, the Labour Party was announced to have won a substantial majority in the UK General Election that was held on July 4, 2024, marking an end to the Conservative Party’s 14 years in power. In the lead up to the election, the Labour Party proposed extensive reforms to UK employment law as part of “Labour’s Plan to Make Work Pay: Delivering A New Deal for Working People” (the “New Deal”), and legislation is expected to be put before Parliament within the first 100 days of the Labour Party’s entry into government. In this update, we outline these anticipated developments in UK employment law.
A brief overview of the potential developments which we believe will be of interest to our clients is provided below, with more detailed information on each topic available by clicking on the links.
1. Implementing Workforce Changes(view details)
We summarise changes proposed to an employer’s ability to terminate employees who have acquired less than two years of service, as well as the impact on employers of proposed changes: (i) to the controversial practice of dismissing and re-hiring employees as a means of changing terms of employment; and (ii) designed to strengthen employee rights and protections in connection with both collective redundancy situations (lay-offs) and business transfers, strategic sourcing transactions, and other transfers subject to the Transfer of Undertakings (Protection of Employment) Regulations 2006 (SI 2006/246) (“TUPE”).
2. Enforcement of UK Employment Law (view details)
We summarise proposed reforms to the practice of enforcing UK employment laws, including the establishment of a single enforcement body and the extension of the time limit for bringing the majority of employment claims before the Employment Tribunal. We also consider the potential new ability for employees to collectively raise grievances about their workplace with Advisory, Conciliation and Arbitration Service (“ACAS”).
3. Discrimination, Diversity, Equity and Inclusion (view details)
We summarise the proposed new obligations on employers to address the gender pay gap, reduce workplace harassment, strengthen whistleblower rights, extend the gender pay gap regime to include race and disability, and carry out ethnicity and disability pay gap reporting. We also consider potential changes to family-friendly rights.
4. Working Arrangements (view details)
We consider the proposed changes to an employer’s ability to engage workers on “zero hour” contracts, changes to national minimum wage (“NMW”) rates, and the introduction of fair pay agreements to the adult social care sector. We also summarise the potential new right for employees to disconnect from work outside of working hours, enhancements to the right to flexible working, and the strengthening of trade unions.
5. Employment Status (view details)
We consider the possible move away from the three-tier system of employee, worker and self-employed contractor that currently exists in the UK towards a simpler two-part framework of employment status, and the proposal to strengthen the rights and protections of the self-employed.
We will provide a further update once the Labour government publishes draft legislation implementing these changes. In the meantime, we will continue to work with our clients to navigate the changing employment landscape in the UK.
APPENDIX
Unfair Dismissal
UK employees with less than two years of continuous service do not currently benefit from protection against unfair dismissal, except in certain limited circumstances. Unfair dismissal protection restricts an employer’s ability to terminate their employment other than for reasons of: (i) capability; (ii) conduct; (iii) redundancy; or (iii) some other substantial reason, while also requiring employers to follow a fair dismissal process.
The Labour government has indicated that a form of unfair dismissal protection will be extended to employees from day one of their employment to ensure that new hires are not terminated without cause. In response to protests from employer organisations, the Labour government has suggested that employers will still be able to operate probationary periods to assess new hires, although for how long such probation periods may last remains to be seen.
Dismissal and Re-engagement
The Labour government has also committed to ending the practice known as “fire and rehire” as a lawful means of imposing unilateral changes to an employee’s contractual terms of employment. This was an area that the previous government attempted to reform by implementing a Statutory Code of Practice on Dismissal and Re-engagement (the “Code”) which employers should follow when seeking to change employment terms and conditions using the method of dismissal and re-engagement. This Code was expected to come into force on July 18, 2024, although it is yet to be seen whether the new Labour government will implement it in its current form.
Instead, it is anticipated that the Code will be replaced by new laws designed to regulate the practice of firing and rehiring employees in order to change their terms of employment.
Redundancy and TUPE
Currently, UK employers are required to follow a collective consultation process when proposing to make at least 20 redundancies in a single establishment (often interpreted as one workplace) within a 90-day period. The Labour government has committed to strengthening employee redundancy rights and protections, which includes making the right to redundancy consultation determined by the number of people impacted across the business rather than in one workplace.
Employees who are subject to TUPE processes also currently enjoy protection from termination of employment and/or changes to their contractual terms that are imposed by reason of a TUPE transfer. The Labour government has stated that they will strengthen existing rights and protections under TUPE, although it is not clear in what way these rights would be strengthened.
Establishing a Single Enforcement Body
Save in relation to equality and human rights, the current enforcement of UK employment rights relies on individual employees or trade unions bringing a claim before the Employment Tribunal. The Labour government plans to establish a single enforcement body to enforce workers’ rights going forward, to include not only equality and human rights but other areas of employment law such as health and safety, minimum wage, and worker exploitation. This body will have strong powers to undertake targeted and proactive enforcement work, such as carrying out unannounced inspections, following up on anonymous tip-offs, and bringing civil proceedings to uphold employment rights.
Employment Tribunal Claims
The time limit for bringing many types of UK employment claims in an employment tribunal currently expires three months from the date the claim arises, subject to an extension of up to six weeks for pre-claim conciliation. The Labour government plans to extend the time limit to bring all UK employment claims to six months.
Collective Grievances
UK employees can currently formally raise individual grievances about conduct in the workplace with their employer through ACAS. The Labour government has stated that it will provide employees with the ability to raise collective grievances about conduct in their place of work directly to ACAS.
Pay Gap Reporting and Action Plans
UK employers with more than 250 staff are currently required to report their gender pay gap data by April 4 of each year. There is currently no mandatory requirement for employers to report on their ethnicity or disability pay gap.
The Labour government has stated that the publication of ethnicity and disability pay gaps will become mandatory for employers with more than 250 employees, mirroring gender pay gap reporting. Although not mentioned in the New Deal, the Labour government has indicated that it would implement new legislation to tackle structural racism, including the issue of low pay for ethnic minorities, with fines for employers not taking appropriate action on their pay gap data.
Large employers are expected to be required to develop, publish, and implement action plans to close their gender pay gaps, and to include outsourced workers in their gender pay gap and pay ratio reporting. Similarly, employers with more than 250 employees are expected to be required to produce Menopause Action Plans, setting out how they will support employees going through the menopause at work.
Another proposed policy, not mentioned in the New Deal but included in the Labour manifesto, is to extend the current gender equal pay regime to include race and disability. This will be enforced by a new regulatory unit with trade union backing.
Workplace Harassment and Whistleblowing
The Labour government has stated that it will “require employers to create and maintain workplaces and working conditions free from harassment, including third parties”, and will also strengthen the legal duty for employers to take all reasonable steps to stop harassment, including sexual harassment, before it starts. Although not mentioned in the New Deal, the Labour government also previously indicated that women who report sexual harassment at work would be provided with the same protections from dismissal and detriment as other whistleblowers.
The previous government also sought to implement a new mandatory duty to prevent sexual harassment in the workplace, which had been expected to come into force in October 2024, however this duty does not currently cover harassment by third parties. It remains to be seen if the new mandatory duty will be implemented in its current form.
The Labour government has committed to strengthening whistleblowers’ rights, and we await details of this new policy.
Family Leave Rights
Whilst UK employment law already provides for extensive family leave rights, the Labour government has stated it would make various enhancements:
- parental leave, which entitles parents with at least one years’ service to take up to 18 weeks of unpaid leave for each child until the child is 18, will become available to employees from day one of their employment;
- it will be unlawful to dismiss a woman during pregnancy or within six months of her return to work following maternity leave, other than in specified circumstances. This is expected to build on the existing protections afforded to pregnant women or women on maternity leave; and
- entitlement to bereavement leave will be clarified and extended to all employees. Currently, employees do not have a statutory right to paid time off when someone dies, unless they are entitled to parental bereavement leave.
The Labour government has also stated that the system of parental leave will be reviewed within its first year and that the implementation of the legislation for unpaid carers’ leave, which entitles employees to take up to one week every 12 months to help a dependent who needs long-term care and was introduced in April 2024, will be reviewed. The Labour government also plans to examine the potential benefits of introducing paid carers’ leave.
Engagement of Casual and/or Low Paid Workers
The Labour government has committed to:
- banning contracts that provide no guarantee of work, known as “zero hour” contracts, although it has been reported that this would not be a total ban and would allow workers to remain on zero hour contracts in certain circumstances; and
- ensuring that workers have the right to: (i) a contract that reflects the number of hours they regularly work based on a twelve-week reference period; and (ii) reasonable notice of any change in shifts or working time, with compensation that is proportionate to the notice given for any shifts cancelled or curtailed.
The previous government had attempted to regularise the engagement of casual workers in the UK by implementing a statutory right to a predictable working pattern, which is expected to come into force in September 2024; it is currently unclear if the new Labour government will implement this provision.
The Labour government also announced various proposed enhancements to the NMW rate, which is currently split into age bands and is reviewed and updated each year. The Labour government plans to: (i) remove the age bands, which it considers discriminatory; and (ii) expand the remit of the Low Pay Commission, which currently reviews and makes recommendations on the NMW rate, to ensure that the rate considers increases in cost of living.
The Labour government has pledged to introduce a “Fair Pay Agreement” to the adult social care sector. This will offer social care workers stronger collective bargaining rights in pay negotiations.
Right to Disconnect and Work Autonomously
The Labour government has stated a new “right to switch off” would be introduced, which would give UK employees the right to disconnect from outside of working hours and not be contacted by their employers. This would follow models already in place in Ireland and Belgium, which give employers and employees the opportunity to work together on bespoke workplace policies or contractual terms that benefit both parties in this respect.
The Labour government has also stated that they will ensure that proposals by employers to use surveillance technologies will be subject to consultation and negotiation, with a view to agreement of trade unions or staff representatives.
Right to Flexible Working
The right to request flexible working recently became a day one right in the UK on April 6, 2024. The Labour government has stated that flexible working would be made the default for all workers from the first day of employment, except where not reasonably feasible, although it is currently unclear what this will involve.
Trade Unions
The Labour government plans to update trade union legislation so that, among other things, employers will be required to inform workers of their right to join a trade union. Additionally, recent legislation introduced by the previous government to restrict trade union activity, such as the minimum service level requirement in essential services, is likely to be repealed. Industrial action ballot requirements will also be eased, and limitations on union workplace access will be lifted.
UK employment law currently recognises three types of employment status: (i) employees; (ii) workers (which is inclusive of employees); and (iii) self-employed contractors. An individual’s employment status determines the statutory employment rights to which they are entitled to (if any), and employment status has become a hot topic before the Employment Tribunal in recent years.
The Labour government has committed to carrying out a consultation on employment status as part of a move towards a single status of ‘worker’ and a simplified two-part framework for employment status. The Labour government has also stated that they will strengthen the rights and protections of the self-employed, including the right to a written contract, action to tackle late payments, and extending health and safety and blacklisting protections to the self-employed, along with strengthening trade union rights.
Further updates
We will provide a further update once the Labour government publishes draft legislation implementing these changes. In the meantime, we will continue to work with our clients to navigate the changing employment landscape in the UK.
Gibson Dunn lawyers are available to assist in addressing any questions you may have about these developments. Please contact the Gibson Dunn lawyer with whom you usually work, any leader or member of the firm’s Labor and Employment practice group, or the following authors in London:
James A. Cox (+44 20 7071 4250, jcox@gibsondunn.com)
Georgia Derbyshire (+44 20 7071 4013, gderbyshire@gibsondunn.com)
Olivia Sadler (+44 20 7071 4950, osadler@gibsondunn.com)
*Finley Willits, a trainee solicitor in the London office, is not admitted to practice law.
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
Gibson Dunn’s Workplace DEI Task Force aims to help our clients develop creative, practical, and lawful approaches to accomplish their DEI objectives following the Supreme Court’s decision in SFFA v. Harvard. Prior issues of our DEI Task Force Update can be found in our DEI Resource Center. Should you have questions about developments in this space or about your own DEI programs, please do not hesitate to reach out to any member of our DEI Task Force or the authors of this Update (listed below).
Key Developments
On June 27, Tractor Supply issued a statement saying that it would “[e]liminate DEI roles and retire [its] current DEI goals,” along with ceasing support for Pride festivals and withdrawing its carbon emission goals. The statement came in response to a public pressure campaign waged against Tractor Supply by Robby Starbuck, a conservative activist and social media personality, who criticized Tractor Supply for its DEI commitments, support for Pride Month celebrations, contributions to the Democratic Party, and carbon emission goals, among other things. Starbuck urged his followers to boycott Tractor Supply and to send complaints to Tractor Supply’s corporate offices. After three weeks of public pressure, and a reduction in its stock price, Tractor Supply acceded to Starbuck’s demands. Starbuck immediately claimed victory following Tractor Supply’s announcement, saying that it “was the start of something big” and threatening to “expose a new company next week.” In response to Tractor Supply’s announcement, the National Black Farmers Association called on Tractor Supply’s president and CEO to step down, and threatened a boycott of its own.
On June 20, the State of Missouri filed a complaint against IBM in state court, alleging that the company is violating the Missouri Human Rights Act by using race and gender quotas in its hiring and basing employee compensation on participation in allegedly discriminatory DEI practices. See Missouri v. IBM, No. 24SL–CC02837 (Cir. Ct. of St. Louis Cty.). The complaint cites a leaked video in which IBM’s Chief Executive Officer and Board Chairman, Arvind Krishna, allegedly stated that all executives must increase representation of ethnic minorities in their teams by 1% each year in order to receive a “plus” on their bonus. The complaint also alleges that employees at IBM have been fired or suffered adverse employment actions because they failed to meet or exceed these targets. The Missouri Attorney General is seeking to permanently enjoin IBM and its officers from utilizing quotas in hiring and compensation decisions.
On July 1, a suit was filed against CBS Broadcasting by former Los Angeles news anchor Jeff Vaughn, alleging that CBS terminated his employment because he is “an older, white, heterosexual male.” See Vaughn v. CBS Broadcasting, No. 2:24-cv-05570 (C.D. Cal. 2024). Vaughn claims that CBS replaced him with a “younger minority news anchor” in violation of Section 1981, Title VII, and the Age Discrimination in Employment Act. The complaint points to public statements by CBS expressing its commitment to diversity, including statements discussing various representation goals. Vaughn, who is represented by America First Legal, is seeking over $5,000,000 in damages.
In a statement issued on June 28, the U.S. Department of Commerce said that it would not appeal the district court’s ruling in Nuziard v. Minority Business Development Agency, No. 4:23-cv-00278 (N.D. Tex. 2024). The court held that the racial presumption used by the Minority Business Development Agency (MBDA) in apportioning federal funds for minority business assistance violates the Fifth Amendment’s equal protection guarantee. The decision extended the Supreme Court’s reasoning in SFFA to federal agencies administering grant programs, holding that “[t]hough SFFA concerned college admissions, nothing in the decision indicates that the Court’s holding should be constrained to that context.” For a more detailed discussion of the Nuziard decision, see our prior update here. The Commerce Department’s statement said that while the Department “strongly disagree[s]” with the court’s ruling, its “primary goal is to ensure MBDA can continue to meet its mission to promote the growth and global competitiveness of minority business enterprises,” and it believes that the injunction imposed by the district court “does not currently prevent MBDA from continuing to fulfill its mission.”
On June 27, EEOC Commissioner Kalpana Kotagal encouraged workers’ rights attorneys to continue advocating for lawful DEI initiatives, including data collection aimed at ensuring equal employment opportunities. Kotagal’s address took place at the National Employment Lawyers Association’s annual conference in Philadelphia and followed panel discussions of conservative legal activists’ anti-DEI efforts. Kotagal commented on the “bleak” landscape but urged the audience not to give up, emphasizing that Title VII standards have not changed and citing “misinformation” and “scare tactics” as having blurred employers’ understanding of the legality of DEI programming. Kotagal acknowledged the litany of reverse-discrimination suits being brought by white employees in the wake of SFFA but insisted that “there’s a huge difference” between quotas, on the one hand, and “measuring and understanding the demographics of your workforce with an eye to breaking down barriers and equal opportunity,” on the other. She stated that employers can legally engage in “remedial and temporary affirmative action plans” and the key is ensuring that “individual decisions are not based on race.”
On June 27, a split Ninth Circuit panel reinstated a proposed class action in which the plaintiffs allege that Meta unlawfully favors visa holders over citizens when making hiring decisions in Rajaram v. Meta Platforms, Inc., No. 22-16870 (9th Cir. 2024). The plaintiff alleged that, despite being qualified, he was discriminatorily rejected by Meta for several jobs because he is as U.S. citizen and Meta prefers to hire noncitizens holding H1B visas because it can pay them lower wages. U.S. Magistrate Judge Laurel Beeler in the Northern District of California had dismissed the complaint, finding that U.S. citizens are not a protected class under Section 1981. The Ninth Circuit reversed. The majority noted that while race discrimination is different from citizenship discrimination, “it is not different in any way that is relevant to the text of 1981.” Judge VanDyke dissented, writing that “discrimination because of citizenship is not covered by Section 1981 because citizens inherently possess the rights enjoyed by citizens, even when noncitizens are preferenced over them.”
On June 24, the Equal Protection Project (EPP) filed a complaint with the U.S. Department of Education’s Office for Civil Rights (OCR) against Indiana University Columbus (IUC). The complaint alleges that IUC partners with the African American Fund Bartholomew County (AAFBC) to administer a scholarship that is restricted to African American students in violation of Title VI and the Equal Protection Clause of the Fourteenth Amendment. EPP contends that because IUC is a public institution receiving federal financial assistance, it cannot intentionally discriminate on the basis of race in any “program or activity,” regardless of any good intention. EPP requests that OCR initiate a formal investigation into IUC’s role in creating and promoting the scholarship and asks that it impose appropriate remedial relief.
On June 20, Illinois Attorney General Kwame Raoul and 18 other Democrat state attorneys general issued a public letter to the American Bar Association (ABA) defending the current criteria used in ABA accreditation, in response to a June 3 letter from Republican state AGs urging the ABA to remove this criteria from its accreditation process. The letter from the Democrat AGs argues that SFFA does not bar higher education institutions from encouraging a diverse applicant pool or creating non-hostile educational environments for underrepresented groups. The ABA is currently considering revisions to Standard 206 for accreditation, which governs diversity and inclusion within law schools. The letter was also addressed to “Fortune 100 CEOs and other organizations unfairly targeted for their commitment to diversity, equity, and inclusion,” noting that SFFA’s “narrow holding did not change the law for private businesses.”
On June 20, Do No Harm filed a complaint against the American Association of University Women (AAUW), alleging that the organization is violating Section 1981 by providing Focus Group Professions Fellowships only to “women from ethnic minority groups historically underrepresented in certain fields within the United States: Black or African American, Hispanic or Latino/a, American Indian or Alaskan Native, Asian, and Native Hawaiian or Other Pacific Islander.” See Do No Harm v. American Association of University Women, No. 1:24-cv-01782 (D.D.C. 2024). Do No Harm is proceeding on behalf of its medical student-members, who allegedly meet all of the other application requirements for the AAUW fellowship but “are ineligible to apply to the fellowship because of their race.” Do No Harm is seeking a preliminary injunction prohibiting AAUW from closing the application window, and a permanent injunction prohibiting AAUW from considering race when selecting grant recipients.
On June 20, a three-judge panel of the Michigan Court of Appeals issued an unpublished per curiam decision dismissing the appeal of two former General Motors employees who contended that they faced discrimination and were terminated because they are white. See Bittner v. General Motors, LLC, No. 366160 (Mich. Ct. App. 2024). As noted in the court’s opinion, GM terminated the plaintiffs’ employment after corroborating complaints from other employees claiming that the plaintiffs routinely used sexually derogatory, homophobic, and transphobic language. The plaintiffs asserted state-law claims of disparate treatment, disparate impact, hostile work environment, and civil conspiracy, but the trial court granted GM’s motion for summary disposition. The Court of Appeals affirmed, rejecting the plaintiffs’ assertion that a supervisor’s request that they remain respectful during a Juneteenth moment of silence was “direct evidence” of discrimination. Nor was the Court convinced by the plaintiffs’ purported circumstantial evidence of disparate treatment.
Media Coverage and Commentary:
Below is a selection of recent media coverage and commentary on these issues:
- The Washington Post, “DEI Programs toppled amid a surge of conservative lawsuits” (June 27): The Washington Post’s Peter Whoriskey and Julian Mark report that right-leaning legal groups filed more than 100 lawsuits challenging racial preferences and other efforts by corporations and the government to “address demographic disparities in business, government and education.” Following SFFA, according to Jason Schwartz, Gibson Dunn partner and co-chair of the firm’s Labor & Employment group, “[t]he cases are going pretty quickly and decisively against the government programs” because “[government] cases are harder to defend.” Whoriskey and Mark say that private companies have “more legal leeway to implement diversity programs,” but that recent litigation also has had a chilling effect on private companies, with many reconsidering their own diversity programs as a defensive measure to reduce litigation risk.
- The Wall Street Journal, “Tractor Supply Retreats from DEI Amid Conservative Backlash” (June 27): Sarah Nassauer and Sabela Ojea of The Wall Street Journal report that Tractor Supply Company, a rural retailer best known for its animal feed and workwear sales, is abandoning its DEI and environmental initiatives in response to weeks of social media criticism from Robby Starbuck, a prominent conservative political commentator. Starbuck encouraged his followers to boycott Tractor Supply because of its stated political, diversity, and environmental goals. Nassauer and Ojea report that the company announced it would eliminative jobs focused on DEI, stop sponsoring LGBTQ+ pride festivals, and no longer submit data to LGBTQ+ advocacy group the Human Rights Campaign. Nassauer and Ojea note that “Tractor Supply’s core customer base is more rural and male than general big-box retailers,” with “customers in regions that tend to vote for more conservative political candidates.” In a statement, Tractor Supply said that it had “heard from customers that we have disappointed them,” and it had “taken this feedback to heart.”
- The Associated Press, “Black farmers’ association calls for Tractor Supply CEO’s resignation after company cuts DEI efforts” (July 2): Wyatte Grantham-Philips and Haleluya Hadero of the Associated Press report on calls from the National Black Farmers Association (NBFA) for Tractor Supply’s CEO Hal Lawton to step down. Grantham-Philips and Hadero say that the calls for Lawton’s resignation come in response to Tractor Supply’s recent announcement that it would stop most of its corporate diversity and climate advocacy efforts. Tractor Supply announced the changes following a pressure campaign from conservative activists who took issue with what Grantham-Philips and Hadero call “the company’s work to be more socially inclusive and to curb climate change.” John Boyd Jr., president and founder of the NBFA, said that he was “appalled” by Tractor Supply’s decision, and warned that “Black farmers are going to start fighting back,” including by considering calling for a boycott of Tractor Supply. Indeed, Grantham-Philips and Hadero report that some customers have “already decided to take their business elsewhere,” deciding that they can “no longer support Tractor Supply if its announcement reflected its beliefs.”
- The Wall Street Journal, “Banks, Law and Consulting Firms are Watering Down Their Diversity Recruiting Programs” (June 20): The Wall Street Journal’s Kailyn Rhone reports that “white-collar companies,” once champions of programs to recruit diverse employees, are now quietly downplaying these programs. Rhone says that these changes include minimizing use of terminology like “DEI,” opening diversity programs to all applicants, and omitting references to DEI programs from annual reports. Rhone cites accounting firm PricewaterhouseCoopers as an example, noting that it recently altered the eligibility criteria for its Start internship, shifting the focus from “traditionally underrepresented” minority applicants to students of “diverse backgrounds” generally. Similarly, Rhone notes that JPMorgan Chase clarified that its Black and Hispanic & Latino fellowship programs are available to all students, regardless of race. And, Rhone says, consulting firm McKinsey & Co. also recently removed the requirement that candidates for its summer business analyst program “self-identify as a member of a historically underrepresented group.” According to Rhone, some minority job seekers worry that the changes “could erode a path for diverse candidates to find internships and entry-level roles.”
- The Dallas Morning News, “131 college scholarships put on hold or modified due to Texas DEI ban, documents show” (June 17): Marcela Rodrigues and Philip Jankowski of The Dallas Morning News report that a new Texas law banning DEI programs at public universities has frozen or modified over 130 college scholarships state-wide. Known as SB 17, the law prohibits Texas public colleges from administering programs designed for students of specific races or genders. Many of the scholarships affected are administered by the schools but funded through private donations. According to officials at public universities across Texas, SB 17 has triggered review of thousands of scholarships, in some cases leading to the alteration or elimination of gender and racial eligibility requirements.
- The Washington Post, “Most Americans approve of DEI, according to Post-Ipsos poll” (June 18): The Washington Post’s Taylor Telford, Emmanuel Felton, and Emily Guskin report on a recent poll finding that the majority of Americans believe DEI programs are “a good thing.” The poll indicated that support is even higher for certain types of programming, like internships for underrepresented groups and anti-bias trainings, and that respondents expressed greater support for DEI programs after they were given a detailed description of them. The authors note that “one effort was universally unpopular: financial incentives for managers who achieve diversity goals.” Joelle Emerson, chief executive of Paradigm, a DEI consultancy, said that she believes “that the vast majority of peoples’ values align with what this work actually entails,” but that the concept of DEI might need some rebranding.
- Law360 Employment Authority, “A Year After Justices Scrap Affirmative Action, DEI Rebounds” (June 28): Law360’s Anne Cullen reports that DEI consultants are seeing a gradual resurgence in corporate interest regarding DEI initiatives. Cullen acknowledges that, although DEI advocates have had some notable wins in the courts, lawsuits filed by conservative groups have had a dramatic chilling effect on corporate programs—including an outsized effect on small businesses and organizations without the financial capacity to mount a defense. But experts in the field say that the tide may be turning, with some noticing “a bottoming out, and some new entrants” to the corporate diversity field. Other consultants report observing “resurging interest” from corporate clients who “want to roll their sleeves up and do the work.” Experts recommend that companies be willing “to adapt and pivot,” including rebranding their programs to move away from the “DEI” label.
Case Updates:
Below is a list of updates in new and pending cases:
1. Contracting claims under Section 1981, the U.S. Constitution, and other statutes:
- Californians for Equal Rights Foundation v. City of San Diego, No. 3:24-cv-00484 (S.D. Cal. 2024): On March 12, 2024, the Californians for Equal Rights Foundation filed a complaint on behalf of members who are “ready, willing and able” to purchase a home in San Diego, but are ineligible for a grant or loan under the City’s BIPOC First-Time Homebuyer Program. Plaintiffs allege that the program discriminates on the basis of race in violation of the Equal Protection Clause.
- Latest update: On June 18, 2024, the City of San Diego filed a motion for judgment on the pleadings. The City argued that the complaint does not include any allegations against the City, and instead alleges a “fictitious [agency] relationship” with the other defendants, the Housing Authority of the City of San Diego and the San Diego Housing Commission. The City also argued that even if the Plaintiff’s agency allegations were accepted as true, its claim against the Housing Authority and City still fails because “a local government may not be sued under § 1983 for an injury inflicted solely by its employees or agents.”
- Valencia AG, LLC v. New York State Off. of Cannabis Mgmt. et al., No. 5:24-cv-116-GTS (N.D.N.Y. 2024): On January 24, 2024, Valencia AG, a cannabis company owned by white men, sued the New York State Office of Cannabis Management for discrimination, alleging that New York’s Cannabis Law and regulations favored minority-owned and women-owned businesses. The regulations include goals to promote “social & economic equity” (SEE) applicants, which the plaintiff claims violate the Fourteenth Amendment’s Equal Protection Clause and Section 1983. On March 13, 2024, the plaintiff filed an amended complaint, naming only two New York state officials as defendants in their official capacity. The plaintiff sought a permanent injunction against the regulations and a declaration that the use of race and sex in the New York Cannabis Law violates the Fourteenth Amendment. On April 24, 2024, the defendants moved to dismiss the amended complaint for lack of standing and failure to state an Equal Protection Clause claim, arguing that even without the contested policy the plaintiff would not have received the license due to their low “position in the queue.”
- Latest update: On June 20, 2024, the defendants filed a reply in support of their motion to dismiss. The defendants argued that the plaintiff lacks standing because its microbusiness license will be reviewed in the November queue under a recently adopted board resolution. Moreover, the defendants asserted that there is no risk of injury because “the Board and Office have interpreted the Cannabis Law and implementing regulations to be satisfied by front-end measures to aid [minority] SEE applicants such as community outreach, low-burden applications, and assistance if an application is found to be defective,” and that the plaintiff has not demonstrated that the defendants will deviate from this interpretation. The defendants also noted that they have submitted affidavits indicating that “applications are being reviewed solely for completeness and correctness, and thus that the race and gender of an applicant will play no role in whether an application is approved.”
2. Employment discrimination and related claims:
- Sullivan v. Howard Univ., No. 1:24-cv-01924 (D.D.C. 2024): On July 1, 2024, a male administrator at Howard University filed suit against the university, claiming that he experienced sex discrimination and retaliation when he was transferred to another department.
- Latest Update: The docket does not reflect that Howard University has been served.
- Gerber v. Ohio Northern Univ., No. 2023-1107-CVH (Ohio. Ct. Common Pleas Hardin Cty. 2024): On June 30, 2023, a law professor sued his former employer, Ohio Northern University, for terminating his employment after an internal investigation determined that he bullied and harassed other faculty members. On January 23, 2024, the plaintiff, now represented by America First Legal, filed an amended complaint. The plaintiff claims that his firing was actually in retaliation for his vocal and public opposition to the university’s stated DEI principles and race-conscious hiring, which he believed were illegal. The plaintiff alleged that the investigation and his termination breached his employment contract, violated Ohio civil rights statutes, and constituted various torts, including defamation, false light, conversion, infliction of emotional distress, and wrongful termination in violation of public policy.
- Latest update: On June 17, 2024, both parties filed motions for summary judgment. The defendants argued that the court should grant summary judgment because plaintiff’s claims of retaliation for expressing his views on DEI policies are not backed by evidence, including because he “advanced through the ranks at ONU” while making prolific remarks against DEI and affirmative action since at least 2005. The plaintiff moved for summary judgment on his breach-of-contract and defamation claims.
- Weitzman v. Fred Hutchinson Cancer Center, No. 2:24-cv-00071-TLF (W.D. Wash. 2024): On January 16, 2024, a white Jewish female former employee sued the medical center where she used to work, alleging that she was terminated for expressing her discomfort with DEI-related content shared in the workplace by coworkers, objecting to DEI-related training, and expressing her political opposition to DEI-aligned ideologies. She also claimed that her employer failed to act when she was allegedly discriminated against because of her religion and race by other coworkers. The plaintiff alleged that her employer’s conduct constituted racial discrimination, a hostile work environment, and retaliation in violation of the Washington Law Against Discrimination and Section 1981; discrimination and retaliation on the basis of political ideology in violation of the Seattle Municipal Code; and intentional infliction of emotional distress and wrongful termination in violation of public policy under common law.
- Latest update: On June 25, the court granted the parties’ joint stipulation for dismissal and the claim was dismissed with prejudice.
- DiBenedetto v. AT&T Servs., Inc., No. 21-cv-4527 (N.D. Ga. 2021): On November 2, 2021, the plaintiff, a white male former executive, brought claims against AT&T under Title VII, Section 1981, and the Age Discrimination in Employment Act (ADEA), alleging that he was wrongfully terminated due to his race, gender, and age.
- Latest update: On June 26, the parties jointly stipulated and agreed to the dismissal with prejudice of all claims in this action.
- Newman v. Elk Grove Educ. Ass’n., No. 2:24-cv-01487-DB (E.D. Cal. 2024): On May 24, 2024, a white teacher at the Elk Grove Unified School District in Sacramento, California, sued the teachers’ union after it created an executive board position called the “BIPOC At-Large Director” open only to those who “self-identify” as “African American (Black), Native American, Alaska Native, Native Hawai’ian, Pacific Islander, Latino (including Puerto Rican), Asian, Arab, and Middle Eastern.” The plaintiff alleges that he is a union member who “wants to run for union office to address the District’s recent adoption of what he believes to be aggressive and unnecessary Diversity, Equity & Inclusion (‘DEI’) policies,” but is ineligible for this board seat because of his race. The plaintiff alleges that he therefore has fewer opportunities to obtain a board seat than non-white union members. He has brought claims against the union under Title VII of the Civil Rights Act of 1964 and the California Fair Employment and Housing Act.
- Latest update: The defendant’s response to the complaint is due on August 26, 2024.
- Faculty, Alumni, and Students Opposed to Racial Preferences (FASORP) v. Northwestern University, No. 1:24-cv-05558 (N.D. Ill. 2024): A nonprofit advocacy group filed suit against Northwestern University, alleging that Northwestern University is violating Title VI, Title IX, and Section 1981 by considering race and sex in law school faculty hiring decisions. The suit also claims that student editors of the Northwestern University Law Review give discriminatory preferences to “women, racial minorities, homosexuals, and transgender people when selecting their members and edits,” as well as when choosing articles to include in the Law Review. The plaintiff is seeking to enjoin Northwestern from (1) considering race, sex, sexual orientation, or gender identity in the appointment, promotion, retention, or compensation of its faculty or the selection of articles, editors, and members of the Northwestern University Law Review, and (2) soliciting any information about the race, sex, sexual orientation, or gender identity of faculty candidates or applicants for the Law Review. The plaintiff is also asking the court to order Northwestern to establish a new policy for selecting faculty and Law Review articles, editors, and members, and to appoint a court monitor to oversee all related decisions.
- Latest update: The docket does not reflect that the defendant has been served.
Gibson Dunn’s lawyers are available to assist in addressing any questions you may have regarding these developments. Please contact the Gibson Dunn lawyer with whom you usually work, any member of the firm’s Labor and Employment practice group, or the following practice leaders and authors:
Jason C. Schwartz – Partner & Co-Chair, Labor & Employment Group
Washington, D.C. (+1 202-955-8242, jschwartz@gibsondunn.com)
Katherine V.A. Smith – Partner & Co-Chair, Labor & Employment Group
Los Angeles (+1 213-229-7107, ksmith@gibsondunn.com)
Mylan L. Denerstein – Partner & Co-Chair, Public Policy Group
New York (+1 212-351-3850, mdenerstein@gibsondunn.com)
Zakiyyah T. Salim-Williams – Partner & Chief Diversity Officer
Washington, D.C. (+1 202-955-8503, zswilliams@gibsondunn.com)
Molly T. Senger – Partner, Labor & Employment Group
Washington, D.C. (+1 202-955-8571, msenger@gibsondunn.com)
Blaine H. Evanson – Partner, Appellate & Constitutional Law Group
Orange County (+1 949-451-3805, bevanson@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
Many multinational companies based in or operating in the European Union will need to restructure their sanctions compliance programs to avoid potential sanctions violations and enforcement risks going forward.
Amidst a plethora of new restrictions on specific goods, vessels and parties, the EU’s 14th package against Russia (June 24, 2024) and latest Belarus sanctions (June 29, 2024) include a few fundamental changes in the territorial reach and substantive design of EU sanctions bolstering the EU’s anti-circumvention toolbox. Many multinational companies based in or operating in the European Union will need to restructure their sanctions compliance programs to avoid potential sanctions violations and enforcement risks going forward.
1. New Provision Changes the Reach of Russia Sectoral Sanctions as regards Non-EU Subsidiaries of EU Entities
According to the new Article 8a of Regulation (EU) 833/2014 (“Reg 833/2014”), EU companies shall undertake their best efforts to ensure that any non-EU company they own or control (“Non-EU Subsidiary”) does not participate in activities that undermine EU sectoral sanctions against Russia under Reg 833/2014.
This provision changes the treatment of Non-EU Subsidiaries under EU sanctions. To date, companies have been relying on general jurisdictional provisions laid down in each EU sanctions regulation (such as Article 13 of Reg 833/2014), according to which non-EU companies shall comply with EU sanctions only “in respect of any business done in whole or in part within the EU.” If a non-EU company maintained no nexus to the EU territory in its operations, it would not be obliged to comply with EU sanctions, even if it was a subsidiary of an EU company. In turn, as per Consolidated FAQs of the European Commission, the EU parent company was bound only in respect of its own actions, for example if clearing/green-lighting decisions taken by the Non-EU Subsidiary. It was understood that the EU parent company would not incur any liability for an independent conduct of a Non-EU Subsidiary it did not have any impact on. A similar understanding of who can be liable for sanctions violations is in fact common to many Western sanctions jurisdictions.
The new provision of Article 8a of Reg 833/2014 changes these dynamics. Remarkably, the jurisdictional provisions of Article 13 remain intact despite the amendment, so that non-EU companies doing business entirely outside the EU continue to be not subject to EU jurisdiction – this allows the EU legislator to uphold its regular claim that EU sanctions are never extraterritorial. However, the new provision of Article 8a forces EU parent companies, in order to avoid direct liability risks for themselves, to ensure that their Non-EU Subsidiaries practically comply with EU sanctions.
The new provision already instilled a debate of its enforceability as the “best efforts” requirement is seen to be too vague. Criminal liability will ultimately be defined by the interplay of Member State criminal laws and EU sanctions regulations, and in this respect, Article 8a might open the door for criminal enforcement agencies to prosecute EU companies in connection with the conduct of Non-EU Subsidiaries. One liability option seems to be that sanctions-undermining activities of a Non-EU Subsidiary would be attributed to the EU parent company as its own sanctions violation, if such an attribution is possible under criminal or administrative laws of the respective Member State. Alternatively, the executives of the EU parent company could be exposed to the criminal liability “by omission,” as for example practiced in German or Dutch legal systems. The respective offense would be a sanctions violation by virtue of failure to undertake necessary measures within the meaning of Article 8a of Reg 833/2014. In this regard, the widespread understanding that EU companies and their executives are not obliged (in a sense of a “guarantor’s duty” or “duty to care”) to ensure EU sanctions compliance in Non-EU Subsidiaries can no longer be upheld, at least in the context of sectoral sanctions against Russia. Instead, diligent and robust policies, procedures and systems should be put in place to avoid to the extent possible conduct by the Non-EU-Subsidiary that could be considered “undermining” EU sanctions.
With regard to the application of the new provision, Recitals 27-30 to Amending Regulation (EU) 2024/1745 provide for helpful clarifications:
- “Ownership” and “control” of a non-EU company are defined in the same way as they are for party-based restrictions under financial sanctions; i.e., 50% or more of the proprietary rights for “ownership” and certain rights to exercise decisive influence for “control.”
- Activities that undermine EU sanctions under Reg 833/2014 are those resulting in an effect that those restrictive measures seek to prevent. The Recitals use the example that a recipient in Russia obtains goods, technology, financing, or services of a type that is subject to prohibitions under Reg 833/2014, indicating that the prevention of such an outcome is at the core of the new provision of Article 8a.
- With regard to the term “best efforts,” the Recitals clarify that:
- “Best efforts” comprise all actions suitable and necessary to achieve the result of preventing the undermining of EU sanctions under Reg 833/2014.
- Those actions can include, for example, the implementation of appropriate policies, controls, and procedures to mitigate and manage risk effectively, considering factors such as the country of establishment, the business sector, and the type of activity of the non-EU company owned or controlled by the EU company.
- At the same time, best efforts should be understood as comprising only actions that are feasible for the EU company in view of its nature, its size, and the relevant factual circumstances, particularly the degree of effective control over the non-EU company. In this context, the situation where the EU company is not able to exercise control over a non-EU company due to the legislation of a third country should be taken into account.
The placement of these clarifications in the Recitals indicates the challenges to find unanimity in introducing unequivocal requirements into the binding provisions of Reg 833/2014, so that they rather provide interpretative aid.
Notably, the new provision was adopted only within sectoral (Reg 833/2014) but not within party-based financial sanctions against Russia (Regulation (EU) 269/2014). However, within the new package of sanctions against Belarus adopted a few days later, the new provision with the same wording was added to the Belarus Sanctions Regulation (new Article 8h of Regulation (EU) 765/2006), which covers both sectoral and party-based financial measures.
It remains to be seen whether the new provision becomes a standard for EU sanctions in general. However, at least with respect the EU’s sectoral sanctions on Russia and for the EU’s Belarus sanctions, companies need to act now to extend their EU sanctions compliance programs to cover Non-EU Subsidiaries of EU parent companies.
2. Mandatory Sanctions Risk Assessment for Companies Trading with Common High Priority Items
Starting from the 12th sanctions package against Russia, the EU has begun to introduce novel obligations for companies trading with so called “common high priority items” (“CHPI”), i.e. items used in Russian military systems found on the battlefield in Ukraine or critical to the development, production or use of Russian military systems. In particular, the so called “No Russia Clause” of Article 12g of Reg 833/2014 obliged EU companies trading with CHPI in third countries (except a few partner countries) to contractually prohibit re-exportation to Russia or for use in Russia, and to provide for adequate remedies in the event of a breach of this contractual obligation.
The 14th sanctions package establishes further obligations for such companies. In particular, the new Article 12ga of Reg 833/2014 introduces a so called “No Russia IP Clause” obliging companies to contractually prohibit their third-country counterparts to use or sublicense IP rights and trade secrets in connection with CHPI being delivered to Russia or for use in Russia, and to provide for adequate remedies in the event of a breach of this contractual obligation.
Furthermore, the new Article 12gb of Reg 833/2014 obliges companies in CHPI industries, as of December 26, 2024, to conduct risk assessments as regards exportation to/for use in Russia, to ensure that those risk assessments are documented and kept up-to-date, and to implement appropriate policies, controls and procedures to mitigate and effectively manage such risks. EU persons must further ensure that non-EU companies owned or controlled by them are equally implementing these requirements. The same obligations apply within the framework of EU sanctions against Belarus by virtue of new Article 8ga of Regulation (EU) 765/2006.
This is not the first call for companies to implement such enhanced due diligence procedures at the EU level. On September 7, 2023, the European Commission provided its Guidance on Enhanced Due Diligence to shield against Russia sanctions circumvention, whereas the less detailed Notice 2022/C 145 I/01 called for due diligence measures as early as on April 1, 2022. Article 12gb of Reg 833/2014 is the first provision which transposes these calls into a binding obligation, albeit only for CHPI industries and in respect of CHPI items.
At the same time, Recital 36 to Amending Regulation (EU) 2024/1745 makes it clear that, if an EU operator in any industry failed to carry out appropriate due diligence, in particular on the basis of publicly or readily available information, it may not invoke the protection against liability granted under EU sanctions regulations to those who did not know, and had no reasonable cause to suspect, that their actions would infringe EU sanctions. Therefore, while companies in CHPI industries have no choice but to implement required due diligence mechanisms due to the new provision, companies in other industries can likewise be advised to do so in order to shield against substantial liability risks.
Gibson Dunn’s lawyers are available to assist in addressing any questions you may have regarding these issues. For additional information about how we may assist you, please contact the Gibson Dunn lawyer with whom you usually work, the authors, or the following leaders and members of the firm’s International Trade practice group:
Europe:
Attila Borsos – Brussels (+32 2 554 72 10, aborsos@gibsondunn.com)
Patrick Doris – London (+44 207 071 4276, pdoris@gibsondunn.com)
Michelle M. Kirschner – London (+44 20 7071 4212, mkirschner@gibsondunn.com)
Penny Madden KC – London (+44 20 7071 4226, pmadden@gibsondunn.com)
Irene Polieri – London (+44 20 7071 4199, ipolieri@gibsondunn.com)
Benno Schwarz – Munich (+49 89 189 33 110, bschwarz@gibsondunn.com)
Nikita Malevanny – Munich (+49 89 189 33 224, nmalevanny@gibsondunn.com)
Melina Kronester – Munich (+49 89 189 33 225, mkronester@gibsondunn.com)
Vanessa Ludwig – Frankfurt (+49 69 247 411 531, vludwig@gibsondunn.com)
United States:
Ronald Kirk – Co-Chair, Dallas (+1 214.698.3295, rkirk@gibsondunn.com)
Adam M. Smith – Co-Chair, Washington, D.C. (+1 202.887.3547, asmith@gibsondunn.com)
Stephenie Gosnell Handler – Washington, D.C. (+1 202.955.8510, shandler@gibsondunn.com)
Christopher T. Timura – Washington, D.C. (+1 202.887.3690, ctimura@gibsondunn.com)
David P. Burns – Washington, D.C. (+1 202.887.3786, dburns@gibsondunn.com)
Nicola T. Hanna – Los Angeles (+1 213.229.7269, nhanna@gibsondunn.com)
Courtney M. Brown – Washington, D.C. (+1 202.955.8685, cmbrown@gibsondunn.com)
Amanda H. Neely – Washington, D.C. (+1 202.777.9566, aneely@gibsondunn.com)
Samantha Sewall – Washington, D.C. (+1 202.887.3509, ssewall@gibsondunn.com)
Michelle A. Weinbaum – Washington, D.C. (+1 202.955.8274, mweinbaum@gibsondunn.com)
Chris R. Mullen – Washington, D.C. (+1 202.955.8250, cmullen@gibsondunn.com)
Sarah L. Pongrace – New York (+1 212.351.3972, spongrace@gibsondunn.com)
Anna Searcey – Washington, D.C. (+1 202.887.3655, asearcey@gibsondunn.com)
Audi K. Syarief – Washington, D.C. (+1 202.955.8266, asyarief@gibsondunn.com)
Scott R. Toussaint – Washington, D.C. (+1 202.887.3588, stoussaint@gibsondunn.com)
Claire Yi – New York (+1 212.351.2603, cyi@gibsondunn.com)
Shuo (Josh) Zhang – Washington, D.C. (+1 202.955.8270, szhang@gibsondunn.com)
Asia:
Kelly Austin – Hong Kong/Denver (+1 303.298.5980, kaustin@gibsondunn.com)
David A. Wolber – Hong Kong (+852 2214 3764, dwolber@gibsondunn.com)
Fang Xue – Beijing (+86 10 6502 8687, fxue@gibsondunn.com)
Qi Yue – Beijing (+86 10 6502 8534, qyue@gibsondunn.com)
Dharak Bhavsar – Hong Kong (+852 2214 3755, dbhavsar@gibsondunn.com)
Felicia Chen – Hong Kong (+852 2214 3728, fchen@gibsondunn.com)
Arnold Pun – Hong Kong (+852 2214 3838, apun@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.
The Final Regulations generally apply to qualified facilities placed in service in tax years ending after June 25, 2024.
On June 25, 2024, the IRS and Treasury published final Treasury regulations (the “Final Regulations”) on the prevailing wage and apprenticeship requirements (the “PWA Requirements”) that taxpayers must[1] satisfy to receive the full amount[2] of certain tax credits provided for in the Inflation Reduction Act of 2022 (the “IRA”).[3] The Final Regulations build upon the proposed Treasury regulations (the “Proposed Regulations”) issued on August 30, 2023 (our earlier alert on the Proposed Regulations is available here)
The Final Regulations generally apply to qualified facilities placed in service in tax years ending after June 25, 2024. For facilities that either (1) began construction on or after January 29, 2023 and before June 25, 2024 or (2) were placed in service in taxable years ending on or before June 25, 2024, taxpayers may choose to apply either the Final Regulations or the Proposed Regulations, as long as the chosen guidance is applied consistently.[4]
Background
At a high level, the “prevailing wage requirement” requires that all laborers and mechanics employed by a taxpayer (or a contractor or subcontractor) claiming an applicable credit[5] be paid wages for construction, alteration, or repair of the applicable facility that are not less than the “prevailing” wage for the type of work performed. The “apprenticeship requirement” generally requires a certain percentage of labor hours be performed by apprentices working under the supervision of experienced laborers. Our prior alert (which is available here) summarizes these requirements in greater detail.
Key Changes to Prevailing Wage Requirements
The Final Regulations provide several crucial clarifications to earlier guidance (including the Proposed Regulations) relating to the prevailing wage requirement.
Timing of Wage Determination
Taxpayers generally must consult guidance published by the Wage and Hour Division of the Department of Labor to determine prevailing wages. Unlike the Proposed Regulations, which would have set the applicable wage rate as the one in effect at the beginning of construction, the Final Regulations stipulate that the applicable wage rate is the one in effect when a contract for the construction, alteration, or repair of a facility is executed. Only if there is no contract is the timing of the wage determination determined on when construction begins. If a taxpayer enters into a generalized contract for alteration or repair work (i.e., a contract that does not call for any specific work) for an indefinite period of time, the applicable wage rates must be refreshed on an annual basis, so taxpayers cannot lock in lower wages (or be locked into higher wages) through vague, long-term contracts.
Curing Failures to Pay Appropriate Wages
In some instances, taxpayers seeking to fix failures to pay appropriate wages can avoid penalties if they self-correct. The Final Regulations modify the Proposed Regulations by specifying that self-correction must be made by the last day of the first month following the end of the calendar quarter in which the failure occurred (as opposed to the Proposed Regulations, which would have required the correction payment to be made within 30 days after the taxpayer became aware of the error or the date on which the increased credit was claimed).
Additionally, the Final Regulations add a further clarification to these correction payments rules: if a former worker cannot be found, a taxpayer will be deemed to make a correction payment if it complies with state unclaimed property laws and all federal and state withholding information reporting requirements. This provision addresses the concern of some taxpayers, expressed after the issuance of the Proposed Regulations, that correction payments might not be possible if an underpaid worker could not be found.[6]
Key Changes to Apprenticeship Requirements
The Final Regulations also include important clarifications related to the apprenticeship requirements, including those highlighted below.
Applicability After Facility is Placed in Service
Under the Proposed Regulations, it was unclear whether the apprenticeship requirements continued to apply after a particular facility was placed in service. The Final Regulations make clear that the apprenticeship requirements cease to apply to alteration or repair work once a facility is placed in service.
Threshold Number of Construction Employees
The Final Regulations confirm that the apprenticeship requirements apply only to taxpayers, contractors, or subcontractors who employ four or more individuals to perform construction, alteration, or repair work in connection with the construction of a qualified facility. The Final Regulations clarify that the four-employee threshold applies over the course of the construction, regardless of whether the employees are employed at the same location or at the same time, increasing the likelihood that the apprenticeship requirements will apply to small contractors or subcontractors.[7]
Requests to Registered Apprenticeship Programs
The Proposed Regulations provided that if a taxpayer made a request for apprentices to a registered apprenticeship program and received a denial or nonresponse, the taxpayer must submit additional requests every 120 days in order to meet the good faith effort exception (to the extent applicable, this exception excuses a taxpayer from complying with the apprenticeship requirements). In response to comments, the Final Regulations relaxed this requirement to provide that the taxpayer only needs to submit additional requests 365 days (or, if applicable, 366 days) after the denial of a previous request to continue to satisfy the good faith effort exception.
Key Changes to Recordkeeping Requirements
The Final Regulations include some important adjustments to the recordkeeping requirements for the PWA Requirements.
Personal Identifying Information
The Proposed Regulations would have required the collection of sensitive personal identifying information, including social security numbers, with respect to the employees of the taxpayer and the employees of contractors or subcontractors. The Final Regulations alter this requirement to provide that only the last four digits of an employee’s social security number must be collected.
Options for Compliance
The Final Regulations provide three ways to comply with the recordkeeping requirements:
- Taxpayers may collect and physically retain relevant records from contractors and subcontractors, with certain personally identifiable information redacted so long as unredacted information is made available to the IRS upon request.
- Contractors and subcontractors may provide relevant records to a third-party vendor to physically retain on behalf of the taxpayer, with certain sensitive information redacted so long as unredacted information is made available to the IRS upon request.
- Taxpayers, contractors, and subcontractors may each physically retain the relevant unredacted records for their own employees, and those unredacted records must be made available to the IRS upon request.
[1] Compliance with the PWA Requirements is not required for facilities (i) that have a maximum net output or storage capacity of less than one megawatt or (ii) the construction of which began before January 29, 2023.
[2] Technically, the baseline tax credit is multiplied by five if the PWA Requirements are met, resulting in a tax credit amount that traditionally has been considered the full amount of the federal income tax credits that may be claimed in respect of clean energy technologies. This full credit amount also can be increased by so-called adders, such as the domestic content adder and the energy community adder. Please see our prior alerts on these adders, which can be found here, here, and here, respectively.
[3] As was the case with the so-called Tax Cuts and Jobs Act, the Senate’s reconciliation rules prevented Senators from changing the Act’s name, and the formal name of the so-called Inflation Reduction Act is actually “An Act to provide for reconciliation pursuant to title II of S. Con. Res. 14.” In addition to tax credit guidance, the Final Regulations also include guidance regarding the PWA Requirements under section 179D, which provides a deduction for the cost of energy efficient commercial building property placed in service during the taxable year.
[4] Unless indicated otherwise, all “section” references are to the Internal Revenue Code of 1986, as amended.
[5] Tax credits with a prevailing wage or apprenticeship requirement include those credits provided for under sections 30C, 45, 45L, 45Q, 45U, 45V, 45Y, 45Z, 48, 48C, and 48E.
[6] The preamble to the Proposed Regulations stated, “[t]he Treasury Department and the IRS expect that taxpayers will be able to establish correction payments even when a former laborer or mechanic cannot be located.”
[7] The Final Regulations clarify that the hours devoted to the performance of construction, alteration, or repair work by any qualified apprentice in excess of the applicable ratio requirement will be counted towards the total labor hours but will not be counted as hours performed by qualified apprentices for purposes of the labor hours requirement applicable to qualified apprentices.
Gibson Dunn lawyers are available to assist in addressing any questions you may have about these developments. To learn more about these issues, please contact the Gibson Dunn lawyer with whom you usually work, any member of the firm’s Tax, Cleantech, or Power and Renewables practice groups, or the following authors:
Tax:
Michael Q. Cannon – Dallas (+1 214.698.3232, mcannon@gibsondunn.com)
Matt Donnelly – Washington, D.C. (+1 202.887.3567, mjdonnelly@gibsondunn.com)
Josiah Bethards – Dallas (+1 214.698.3354, jbethards@gibsondunn.com)
Blake Hoerster– Dallas (+1 214.698.3180, bhoerster@gibsondunn.com)
Duncan Hamilton– Dallas (+1 214.698.3135, dhamilton@gibsondunn.com)
Nathan Sauers – Houston (+1 346.718.6715, nsauers@gibsondunn.com)
Cleantech:
John T. Gaffney – New York (+1 212.351.2626, jgaffney@gibsondunn.com)
Daniel S. Alterbaum – New York (+1 212.351.4084, dalterbaum@gibsondunn.com)
Adam Whitehouse – Houston (+1 346.718.6696, awhitehouse@gibsondunn.com)
Power and Renewables:
Peter J. Hanlon – New York (+1 212.351.2425, phanlon@gibsondunn.com)
Nicholas H. Politan, Jr. – New York (+1 212.351.2616, npolitan@gibsondunn.com)
© 2024 Gibson, Dunn & Crutcher LLP. All rights reserved. For contact and other information, please visit us at www.gibsondunn.com.
Attorney Advertising: These materials were prepared for general informational purposes only based on information available at the time of publication and are not intended as, do not constitute, and should not be relied upon as, legal advice or a legal opinion on any specific facts or circumstances. Gibson Dunn (and its affiliates, attorneys, and employees) shall not have any liability in connection with any use of these materials. The sharing of these materials does not establish an attorney-client relationship with the recipient and should not be relied upon as an alternative for advice from qualified counsel. Please note that facts and circumstances may vary, and prior results do not guarantee a similar outcome.